MKS Faces A Credibility Test As Stock Slump Collides With Record Semiconductor Guidance
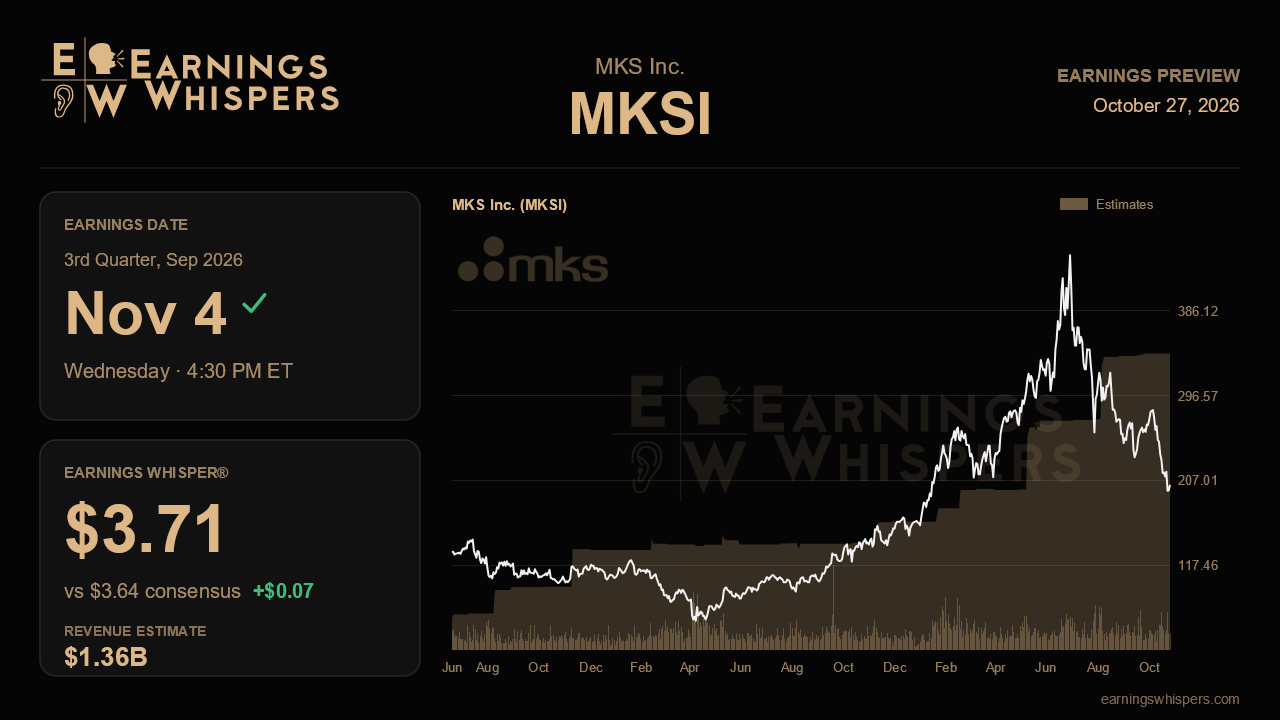
MKS heads into its third-quarter report with one of the sharper disconnects in semiconductor equipment. Management used its last call to raise nearly every operating target, describe chemistry equipment demand as the strongest in company history, and extend visibility through 2027. Since then, the stock has fallen about 30%, while the S&P 500 was roughly flat. Either the market is pricing in an end to the upswing that management says is still building, or the shares have run ahead of the fundamentals on the downside. The November 4 release, due after the close, should help settle which.
The Street expects earnings of $3.64 a share on revenue of $1.36 billion. That would be an 88.6% jump in profit and 37.7% revenue growth from a year ago, which is acceleration, not just strength. Management guided to $3.27 to $3.89 a share on revenue of $1.31 billion to $1.39 billion, with midpoints of about $3.58 and $1.35 billion. Consensus sits comfortably inside that range and slightly above the middle, so analysts are assuming modest execution upside rather than a blowout. The whisper number of $3.71 is a bit higher, a small but meaningful sign that some investors expect MKS to keep beating its own guidance, as it did last quarter when revenue of $1.25 billion cleared a $1.2 billion guide.
The segment detail matters more than the headline figures. Semiconductor revenue was guided to about $630 million, implying growth of more than 50% from a year ago, after 28% growth in the second quarter and 13% in the first. Delivering that figure would confirm management's claim that MKS is outgrowing wafer fab equipment spending during this ramp. Investors should also listen for whether the company holds or raises its capacity to support $200 billion to $250 billion of industry equipment spending. Electronics and packaging was guided to roughly $385 million despite normal flex seasonality. Hitting that would support the case that AI-related advanced circuit boards, now 15% to 20% of chemistry revenue, can offset the usual summer lull. Specialty industrial, guided to $335 million, is the quieter test of whether data center testing and defense demand are durable.
Margins are where the story could get complicated. Gross margin was guided down to about 47% from 47.6%. Part of the drop reflects a one-time tariff refund in the prior quarter, but the rest comes from a mix shift toward lower-margin chemistry equipment and from ramp investment costs of 50 to 80 basis points per quarter. Management called this a good problem: volume rising faster than margin dilution, with operating margin still expected to climb to 26.3%. If gross margin lands at or above 47% and operating leverage holds, the argument stands. If it slips noticeably below that level, a market already this skittish may read it as a sign that growth is getting more expensive to deliver.
The balance sheet is a secondary but real checkpoint. Net leverage fell to 3.0x from 3.9x a year earlier, but debt paydown has held at about $100 million a quarter as capital spending and working capital rise to fund projects in Guangzhou, Malaysia and Germany. Any additional prepayment in the second half, as management has signaled, would show the ramp is funding itself.
Sentiment has turned mildly bullish from slightly bearish heading into last quarter, even as the stock trades well below its 200-day moving average of about $277. At $202, it sits just above the $192 low of its post-earnings range. That pairing suggests buyers see value but have not yet seen proof. The deciding question is whether fourth-quarter guidance shows the semiconductor ramp still accelerating. A guide that steps up again would challenge the market's skepticism head on. A flat or hedged outlook would suggest the selloff anticipated something management had not yet acknowledged.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-19 | |
| Oct-19 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-05 | |
| Oct-02 | |
| Oct-02 | |
| Sep-30 | |
| Sep-29 | |
| Sep-14 | |
| Aug-17 |
