MKS Blows Past Guidance As Semiconductor Growth Hits 54%, But The Stock Is Still Trading Like The Cycle Is Ending
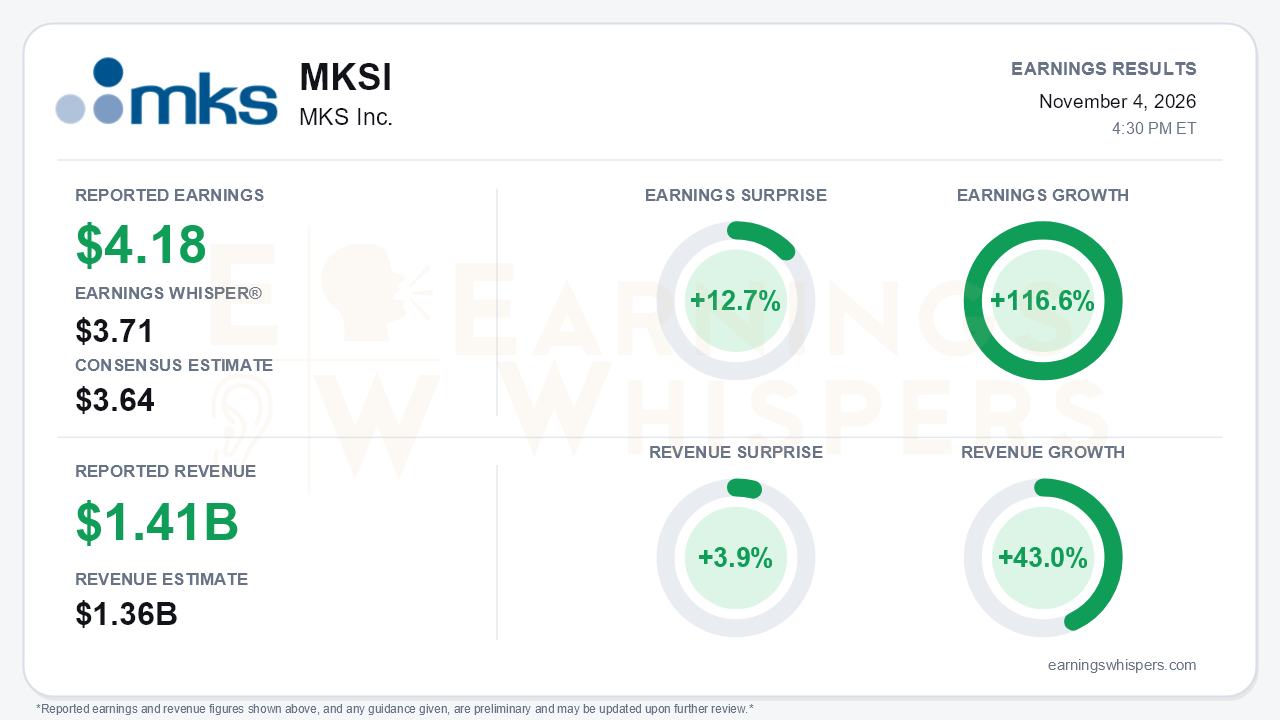
MKS Inc. delivered one of the cleanest beats of the semiconductor-equipment supply chain this season. Third-quarter non-GAAP earnings of $4.18 per share topped the $3.64 consensus by 12.7% and cleared the $3.71 Earnings Whisper number. Earnings grew 116.6% year over year on revenue of $1.413 billion, which was 43.0% higher and 3.9% above the $1.36 billion consensus. Every end market landed at or above the high end of guidance. The fourth-quarter outlook of $1.49 billion, plus or minus $40 million, sits above Street expectations. The central tension is not in the numbers. It is the gap between a business that is clearly accelerating and a stock that has fallen 33% since the opening after the August report.
The quality of the quarter holds up well under scrutiny. GAAP earnings rose to $3.26 per diluted share from $1.10 a year ago. Non-GAAP operating margin expanded to 27.8%, up from 25.6% in the second quarter and 20.8% a year earlier. Operating expenses grew far more slowly than revenue, so the operating leverage is genuine rather than accounting-driven. Free cash flow reached $243 million, up from $147 million a year earlier, even as receivables and inventory absorbed cash to support the ramp. Two caveats deserve attention:
- Gross margin of 47.7% included roughly 30 basis points from a non-recurring IEEPA tariff refund.
- The $5.00 fourth-quarter non-GAAP EPS guide benefits from a full-year tax rate cut to about 16%. GAAP guidance assumes a tax provision of just $16 million, versus $51 million in the third quarter.
The call reinforced that the acceleration is broad. Semiconductor revenue grew 54%, up from 28% in the second quarter and 13% in the first, and is guided to $700 million in the fourth quarter. Management now expects roughly 40% semiconductor growth in 2026 against wafer fab equipment (WFE) spending growth in the mid-30s. Electronics & Packaging rose 43%, and chemistry growth excluding FX and palladium accelerated for a third straight quarter, to 26%. The language around demand also hardened:
- Chemistry equipment is sold out through 2027, with bookings now extending into 2028.
- Rigid PCB laser drilling moved from "increased order activity" to "considerable new orders," with explicit share gains as competitors face constraints.
- New wins included dissolved gas solutions at a major foundry and a pulsed DC conductor-etch position that displaced an incumbent.
Most telling, MKS raised its capacity planning to support roughly $300 billion of WFE in 2028. That figure was $200-250 billion last quarter and $170-180 billion in the first quarter. Management's tone has shifted from deleveraging first to pricing leverage and share gains.
The risks are real but mostly about pace rather than direction. Gross margin is plateauing in the 47%-48% range. Lower-margin equipment mix and capacity-expansion costs are expected to weigh into 2027, and the path to higher gross margin has been deferred to the December 14 investor day. Specialty Industrial is guided flat sequentially. Flex PCB drilling faces seasonal and smartphone softness, and management flagged pockets of input-cost inflation. More structurally, supply constraints elsewhere in the chain could cap customer tool shipments regardless of MKS's own capacity. Management also acknowledged overbuild risk if AI data-center economics deteriorate.
The balance sheet has transformed. Net leverage fell to 2.4x from 3.7x at the end of 2025, enough to fund a new $500 million buyback alongside a $100 million term-loan prepayment in November. The $1.4 billion of convertible notes, however, are now classified as short-term debt because the conversion condition was met. The pending Ophir Optics sale to TTM Technologies is excluded from guidance.
The market setup is more complicated than the surprise implies. Shares closed at $194.95 before the release, nearly 30% below the 200-day moving average of $277.68. Investor sentiment swung meaningfully, moving from essentially neutral (-0.01) to moderately positive (+0.26). The Earnings Whispers trend readings are split: sequential growth and momentum are positive, while price and AVWAP trends remain negative. That split mirrors the disconnect between fundamentals and the tape.
The bottom line is that MKS reported accelerating revenue, expanding operating margins, rapid deleveraging, and a guide that implies 44% growth next quarter. Its order visibility now reaches into 2028. Bears retain legitimate ammunition in the plateauing gross margin, a tax-aided fourth-quarter EPS guide, and the cyclical risk embedded in tripling capacity assumptions in two quarters. The stock's steep slide below its long-term average suggests investors are pricing peak-cycle fears that this report did little to validate.
Read our earnings preview for MKS Inc.: https://www.earningswhispers.com/article/MKSI/21876
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-27 | |
| Oct-19 | |
| Oct-19 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-05 | |
| Oct-02 |
