Magnolia's First Post-Wildfire Report Tests Whether Scale Can Outrun Dilution And Debt
Magnolia Oil & Gas spent years as the tidy, low-leverage operator in South Texas. Its third-quarter report, due after the close on November 4, is the first since it reshaped that identity with the roughly $4.06 billion Wildfire Energy acquisition. The deal was expected to close late in the quarter. That timing means this release will combine a mostly standalone operating quarter with the first look at a much larger share count and balance sheet. The central question is whether management's promise of immediate per-share accretion holds up once the bigger denominator arrives.
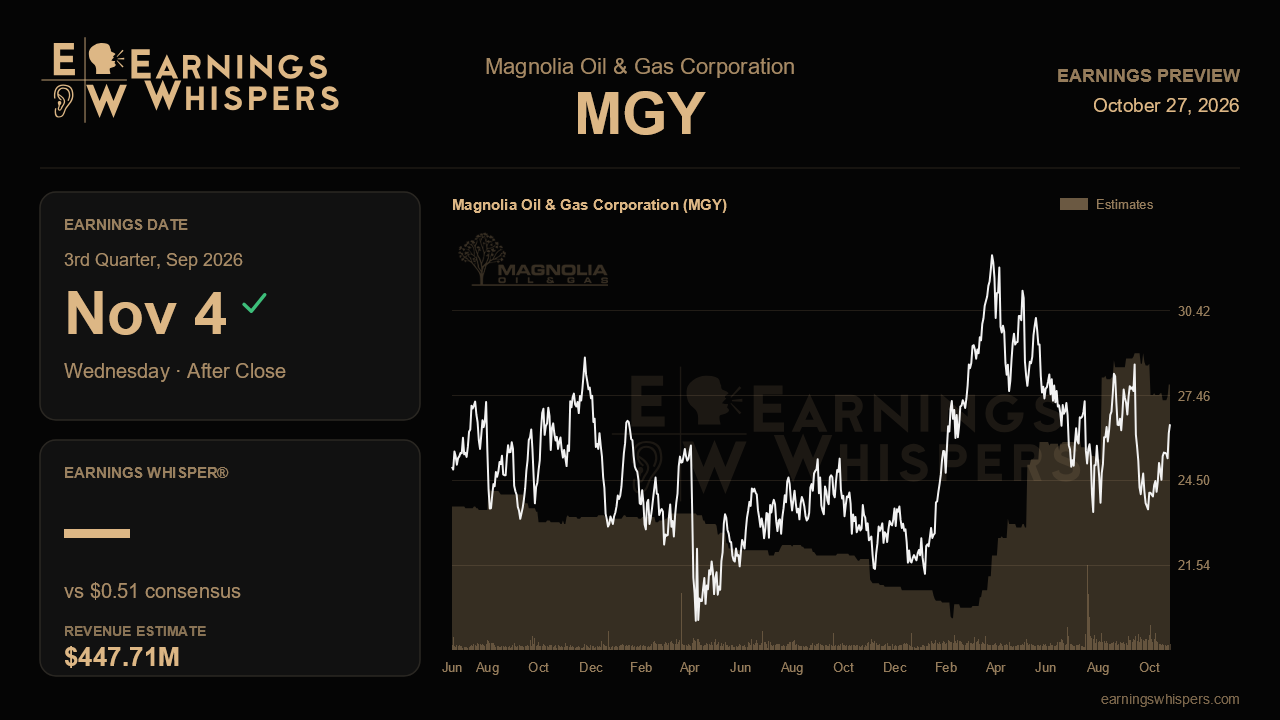
Wall Street expects earnings of $0.51 per share on revenue of $447.7 million. Against the year-ago quarter, that is strong growth, with EPS up about 24% and revenue up nearly 38%. The sequential picture is less flattering. Last quarter Magnolia earned $0.99 on $478.8 million in revenue, so consensus implies EPS nearly halving while revenue slips only modestly. That gap points to two things. Analysts are modeling softer realizations than the second quarter's unusually rich pricing, and they are absorbing dilution from the 53.3 million shares issued to fund the deal. Diluted shares are heading toward about 269 million from roughly 185 million. Accretion claims will be judged on a per-share basis, so the share count matters as much as the barrels.
Operationally, the bar is clear. Management guided standalone third-quarter production roughly flat at about 106 MBoe/d, after a record 106.1 MBoe/d in the second quarter. It also raised full-year standalone growth to 6% from the 5% it had reiterated for several quarters. Holding near that level and reaffirming 6% would confirm the raise was not a one-quarter stretch. A miss on volumes would be more worrying. It would suggest the legacy Giddings and Karnes engine is losing steam just as attention shifts to integration. The second-quarter results also set efficiency benchmarks: a 51% pre-tax operating margin, $235 million of free cash flow and a 34% reinvestment rate, the lowest since 2022. Much of that margin came from a roughly 39% year-over-year jump in revenue per BOE. Some margin giveback would be normal. Discipline on lease operating costs and capital spending would show that the efficiency gains are structural.
The Wildfire details may matter more than the quarter itself. Investors will want confirmation of the closing and early pro forma guidance for the fourth quarter and 2027. They will also want specifics on how the added 53 MBoe/d, about 37,000 barrels a day of it oil, lifts the company's oil mix toward 50%. Commentary on the sand mine synergies, the drilling plan for the lightly tested Austin Chalk acreage, and progress toward net debt below 1x EBITDA by year-end 2027 would strengthen the expansion story. Vague integration timelines or a higher reinvestment rate to develop the new acreage would challenge it.
The market has given Magnolia some benefit of the doubt. Shares are up about 4.8% since the last report while the S&P 500 slipped 0.6%. Sentiment has edged from slightly bearish to modestly bullish, a small shift rather than enthusiasm. At $26.46, the stock sits mid-range between its post-earnings low of $23.15 and high of $28.83, just under its 200-day moving average. It has not yet broken out decisively in either direction.
Ultimately, this report hinges on whether Magnolia can show that the enlarged company generates enough free cash flow per share to justify the dilution and the new debt. Steady standalone execution and a credible deleveraging path would keep the improving narrative intact. Signs that Wildfire is costlier or slower to integrate than advertised would make the old balance sheet look like the better asset.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-01 | |
| Sep-10 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-21 | |
| Jul-21 | |
| Jul-21 | |
| Jul-21 | |
| Jul-20 | |
| Jul-20 | |
| Jul-08 |
