Magnolia Beats Handily In First WildFire Quarter, But Dilution, Thinner Margins And A Heavier Balance Sheet Complicate The Story
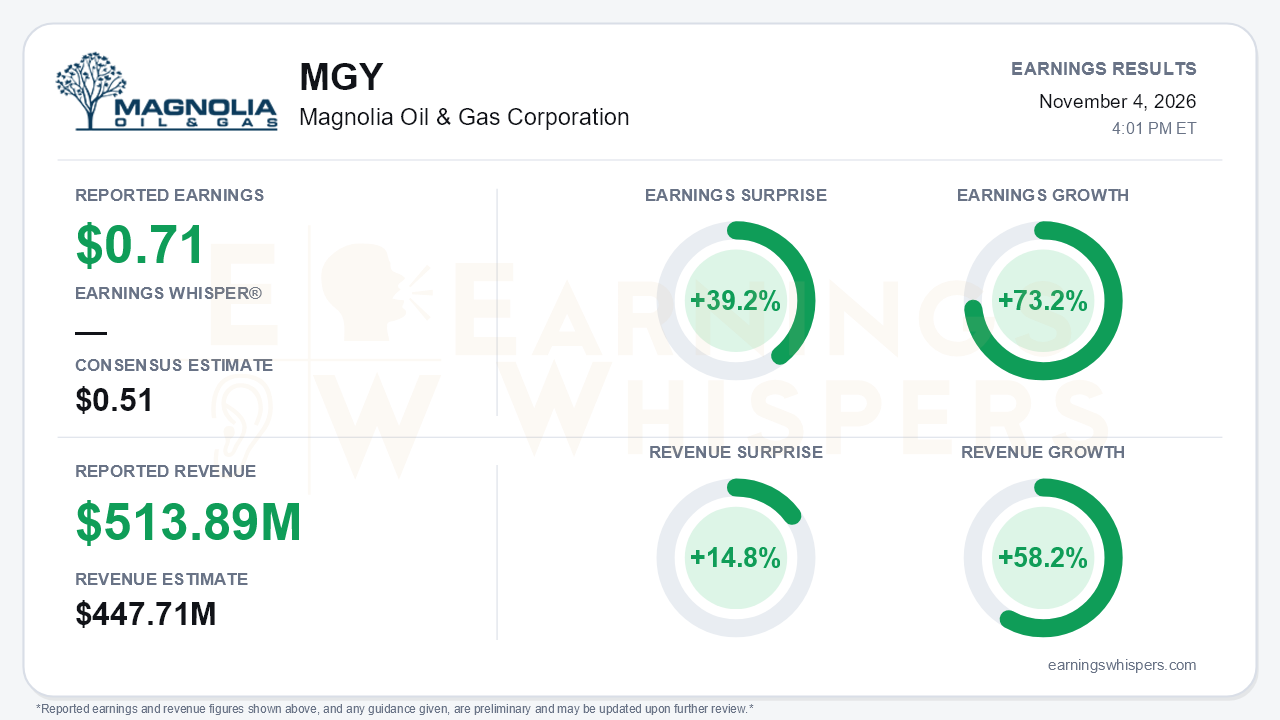
Magnolia Oil & Gas delivered a clean headline beat in its first quarter as a larger company. Adjusted earnings of $0.71 per share topped the $0.51 consensus by 39.2% and grew 73.2% year over year. Revenue of $513.89 million beat expectations by 14.8% and rose 58.2%. The central tension is that the beat comes from a fundamentally different company. The WildFire Energy acquisition closed September 10, adding scale, oil weighting and inventory. It also brought share dilution, debt and hedges, all of which weigh on the per-share and return metrics that historically set Magnolia apart.
The quality of the beat deserves scrutiny. Much of the revenue growth came from price rather than volume. Magnolia realized $87.18 per barrel of oil versus $63.55 a year ago, helped by a 102% realization to WTI. Oil revenue climbed 71% while production rose 17% to 117.3 Mboe/d. On a GAAP basis the picture is far less flattering. Diluted EPS fell 13% to $0.35 from $0.40, weighed down by $68.7 million of transaction and integration costs and a $39.9 million unrealized derivative loss. Those items are reasonably treated as non-recurring. Diluted share count, however, rose to 230.6 million from 190.3 million, and that is permanent. Sequentially, the call noted that adjusted EPS dropped from $0.99 in the second quarter.
Beneath the headline, the operating trends split cleanly. Scale metrics improved:
- Production rose from 106.1 Mboe/d in Q2.
- Oil output climbed to 49.1 Mbbl/d from 41.9.
- Adjusted EBITDAX reached $392 million, up from $370 million in Q2 and $253 million in Q1.
Efficiency metrics moved the other way:
- Unit cash costs increased to $12.40/Boe from $11.55.
- Pre-tax margin narrowed to 43% from 51% in Q2.
- Return on capital employed fell to 20% from 39%.
- Adjusted free cash flow slipped to $224 million from $235 million, while the reinvestment rate rose to 38% from 34%.
The release frames the 43% pre-tax margin favorably against 31% a year ago. Both comparisons are accurate. The year-over-year gain mostly reflects higher oil prices, while the sequential decline reflects the cost of integrating a larger, more levered asset base during a partial quarter.
The forward story is where management made its strongest case. Fourth-quarter guidance calls for 159–161 Mboe/d with oil at 49–50% of volumes, a step-change from the roughly 42% oil mix in Q3. Synergy capture is running ahead of plan. Management expects at least one-third of a more than $100 million run-rate by year-end and three-quarters by mid-2027, with D&C savings of at least $1 million per well. Other supports include:
- an owned sand mine expected to cut sand costs by about one-third;
- early Austin Chalk results on WildFire acreage that management says point to more inventory than the acquisition baseline, with the 2027 program weighted roughly 65% to the Chalk.
For 2027, Magnolia introduced D&C spending of $900–950 million against roughly $800 million of maintenance capital, supporting 4–5% organic growth. The company also cut leverage below 1.0x net debt to EBITDAX more than a year early and raised its buyback authorization to 22.6 million shares.
Bears still have legitimate ammunition. Net debt stands near $1.9 billion, compared with $133 million at the end of 2025, and the company carries $435 million on its revolver. Management assumes mid-single-digit service inflation for 2027. Magnolia has also abandoned its long-held unhedged stance. Costless collars with $70–75 floors cap upside at roughly $80–91, and inherited WildFire swaps sit in the mid-$60s. Those swaps contributed to about $20 million of cash settlements this quarter and will dilute leverage to elevated oil prices. Integration across a 1.25 million net acre footprint adds execution risk.
The market has not yet rewarded the deal. Shares closed at $23.37, down 7.4% since the open after the August report and 13.7% below the 200-day moving average of $27.09. The call acknowledged that the stock trades below pre-deal levels, with a possible overhang once lockups expire on shares issued to WildFire sellers. Investor sentiment was essentially unchanged and hovering just below neutral, slipping marginally to -0.0054 from -0.0015. Earnings Whispers trend readings are mixed: price trend negative, momentum and AVWAP positive.
The bottom line is that Magnolia's beat was real but flattered by oil prices and non-GAAP adjustments, and the quarter traded per-share efficiency for scale. The fourth quarter, as the first full combined period, now carries the burden of proof. Investors need to see synergies, Austin Chalk upside and debt reduction restore margins and returns faster than dilution, hedging and cost inflation erode them.
Read our earnings preview for Magnolia Oil & Gas Corporation: https://www.earningswhispers.com/article/MGY/21875
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-27 | |
| Oct-01 | |
| Sep-10 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-21 | |
| Jul-21 | |
| Jul-21 |
