MetLife Needs A Private Equity Rebound To Clear A Steeper Third-Quarter Bar
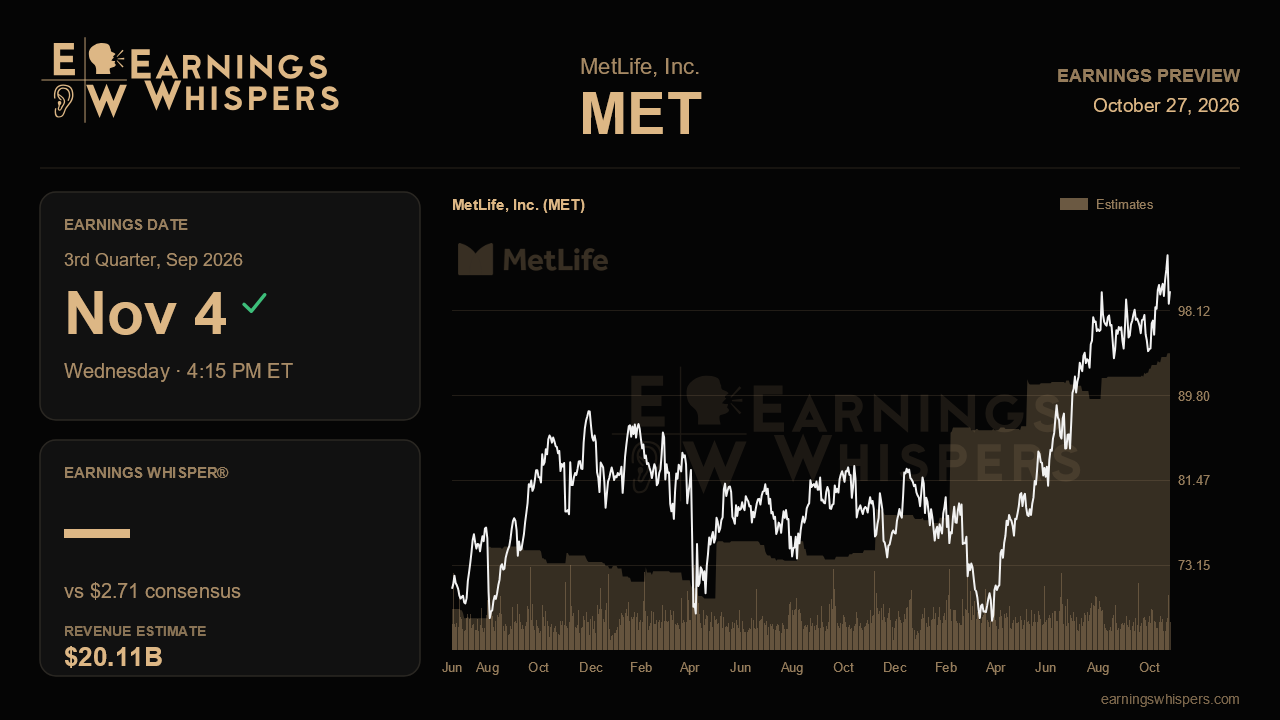
MetLife heads into its third-quarter report with a quirk in the numbers. The Street expects a sizable sequential jump in earnings at the very moment management has warned that one of its best tailwinds, unusually favorable group life mortality, is fading. Closing that gap depends largely on something the company does not control: whether private equity and venture capital returns bounce back as management suggested they would.
Consensus calls for adjusted EPS of $2.71 on revenue of about $20.11 billion, both up 15.8% from a year ago. That is solid growth, but it continues a gradual deceleration, following adjusted EPS gains of 23% in the first quarter and 20% in the second. The more telling comparison is sequential. Analysts are looking for roughly 11% more earnings than the $2.43 MetLife posted last quarter, even though group benefits, the standout segment that grew adjusted earnings 25% to $503 million, is expected to give back some of its edge. The group life mortality ratio came in at 79%, comfortably better than the 83% to 88% target, and management signaled that roughly two points of favorability should normalize in the back half based on July trends. Last quarter's 23% effective tax rate, below the 24% to 26% guidance, is also unlikely to repeat.
So where does the extra earnings power come from? The clearest answer is variable investment income. Private equity returned just 0.8% in the second quarter, versus 2.9% in the first, dragging the retirement and income solutions spread to 97 basis points, below the 100 to 120 basis point guidance range. Management pointed to elevated IPO activity as reason to expect stronger private equity and venture returns in the third quarter. A spread back inside the guided range would validate that call and do much of the heavy lifting for consensus. Another sub-100 print would suggest the second quarter was not a one-off and make the Street's number look stretched. Core spread excluding variable income rose to 100 basis points last quarter, so steadiness there matters too.
Several secondary threads will help investors judge whether the improving tone was earned. MetLife Investment Management guided toward the low end of its $240 million to $280 million full-year earnings range, with Pinebridge integration benefits expected to build in the second half; a visible step-up is needed to make that math work. Pension risk transfer was quiet through the first half after a record $14 billion in 2025, and UK-funded reinsurance, now over $1 billion year to date, has been the offset. Asia, which grew earnings 25% in constant currency on 17% sales growth, needs to keep compounding, while a Mexico VAT change is a modest drag on Latin America. The direct expense ratio, which ticked up to 12.1% on integration costs, should hold at or below its full-year target. Buybacks under the new $3 billion authorization will also quietly support per-share results.
Expectations have warmed. Sentiment has swung from decidedly bearish ahead of last quarter to slightly bullish now, and the stock has gained 1.5% since the last report while the S&P 500 slipped 0.6%. At about $100, shares sit well above the 200-day moving average near $85 and above last quarter's high of $97.80, though still a few percent shy of the post-earnings peak of $103.65. The market has given MetLife some credit, not a free pass.
The central question is whether investment income and asset management growth can replace normalizing mortality gains. If private equity returns rebound and the spread recovers into its range while group margins slip only modestly, the multi-quarter improvement story stays intact. If both mortality and investment income disappoint at once, the sequential leap embedded in consensus will be hard to reach.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-25 | |
| Oct-23 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Sep-29 | |
| Sep-28 | |
| Sep-23 | |
| Sep-22 | |
| Sep-16 |
