Nuvation Bio's First-Line Ibtrozi Bet Faces A Skeptical Market After A 25% Slide
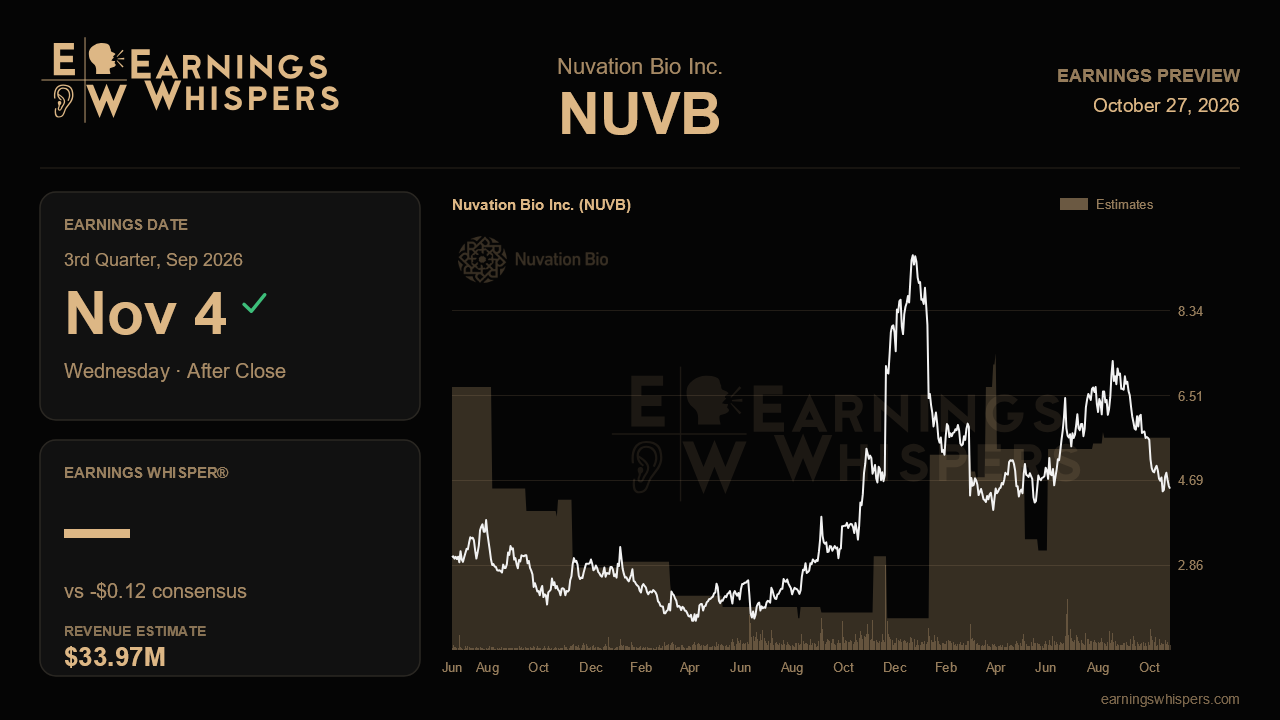
Nuvation Bio heads into its third-quarter report with a story that management insists is getting better and a stock that says the market is not convinced. Last quarter the company argued that a drop in new patient starts for its ROS1 lung cancer drug Ibtrozi was a sign of health rather than weakness. In its view, the pool of previously treated patients was emptying out while long-duration first-line patients piled up. The November 4 release, due after the close, is the first real chance to test whether that revenue stacking thesis holds up now that a competitor is on the market.
The Street is looking for total revenue of about $34.0 million, up roughly 159% from $13.1 million a year ago. The per-share loss is expected to narrow to 12 cents from 16 cents. The year-over-year growth is striking, but the sequential bar is modest. Consensus implies only about 7% growth over the prior quarter's $31.7 million. Ibtrozi alone grew 25% sequentially last quarter to $23.2 million, its fourth straight sizable step up. Management has not issued formal guidance. It did, however, describe full-year Street forecasts near $115 million as comfortably achievable. Given how much of that total has to come in the back half, a quarter that merely matches consensus could look less comfortable than the company implied.
The heart of the report is patient flow. New starts held near 204 a quarter for three quarters before falling to roughly 160. Meanwhile the first-line share of starts surged to about 85%, and first-line starts rose about 30% in a single quarter. Management argued that first-line patients matter far more economically because of a 50-month median duration of response in treatment-naive patients, which makes the drug behave more like therapy for a chronic disease. Validation would look like total starts stabilizing around the new base, first-line additions continuing to grow, and product revenue rising faster than the starts count. Another step down in starts, or a stall in first-line momentum, would suggest the later-line drain is not the whole explanation.
Competition is the new variable. GSK's rival ROS1 inhibitor was approved ahead of schedule, though only for later-line use, and it is priced about 8% above Ibtrozi. Nuvation has leaned on the competitor's label, which includes CNS warnings and a heavier toxicity profile, to argue its own franchise is protected. The cleanest evidence would be steady gross-to-net discounting near the 30% level management described, alongside no visible erosion in Ibtrozi's position as the most prescribed ROS1 drug. Commentary on testing rates in community oncology is also worth a close listen. Under-testing and habitual use of immunotherapy or chemotherapy remain the main brakes on expanding the first-line market, which has grown about 20% since launch.
Beyond Ibtrozi, the company has more financial room than most commercial-stage biotechs. A roughly $279 million low-coupon convertible replaced expensive debt and lifted cash to $661 million, explicitly to fund business development. Any deal activity, along with updates on the expanded safucitinib glioma program, could shape the longer-term story. Still, this quarter will be judged mainly on the launch curve.
Sentiment has soured noticeably. Bearish readings have climbed to about 38% from 15% ahead of the last report. Shares have fallen nearly 26% since then while the S&P 500 was roughly flat. At $4.51, the stock sits well below its 200-day average of $5.46 and just above its post-earnings low of $4.35, far from the $7.58 high. That pessimism lowers the bar in one sense, but it also signals the market wants proof rather than reassurance. If Ibtrozi revenue keeps compounding at a healthy clip despite fewer total starts, the mix-shift argument stays intact. If revenue growth slows toward the patient-start decline, the bears will have their case.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 46 min | |
| Oct-21 | |
| Sep-17 | |
| Sep-15 | |
| Sep-02 | |
| Aug-20 | |
| Aug-06 | |
| Aug-04 | |
| Jul-22 | |
| Jul-20 | |
| Jul-20 | |
| Jul-06 | |
| Jul-01 | |
| Jun-29 | |
| Jun-25 |
