NETGEAR's Enterprise Margin Story Faces A Memory-Cost And Air-Freight Squeeze In Q3
NETGEAR heads into its third-quarter report with a split personality. Its enterprise business has been compounding profitability at a pace the company has not managed in years, and management used its last call to signal that full-year revenue and operating margin estimates should move higher. Yet the quarter it is about to report was always meant to be the soft spot of the year, weighed down by memory costs, an expensive logistics fix and a deliberate reset in Asia-Pacific. The question on November 4 is whether that dip proves to be the contained, temporary hit management described, or something messier.
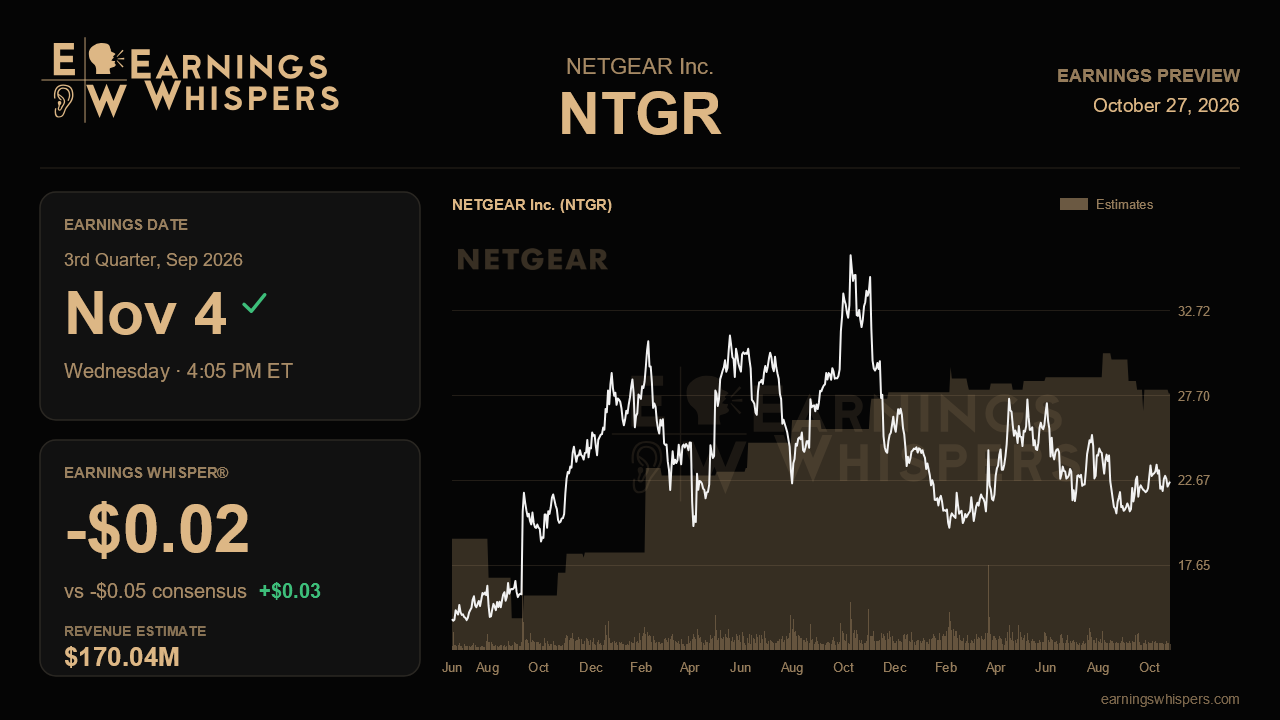
The Street expects a non-GAAP loss of 5 cents a share on revenue of about $170.0 million, which would be a decline of roughly 8% from the $184.6 million posted a year earlier. That figure sits squarely at the midpoint of management's $165 million to $175 million guidance range, so analysts are taking the company at its word rather than leaning in either direction. The whisper number of a 2-cent loss is slightly better than consensus, a hint that some believe NETGEAR can outrun its guidance on costs, though the gap is small enough that it mostly reflects modest confidence in execution rather than a high bar. For context, the company guided operating margin to a range of negative 3% to breakeven, a clear step down from the positive 2.4% it delivered in the second quarter.
Enterprise is where the narrative lives or dies. Enterprise gross margin climbed for four straight quarters to a record 54.1%, and the segment now accounts for more than half of revenue and roughly 69% of gross profit. A ProAV manufacturing partner's factory relocation forced costly air freight that management said would pressure third-quarter margins, so some retreat from that record is expected. What matters is the size of the retreat. A modest slip that preserves margins in the low 50s would validate the idea that the improvement is structural; a sharp drop would suggest that recent gains were more fragile than they looked. Revenue growth in the Americas and EMEA, which rose 15% and 9% respectively last quarter, should show whether new catalysts such as the award-winning Align AV platform, the relaunched Insight software and 86 E-Rate school district wins are converting into orders. Annual recurring revenue, which reached $41.6 million, is another useful tell for the software-driven pitch.
The risks are more familiar but still potent. Memory costs were expected to shave about 200 basis points from second-half gross margin, skewed toward this quarter, and management warned the pressure was spreading to other components alongside modest production delays. Consumer gross margin has already slid from 31.4% to 27.3% over two quarters, so another meaningful leg down would raise doubts about how much of the company's mix shift is being offset at the consumer end. Asia-Pacific enterprise sales fell 16% last quarter amid a channel restructuring, with sequential growth not expected until the fourth quarter, so any sign that timeline is slipping would matter. Service provider revenue, guided to around $22 million, remains in structural decline.
The market has not given NETGEAR much credit for its upbeat tone. Shares are down 5.4% since the last report, trailing the S&P 500 by nearly 5 percentage points, and sentiment has turned somewhat more bearish than a quarter ago. At $22.60, the stock sits just below its 200-day moving average and in the middle of its post-earnings range, well beneath the prior quarter's highs near $28.
That skepticism sets up a straightforward test. If NETGEAR lands near its guidance while showing enterprise margins holding up through the air-freight hit and reaffirming its call for roughly 400 basis points of sequential operating margin improvement in the fourth quarter, the case for a raised full year stays intact. If cost pressures bleed further into enterprise or the fourth-quarter rebound looks shakier, the market's doubts will have been justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-20 | |
| Sep-09 | |
| Aug-07 | |
| Aug-06 | |
| Jul-21 | |
| Jun-30 | |
| Jun-15 | |
| Apr-30 | |
| Apr-29 | |
| Apr-20 | |
| Apr-15 | |
| Mar-24 |
