NETGEAR's Margin-Driven Beat Masks A Supply Stumble That Pushes The Enterprise Recovery Into 2027
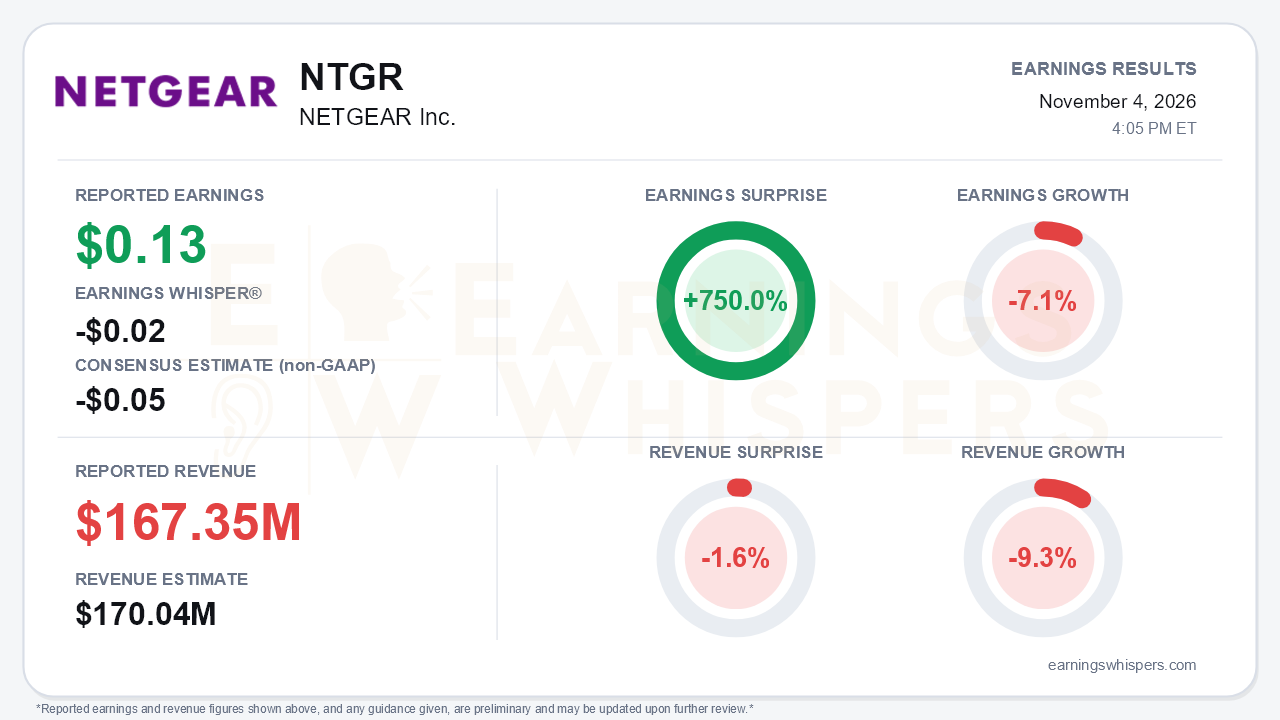
NETGEAR delivered a large earnings beat that says more about cost discipline and mix than about growth. The company reported non-GAAP earnings of $0.13 per share, well ahead of the -$0.05 consensus and the -$0.02 Earnings Whisper, a 750.0% surprise. Revenue of $167.35 million missed consensus by 1.6% and fell 9.3% year over year. Earnings Whispers' normalized comparison shows EPS down 7.1% year over year. The company's own non-GAAP presentation shows $0.13 versus $0.12, which suggests a difference in the prior-year baseline. On either basis, earnings were essentially flat. The central tension is that NETGEAR's profitability model is working while its revenue engine has stalled. Management now says a manufacturing partner's problems will not be resolved until the first quarter of 2027.
The quality of the beat deserves scrutiny. Non-GAAP operating income of $3.3 million produced a 2.0% margin, above the guided range of -3% to 0%. It was the fifth straight profitable quarter on that basis. Enterprise non-GAAP gross margin expanded 220 basis points to 53.2%, and Enterprise now accounts for roughly 70% of non-GAAP gross profit. Below the non-GAAP line, the picture is weaker. The GAAP loss widened to $0.45 per share from $0.17 a year ago, driven partly by $5.6 million of restructuring charges and higher stock-based compensation. Non-GAAP operating income was also slightly lower than both the prior quarter and the prior year. The beat came largely from expectations that were set too low, not from a business that is earning more.
The call marked a clear shift from beat-and-raise to supply-constrained. Enterprise revenue of $90.7 million was flat year over year, a sharp slowdown from 7.7% growth in Q2 and 5.8% in Q1. Consumer revenue fell 18.2% after a 9.4% decline in Q2, and the segment posted a $1.4 million contribution loss. The deceleration is not a demand problem. Enterprise sell-through rose about 6% (Americas +10%, Europe +4%), managed switches grew double digits, and Enterprise backlog more than doubled again to roughly $20 million. The problem is execution. On the Q2 call, management described the ProAV supply issue as a resolved blip. In Q3, the partner missed minimum commitments again following a poorly executed factory transition. The shortfall also spread to consumer routers, costing roughly $4 million of largely perishable demand. Management's tone moved from expressing great confidence to calling the situation "unacceptable."
Guidance reflects that reset. Fourth-quarter revenue of $160 million to $175 million implies no seasonal lift and came in below estimates. Management had earlier signaled sequential growth and a roughly 400-basis-point operating-margin step-up. The non-GAAP operating margin guide of 0% to 3% is better than last quarter's range but falls short of that earlier framing. Gross margin is expected to fall about 150 basis points sequentially on memory and air-freight costs. Service provider revenue is guided to roughly $17 million, down about 28%. Component tightness is broadening from memory to flash, PCBs, and MLCCs. Recurring revenue is also cooling: ARR grew 12% to $42.5 million, down from 15% growth in Q2.
The offsets are real but mostly deferred. A further ~10% price increase on managed switches takes effect in November, and consumer price increases follow in early 2027. The backlog gives NETGEAR a revenue reservoir once production normalizes. Some products are moving to alternative manufacturing partners. On the product side, the Align platform sold out its initial quantities and Insight billings more than doubled. The roughly 8% workforce reduction should yield about $6 million in annualized savings starting in 2027. Bears have legitimate ammunition on the balance sheet: cash and investments fell to $242.1 million from $323 million at the end of 2025. Operating cash flow was -$3.8 million in the quarter, and buybacks continue at $15 million.
Investor sentiment entered the report negative and drifted modestly lower, from -0.21 to -0.25. The change reflects mild erosion rather than capitulation. Shares closed at $21.82 ahead of the release, down 8.7% from the open after the prior report and about 5% below the 200-day moving average. The stock has never recovered its $24.50 post-report high from August and sits roughly 8% above its late-August low of $20.22. The market had already discounted part of the slowdown before management confirmed the delay. Earnings Whispers momentum and AVWAP trend readings are positive, but they offer limited comfort against a guide that pushes the recovery out another quarter.
The bottom line is that NETGEAR's transformation into a higher-margin, Enterprise-led company is visible in the margins, sell-through, and backlog. However, the near-term story now depends on a supplier that has already missed one recovery deadline. Until Enterprise revenue catches up with demand, the earnings beat is less important than whether the Q1 2027 normalization target holds.
Read our earnings preview for NETGEAR Inc.: https://www.earningswhispers.com/article/NTGR/21889
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-20 | |
| Sep-09 | |
| Aug-07 | |
| Aug-06 | |
| Jul-21 | |
| Jun-30 | |
| Jun-15 | |
| Apr-30 | |
| Apr-29 | |
| Apr-20 |
