PacBio's SPARCnext Transition Faces Its First Real Test After Three Straight Guidance Cuts
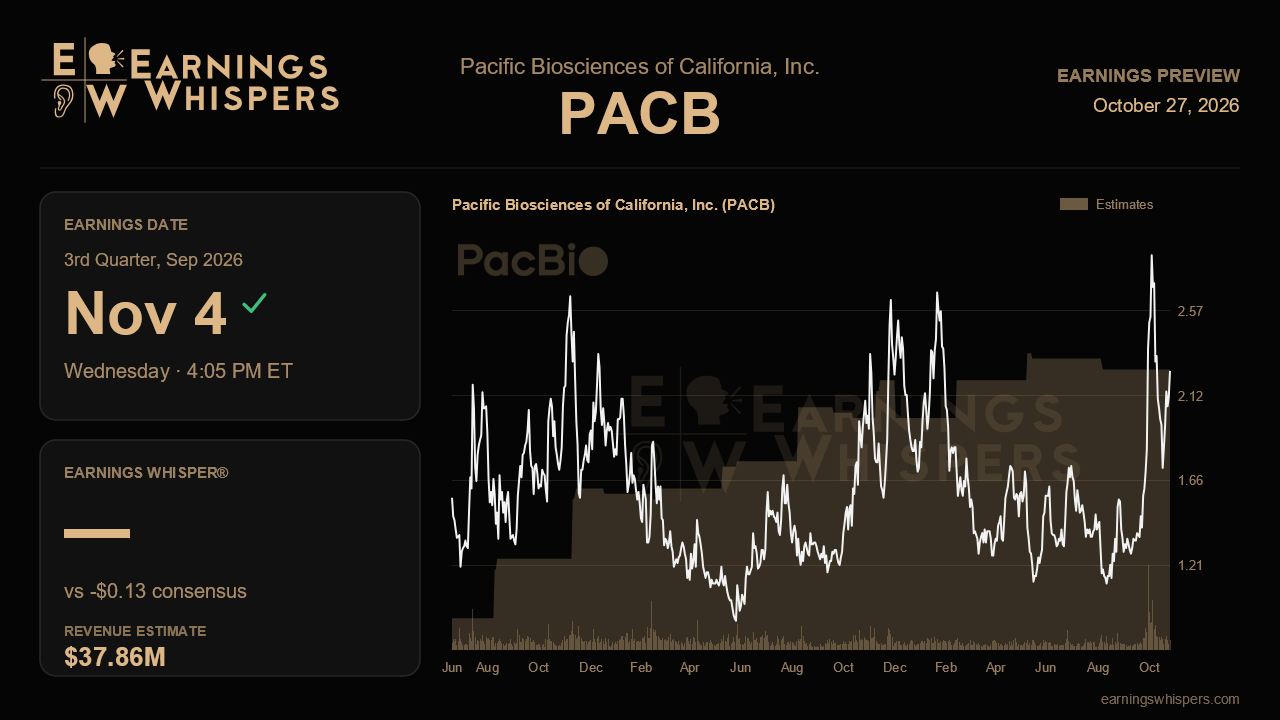
Pacific Biosciences heads into its third-quarter report with a stock that has rallied roughly 73% since its last update, even though that update was among the most sobering in years. Management cut its revenue outlook for the third time in 2026, lowered its gross margin target, pushed cash flow breakeven out to 2028 and named Mark Van Oene chief executive after Christian Henry stepped down. The rally suggests the market has decided the worst is behind the company. The November 4 release, due after the close, is the first chance to check whether that conclusion holds up.
Wall Street expects a loss of $0.13 per share on revenue of about $37.9 million. That would be a 1.5% revenue decline from the year-ago quarter and a slightly wider loss than the $0.12 reported then. Revenue would also slip from the $39.0 million posted in the second quarter, so the Street is effectively modeling a flat-to-down quarter rather than the start of a recovery. Full-year guidance now stands at $155 million to $165 million, down from an original range of $165 million to $180 million. A quarter near $38 million keeps the company on track for the middle of that range, though not with much room to spare. After three successive reductions, simply holding the range would be meaningful. A fourth cut would do real damage to the credibility of the new leadership team.
The central operating question is consumables. Revio pull-through fell to about $202,000 per system in the second quarter from $229,000 in the first, and management reset the full-year expectation to $200,000 to $225,000. The company blamed much of the weakness on customers working down older SPARC inventory and validating the multi-use workflow under SPARCnext, which also carries a 30% price cut to $345 per genome. The bullish argument is that cheaper genomes will drive enough extra volume to more than make up for the lower price. This quarter should show whether that is starting to happen. Pull-through holding at or above the second-quarter level would suggest the inventory burn-down is easing. Another step down would point to price cuts outrunning demand. Management said more than a third of the install base had opted into the enabling software by June, with a majority expected by year-end, so updates on adoption pace will matter.
Margins are the second test. Gross margin was 36% in the second quarter against 42% a year earlier, pressured by compute and memory cost inflation and roughly $2.5 million of costs tied to moving Vega manufacturing in-house. The new 35% to 37% full-year target leaves little cushion if component costs keep climbing. On the expense side, the opex guide was trimmed to $215 million to $220 million, and the 40-person restructuring is meant to produce $30 million to $40 million in 2027 savings. Cash is the scorecard here. The company ended the second quarter with $236.9 million and expects $175 million to $185 million by year-end.
There are pockets of genuine strength to monitor. EMEA revenue jumped 52%, clinical consumable shipments rose 67%, and Revio placements climbed to 20 units. A new population-scale customer was slated to begin sequencing in the third quarter, and SPARCnext reached Vega in August. On the other side, Vega placements have sagged on U.S. academic funding pressure, and APAC revenue fell 45% as a population program ended and China recovered only slowly.
Sentiment has soured even as the shares surged, with bearish readings rising to 37.8% from 14.6% a quarter ago. The stock trades at $2.25, comfortably above its 200-day average of $1.60 but well below the post-report peak of $3.44, which suggests some of the early enthusiasm has already faded. The verdict will likely come down to pull-through. If SPARCnext volumes begin offsetting the price cut while margins and full-year guidance hold, the recovery story stays intact. If consumables slip again, the rally will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-19 | |
| Oct-14 | |
| Oct-06 | |
| Oct-06 | |
| Oct-01 | |
| Sep-03 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-28 | |
| Jul-15 | |
| Jun-15 |
