PacBio Beats On Sequential Rebound And Deep Cost Cuts, But Another Guidance Trim And Margin Squeeze Keep The Inflection Story Unproven
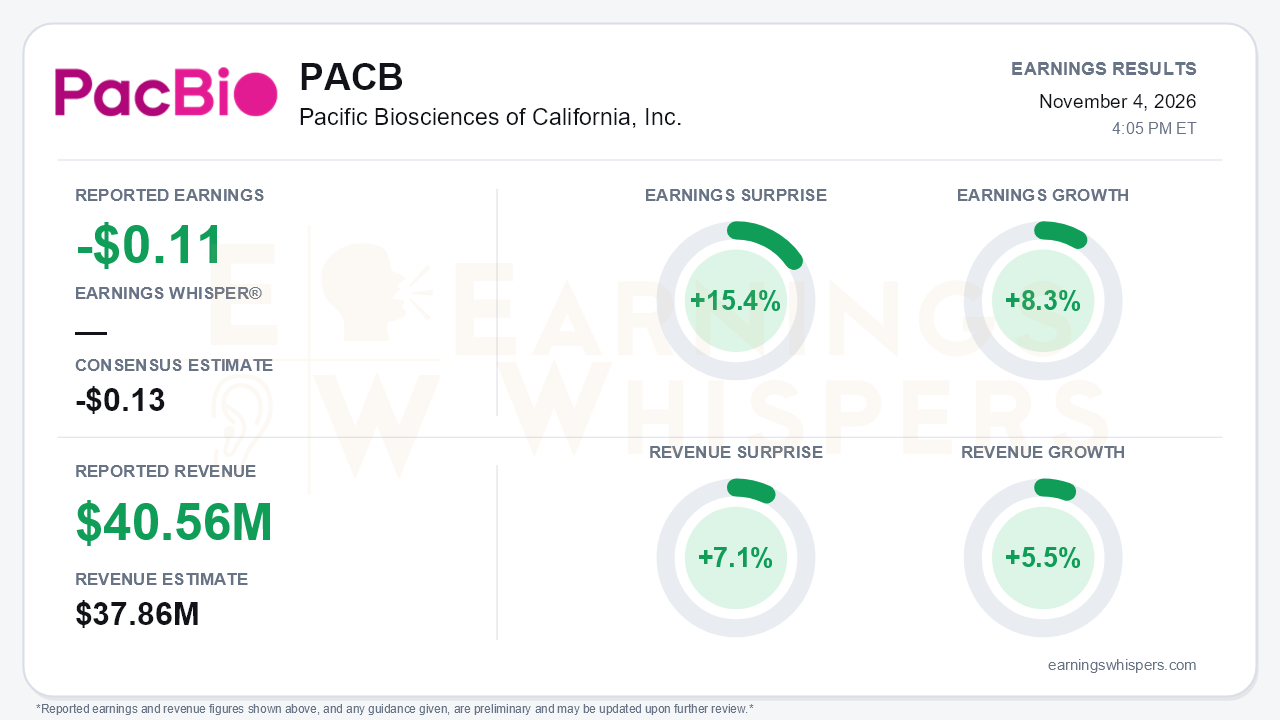
PacBio delivered its cleanest quarter in a year, posting a non-GAAP loss of $0.11 per share against a consensus estimate of a $0.13 loss. That was a 15.4% earnings surprise, and the loss improved 8.3% from a year ago. Revenue of $40.56 million beat the $37.86 million consensus by 7.1% and grew 5.5% year over year, a return to growth after a flat second quarter. Sequential progress was steady, with revenue rising from $37.2 million in Q1 to $39.0 million in Q2 and now $40.6 million. Yet the company again trimmed the top of its full-year revenue range, now $155 million to $160 million versus $155 million to $165 million previously. That is the central tension: operating momentum is visibly improving, while the annual outlook keeps getting smaller.
The quality of the beat deserves scrutiny. The bottom-line improvement came almost entirely from cost reduction, not from operating leverage on the gross profit line. Non-GAAP gross margin fell to 36% from 42% a year ago, which management attributed to higher memory costs and Vega manufacturing transition costs. Non-GAAP gross profit actually declined to $14.6 million from $16.2 million. The offset was opex discipline. Non-GAAP operating expenses dropped to $47.0 million from $53.9 million a year earlier and $56.1 million in Q2, and headcount fell to 445 from 492. On a GAAP basis, the net loss was essentially flat at $37.8 million, including roughly $3 million in restructuring charges. Revenue mix also matters. Instrument revenue rose to $13.2 million from $11.3 million, while consumables slipped to $20.8 million from $21.3 million a year ago. Annualized Revio pull-through was about $204,000, down from roughly $236,000.
Beneath the year-over-year comparisons, the call made a credible case that the business turned a corner sequentially:
- **Consumables and pull-through:** Consumables rose from $20.1 million in Q2, and pull-through edged up from about $202,000.
- **SPRQ-Nx adoption:** More than half of Revio consumables revenue is now tied to the lower-cost SPRQ-Nx chemistry. Two-thirds of the installed base has opted into the software, up from just over one-third in June. This shift had been the main drag on pull-through, and management now guides it back to $225,000 to $250,000 in 2027.
- **Placements:** Revio placements rose to 15 from 13, plus 10 additional units for Berry Genomics. Vega placements jumped to 35 from 26 in Q2 following the late-August SPRQ-Nx launch on Vega, with more than 90% going to new customers.
- **Clinical:** Clinical consumables are growing more than 20% and now exceed 20% of the business.
Management's tone shifted noticeably, describing the period as the start of an inflection. It backed that up with a cluster of deals: GeneDx adding long-read whole-genome sequencing for rare disease, Berry Genomics' China birth-defects program with a path to 40 hospitals, Sampled's VA Million Veteran Program contract, and AI-data collaborations with Verily and TychoBio. Bears still have legitimate ammunition:
- **Regional weakness:** Americas instrument revenue fell about 24% on NIH and academic funding pressure, and APAC was down 13% year over year despite a sequential rebound.
- **Competitive losses:** The first 200,000 samples of Singapore's PRECISE program went to Illumina and Ultima.
- **Pricing pressure:** Strategic pricing on large programs ahead of the late-2027 high-throughput launch could pressure ASPs.
- **CFO departure:** Jim Gibson has left, adding transition risk.
The balance sheet frames everything. Cash fell to $199.4 million after roughly $37 million of Q3 burn. The reaffirmed year-end target of $175 million to $185 million depends on a sharp Q4 burn reduction and favorable working-capital timing. Against that, PacBio carries about $643 million of convertible notes, including maturities of $200 million in 2029 and $400 million in 2030. Stockholders' equity has turned negative. Lowering non-GAAP opex guidance to $203 million to $207 million, from $215 million to $220 million, and reaffirming 2028 breakeven help, but breakeven has already slipped once.
The market setup is more complicated than the surprise implies. Shares rose 87.7% from the $1.30 open after the August report to $2.44 ahead of this release, sitting about 51% above the 200-day moving average. However, the stock had already retreated 29% from its October 6 high of $3.44, a 52-week high, after rallying from a 52-week low of $1.07 in mid-August. Investor sentiment moved the other way, slipping modestly further into negative territory, from -0.15 to -0.23. Price strength has outrun conviction, and a meaningful portion of the rebound has already been surrendered.
The bottom line is that PacBio produced a genuine beat and its best evidence yet that SPRQ-Nx adoption and clinical demand are stabilizing the business. The beat was built on cost cuts while gross margin contracted and full-year guidance was trimmed again. Until pull-through, margins and cash burn improve together, the inflection management describes remains a forecast rather than a fact.
Read our earnings preview for Pacific Biosciences of California, Inc.: https://www.earningswhispers.com/article/PACB/21904
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-31 | |
| Oct-27 | |
| Oct-27 | |
| Oct-19 | |
| Oct-14 | |
| Oct-06 | |
| Oct-06 | |
| Oct-01 | |
| Sep-03 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 |
