Ormat Must Show Its Raised Outlook Survives A Cooling Storage Boom As Shares Slump
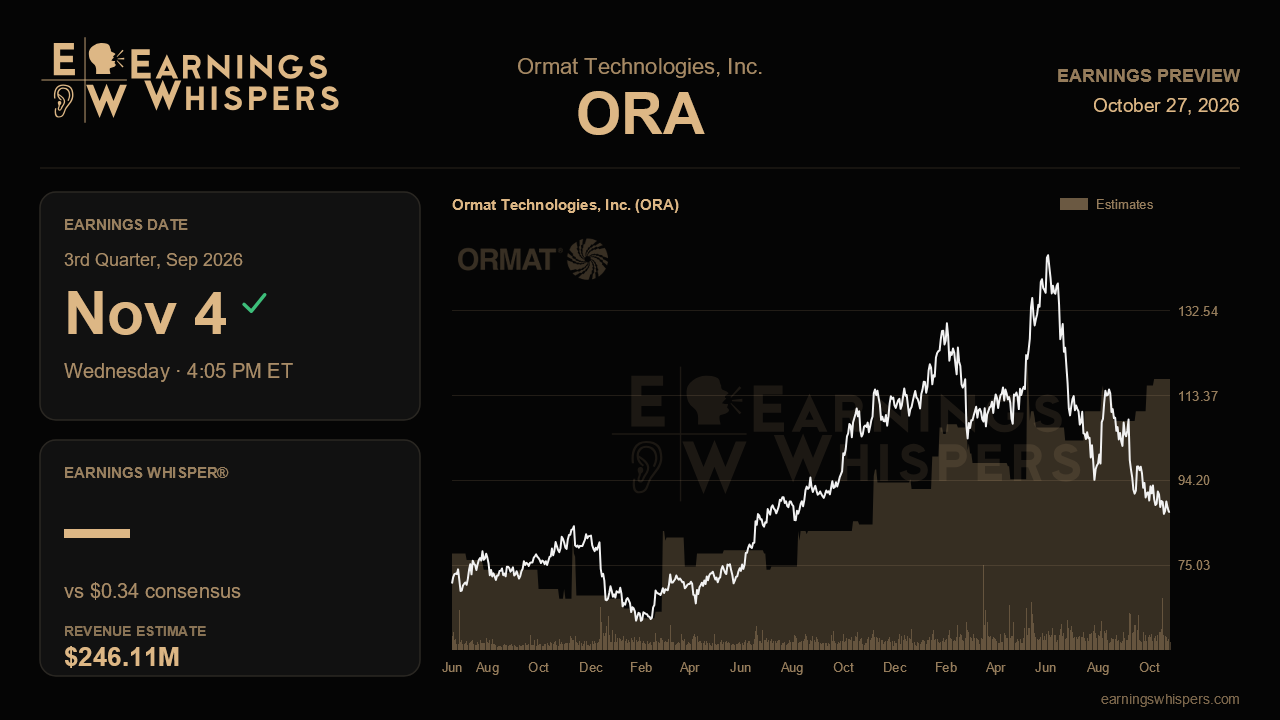
Three months ago Ormat Technologies delivered its first guidance increase of the year, powered by an energy storage business that nearly tripled its revenue. The stock has since fallen about 19%, trailing a roughly flat S&P 500 by more than 18 percentage points. When Ormat reports third-quarter results after the close on November 4, the question is whether the market has priced in too much fade, or whether the cooling management itself warned about is arriving faster than planned.
The Street is braced for a softer quarter. Consensus calls for earnings of $0.34 per share, down about 17% from $0.41 a year ago, on revenue of $246.1 million, a 1.5% slip from $249.7 million. That is a sharp step down from the $0.50 and $258.8 million posted last quarter, and it reflects guidance rather than skepticism. Management lifted full-year revenue guidance to $1.15 billion to $1.20 billion from $1.11 billion to $1.16 billion, and raised adjusted EBITDA to $630 million to $650 million. Yet the full-year revenue consensus of $1.15 billion sits at the very bottom of that new range. In effect, analysts accepted the raise on paper while modeling little of the upside. That gives Ormat a real chance to look better than expected, but it also tells you how little faith the Street has in the second half.
Storage is the swing factor. Segment revenue rose 195% in the second quarter to $42.8 million, with gross margin above 56% on strong merchant pricing in the PJM market. Management raised full-year storage revenue guidance to $140 million to $155 million from $95 million to $110 million. It also cautioned that second-half merchant pricing would normalize, pulling storage margins toward 30% to 40%. A third-quarter storage margin inside that band would validate the outlook. A figure well below 30%, or revenue tracking short of the pace needed to reach the raised target, would suggest the first-half windfall was more fleeting than advertised.
The core geothermal business faces its own test. Electricity guidance was trimmed to $710 million to $725 million because of delays at a Caribbean project, and management flagged West Coast heat as a likely drag on summer generation, since hot air reduces plant efficiency. Second-quarter electricity growth of 5.8% came from Blue Mountain, rate recovery at Puna, well work at Olkaria and less U.S. curtailment. Holding that momentum through a hot quarter would reassure investors that the base business can carry results as storage normalizes. Product is the other soft spot. Second-quarter segment revenue fell 21.6% and gross margin collapsed to 9.7% on cost overruns and currency pressure at a European project. Because management still guides to about 18% for the year, a visible margin rebound is needed now, not just promised for later.
This is also the first report since the September Investor Day. Updates on the Omega 100 binary unit, the Denali storage project under its 20-year tolling deal, Lone Mountain under the Google portfolio agreement, and the SLB Desert Peak enhanced geothermal pilot will shape the longer-term story, even if they barely touch this quarter's numbers.
Sentiment has turned noticeably darker, swinging from modestly bullish before the last report to clearly bearish now. The chart agrees. At $87.13, the shares sit just above their post-earnings low of $85.77 and far below the 200-day moving average near $112, after a previous quarter that saw highs above $146. With expectations this compressed, the bar is not high. What matters most is whether Ormat reaffirms or nudges up its raised full-year targets while showing storage margins landing where promised. If it does, the bearish turn looks overdone. If the guidance slips back, the selloff will look like foresight.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-13 | |
| Oct-06 | |
| Oct-05 | |
| Oct-01 | |
| Oct-01 | |
| Sep-24 | |
| Sep-04 | |
| Sep-01 | |
| Aug-22 | |
| Aug-05 | |
| Aug-05 | |
| Jul-01 | |
| Jun-25 | |
| Jun-17 |
