Ormat Crushes Q3 Estimates On A PJM Storage Windfall, But The Core Geothermal Engine Is Still Losing Ground
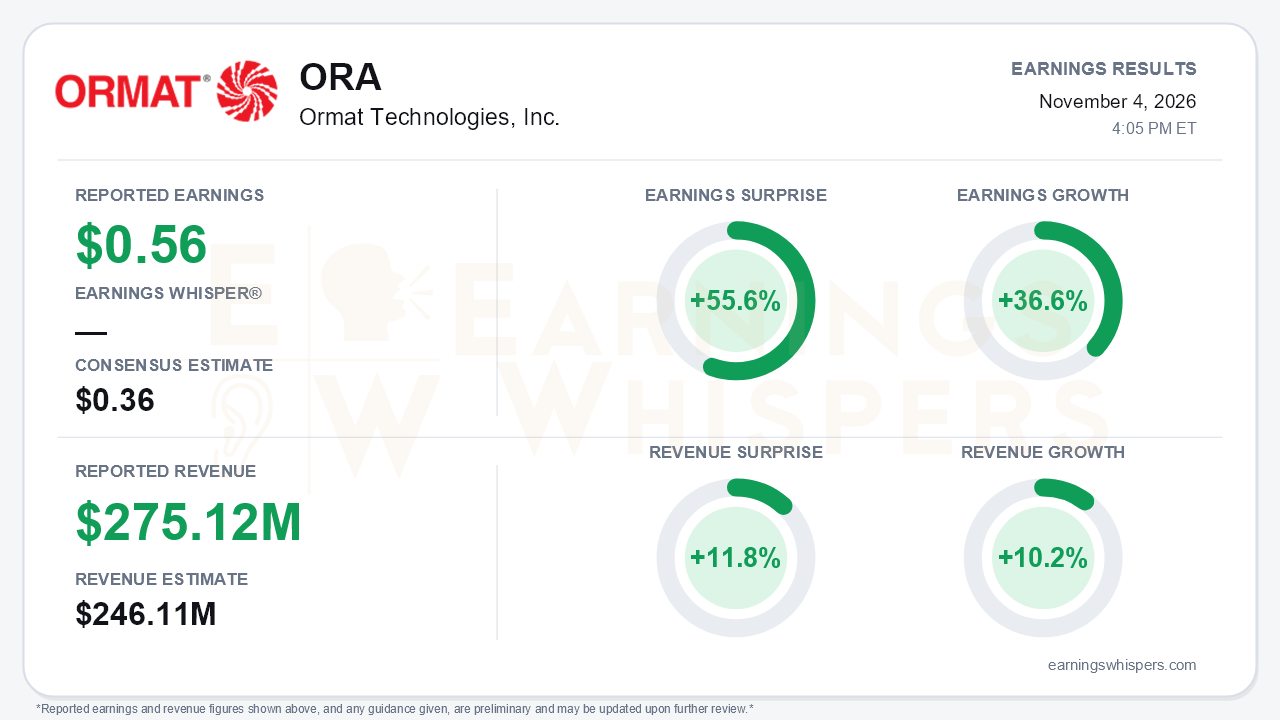
Ormat Technologies delivered a decisive beat in the third quarter. Adjusted EPS of $0.56 topped the $0.36 consensus by 55.6% and grew 36.6% year over year. Revenue of $275.12 million beat expectations by 11.8% and rose 10.2%. Management raised the midpoints of full-year revenue and adjusted EBITDA guidance for the second straight quarter. The source of the upside deserves scrutiny, though. Nearly all of it came from Energy Storage, a segment riding unusually strong merchant pricing in PJM. Meanwhile, the geothermal Electricity business that anchors the valuation shrank, and its outlook was cut again. That is the central tension.
The segment math makes the point. Energy Storage revenue jumped 145.2% to $49.9 million, and segment gross margin expanded to 62.1% from 39.4%. As a result, storage gross profit rose to roughly $31 million from about $8 million a year ago. Consolidated gross profit rose only $13.4 million, to $77.4 million, which means Electricity and Product gross profit both declined. Electricity revenue fell 2.1% to $163.7 million, and its gross margin compressed to 22.2% from 25.4%. Product revenue slipped 1.2%, with gross margin down to 16.5% from 21.7%. Below the operating line, the GAAP picture is also less clean than the 32.2% net income gain suggests. Interest expense rose to $44.2 million from $35.7 million, and pre-tax income grew only modestly to $22.6 million. A larger income tax benefit and $15.7 million from the sale of tax benefits carried GAAP net income to $31.9 million, or $0.51 per diluted share.
The call explained the Electricity weakness mostly as a one-off. A hurricane-related forced outage at Puna cost about $5.1 million of third-quarter revenue. Excluding Puna, segment gross margin would have been 24.5%, which is still below the prior year. A fourth-quarter well clean-out will further reduce Puna generation. That helps explain why Electricity revenue guidance fell to $700-710 million, down from $710-725 million last quarter and $715-730 million before that. Management still expects Electricity gross margin to rise year over year in Q4 and to "jump" in 2027. It cited recontracted PPAs priced above $100/MWh, and it reiterated a 40% Electricity gross margin goal for 2030. Product is the more structural concern. Backlog has fallen to $183 million from $352 million at year-end, and management acknowledged few new third-party projects in the market.
The storage strength is real but not fully repeatable. Full-year storage revenue guidance rose to $160-170 million, and margin guidance to 50-55%, both up sharply from earlier in the year. However, management said October PJM pricing was "normal" and expects 2027 to come in below an exceptional 2026. Longer term, the catalysts look more durable. The storage pipeline grew to about 3 GW from 2.5 GW, and Ormat committed to the 100 MW/400 MWh Denali project under a 20-year tolling agreement. The company also raised its estimate of potential EGS development to 5-6 GW from 3-4 GW, backed by up to $35 million in DOE funding and Dixie Valley PPA talks with hyperscalers and utilities. Bears have legitimate ammunition on EGS, however. Drilling at the pilots is now expected in late 2026 or early 2027. Management conceded that a $100/MWh PPA is insufficient for early projects and that the first project will exceed its cost-per-MW target. Leverage is also elevated, with net debt to EBITDA at 4.3x and liquidity down to $977 million.
One point about guidance needs clarifying. Earnings Whispers characterizes the update as a narrowing, and that is accurate: the ranges tightened. The tightening came almost entirely from raising the low ends, however, so the midpoints moved up even though the top ends did not.
The market had been skeptical heading into the print. Investor sentiment fell from a modestly positive 0.12 after the prior report to a modestly negative -0.14. That is a meaningful reversal, though not an extreme reading. Shares sit at $94.28, down 12.5% since the opening after the August report and about 15% below the 200-day moving average of $111.16. The Earnings Whispers trend signals lean negative on price and AVWAP, although momentum has turned positive.
The bottom line is that Ormat produced a high-quality headline beat and a credible long-term growth narrative, but the quarter's earnings power was borrowed heavily from a PJM pricing environment management itself expects to fade. Until Electricity margins actually recover and Product backlog stabilizes, the storage windfall alone is unlikely to fully resolve investor doubts reflected in the stock's discount to its 200-day average.
Read our earnings preview for Ormat Technologies, Inc.: https://www.earningswhispers.com/article/ORA/21901
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-27 | |
| Oct-13 | |
| Oct-06 | |
| Oct-05 | |
| Oct-01 | |
| Oct-01 | |
| Sep-24 | |
| Sep-04 | |
| Sep-01 | |
| Aug-22 | |
| Aug-05 |
