OceanaGold's Cost Creep Faces A Key Test As Shares Slide Toward Post-Earnings Lows
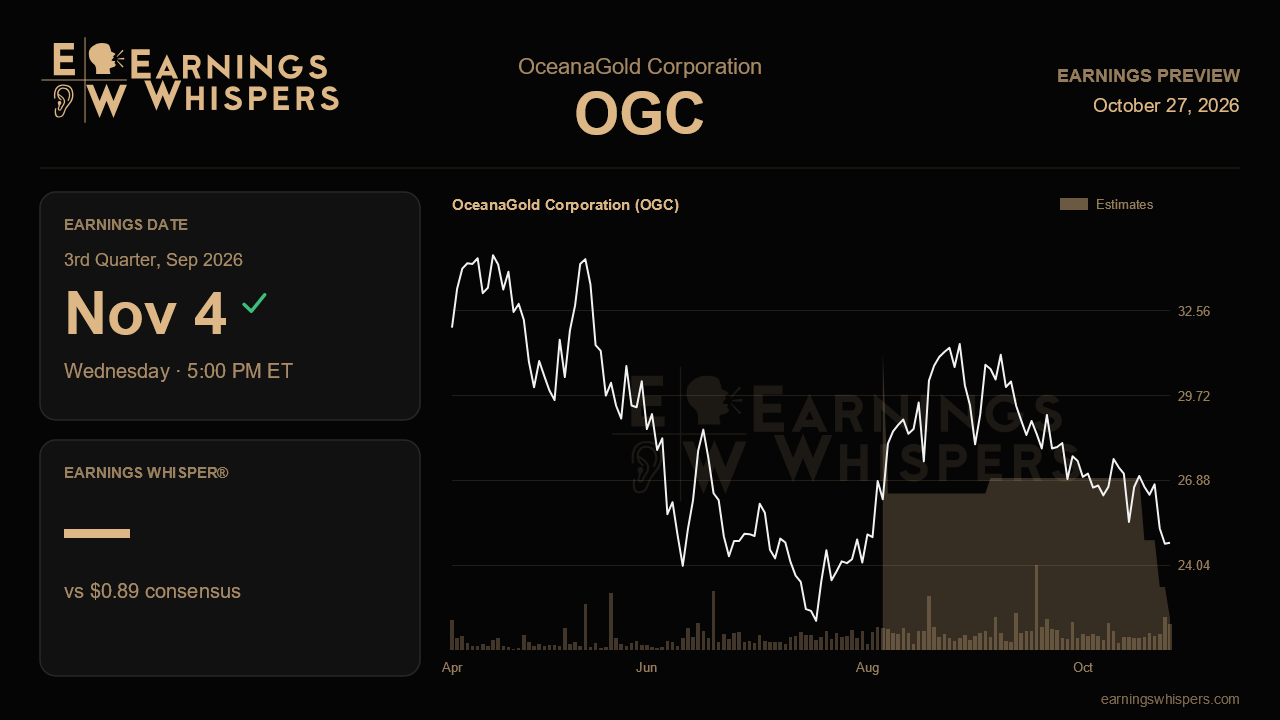
OceanaGold heads into its third-quarter report with a peculiar problem for a gold miner enjoying record margins: the conversation has shifted from how much money it is making to how much it costs to make it. Last quarter, management delivered a record 61% adjusted EBITDA margin and a growing, debt-free cash pile, yet the headline revision was that full-year all-in sustaining costs would now land near the upper end of guidance. The report due after the close on November 4 should reveal whether that was a one-time adjustment or the start of a steadier drift.
The Street expects earnings of $0.89 per share, down from $0.98 in the second quarter, when revenue reached $647.3 million. That implied step down is not alarming on its face. Second-quarter free cash flow already moderated to $130 million from $255 million in the first quarter as realized gold prices eased off their highs and tax and government payments rose, so analysts appear to be pricing in some combination of softer realized prices and stickier costs. The question is which of those forces does more of the damage.
Costs deserve the closest look. Management singled out labor inflation as the largest driver, most acute at Hale, where there is no currency cushion. It also flagged unhedged diesel exposure at Waihi and Didipio, estimating roughly $25 per ounce of added cost if oil holds near $100 a barrel, along with heavier maintenance spending and thinner silver by-product credits. That is a notable progression. A year ago the message was that costs would move back inside the range; by the first quarter it was the top half at worst; by the second it was the upper end. A third-quarter AISC that holds steady and a reaffirmed upper-end outlook would validate the idea that the pressure is contained. Any hint that costs could break above the range would challenge the core margin story.
Volume is the offset. Production rose 7% sequentially to about 139,000 ounces last quarter, helped by record mill throughput at Hale and Waihi and an exceptional first half at McRae's, which delivered 64% of its full-year midpoint. That front-loading cuts both ways: it de-risks the annual target, but it also means a softer second half at McRae's would not be surprising. Spreading fixed costs over more ounces is the most direct way to defend unit costs, so sustained throughput at Hale and a smooth ramp in Didipio's resumed decline development would carry real weight. Progress on the Waihi North twin tunnels toward Fere Kereponga, the Hale paste plant, and the phase-four fast-track application at McRae's that could stretch mine life into the 2040s will matter more for valuation than for this quarter's numbers, but evidence of steady advancement would reinforce the growth narrative.
The market has not been generous. Shares have fallen 5.1% since the last report, trailing the S&P 500 by more than four percentage points, and at $24.79 they sit well below the 200-day moving average of $28.27 and only about 2% above the post-earnings low of $24.28. The trading range has narrowed from the prior quarter's wide swings, suggesting a stock drifting rather than capitulating. Sentiment has improved modestly from the previous quarter but remains only mildly bullish, which points to a cautious rather than demanding bar.
That combination of a reasonable estimate and a discouraged stock gives OceanaGold room to reassure. Capital returns, which totaled $174 million in the first half, and a cash balance that reached $655 million provide a cushion. Ultimately, though, the report will be judged on one issue: whether the cost guidance has stopped moving. If AISC holds at the upper end while production stays on track, the record-margin thesis survives intact. If the range shifts again, the market will likely treat rising costs, not the gold price, as the defining story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-06 | |
| Sep-25 | |
| Sep-24 | |
| Sep-24 | |
| Sep-24 | |
| Sep-23 | |
| Sep-21 | |
| Sep-09 | |
| Aug-17 | |
| Aug-17 | |
| Aug-05 | |
| Jul-22 | |
| Jul-22 | |
| Jul-13 |
