OceanaGold Beats On EPS And Cash Flow, But A Haile Shortfall And Capex Creep Load The Year Onto Q4
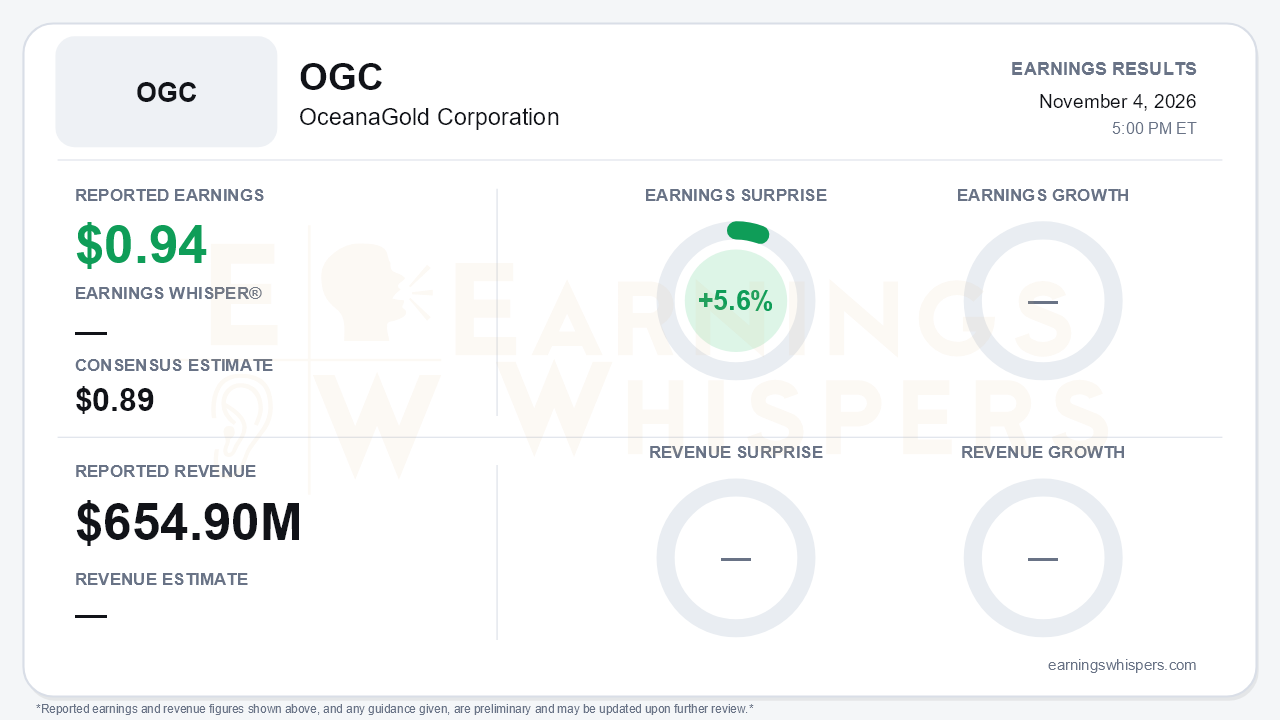
OceanaGold reported third-quarter adjusted EPS of $0.94, beating the $0.89 consensus by 5.6%, on revenue of $654.9 million. Against last year the improvement is large. Adjusted EPS more than doubled from $0.40, and revenue rose from $448.5 million as gold sales climbed to 140,900 ounces from 116,200. The sequential picture is flatter. Adjusted EPS eased from $0.98 in the second quarter, revenue was essentially unchanged from $647.3 million, and adjusted EBITDA margin slipped to 58% from a record 61%. (The call analysis cites $0.99 for the prior quarter, which matches the release's GAAP diluted EPS rather than its adjusted figure.) That is the central tension. The beat and the cash generation are real, but the year's growth narrative now depends heavily on a fourth quarter that has not yet happened.
The headline cost improvement deserves a closer look. Consolidated AISC fell 13% sequentially to $1,874 per ounce, but much of that came from Didipio. Didipio's AISC collapsed to $687 from $1,589 as sustaining capital and capitalized mining dropped sharply and copper by-product credits grew on 3,400 tonnes of copper sold at $6.54 per pound. Didipio's figures also exclude a $16.2 million Additional Government Share that management treats as income tax. Haile's AISC improved to $1,811, helped by minimal capitalized stripping and a favorable $22.7 million inventory adjustment. Macraes moved the other way: production fell to 37,200 ounces and AISC rose to $2,155 from $1,932. Cash generation was the cleaner positive:
- Operating cash flow reached $325 million.
- Free cash flow rose to $155 million from $130 million.
- Year-to-date free cash flow of $541 million nearly matches all of 2025.
- Cash grew to $729 million with no debt.
On the call, the most important change was at Haile. Management had signaled that Haile's third-quarter output would exceed the prior quarter's roughly 60,000 ounces. Instead it produced about 55,000. A modified mine plan to de-risk the Ledbetter Pit's south wall kept mining on lower-grade upper benches. Mining reached the higher-grade lower benches by the end of September, and October output of 27,400 ounces supports management's call for Haile's strongest quarter of the year. Even so, Haile is now guided toward the low end of its production range and the high end of its AISC range. Consolidated production is held around the guidance midpoint. AISC remains at the upper end, reflecting labor and consumables inflation, unhedged energy and weaker silver credits. Macraes is now expected near the top of its range, but that offsets Haile rather than lifting the consolidated outlook.
Capital is the other moving part. Total 2026 investment is now expected to run about $45 million, or 7%, above the $645 million guide. Last quarter, management had described spending as in line. The overrun is growth-oriented rather than remedial: accelerated Macraes Phase 4 work, Didipio fleet investment, Waihi North activities pulled forward from 2027, and $10 million of success-driven exploration. The project pipeline also deepened:
- The MP4 permit application is lodged, with a decision expected mid-2027.
- Drilling now points to Macraes mine life potentially running into the 2040s.
- The Waihi North decline has advanced about 500 meters, up from roughly 200 at the second-quarter call.
- A January 2027 Waihi technical report will address reserves and a possible plant expansion to 1.2 million tonnes per annum.
- Wharekirauponga continues to return high-grade results.
The Ausgold acquisition adds the Katanning project, targeting first ore in 2029, for up to roughly $137 million in cash. The call flagged that this outlay may temper the fourth-quarter buyback pace. Buybacks totaled $193 million through September against a $350 million 2026 authorization.
Investor sentiment improved from 0.07 to 0.21. That is a meaningful but not dramatic shift, and it leaves expectations moderately positive rather than euphoric. The tape has been less forgiving than the fundamentals. Shares at $25.78 are down 1.3% from the $26.11 open after the August report and sit 8.3% below the 200-day moving average of $28.12. The market has not paid up for record cash generation, likely because realized gold prices have cooled from second-quarter levels and the Haile miss reopened questions about execution. Earnings Whispers trend readings are mixed, with momentum neutral and AVWAP still negative.
The bottom line is that OceanaGold delivered a solid beat, a debt-free balance sheet and a richer growth pipeline. However, the quarter shifted more execution risk into the fourth quarter. Haile must deliver the higher grades its October output suggests, cost inflation is keeping AISC pinned near the top of guidance, and capital spending is now running ahead of plan. If Haile performs and gold prices hold, the stock's discount to its 200-day average looks more like skepticism than a verdict. If it stumbles, bears have legitimate ammunition.
Read our earnings preview for OceanaGold Corporation: https://www.earningswhispers.com/article/OGC/21898
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Oct-27 | |
| Oct-06 | |
| Sep-25 | |
| Sep-24 | |
| Sep-24 | |
| Sep-24 | |
| Sep-23 | |
| Sep-21 | |
| Sep-09 | |
| Aug-17 | |
| Aug-17 | |
| Aug-05 | |
| Jul-22 |
