QuinStreet Must Show Its Growth Engine Can Outrun A Softening Auto Insurance Market
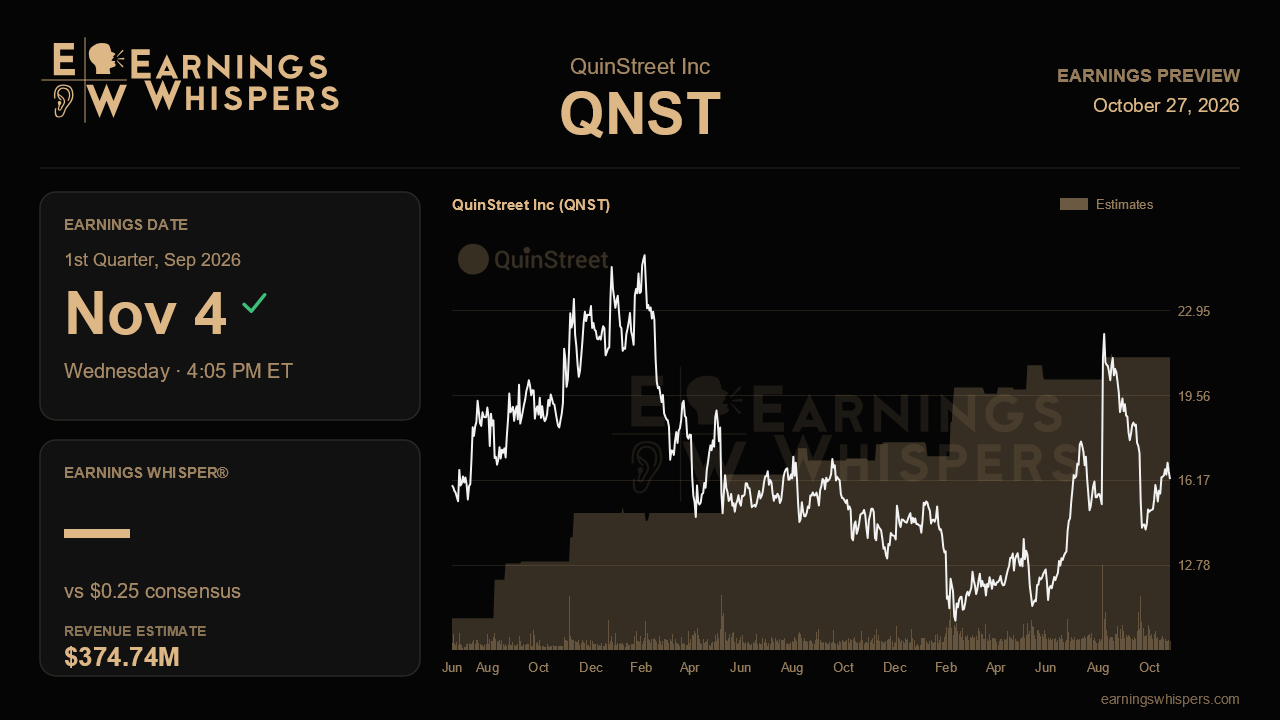
QuinStreet enters its fiscal first-quarter report with a striking disconnect. Management closed fiscal 2026 with its best quarter yet, issued a fiscal 2027 outlook that amounted to a genuine raise, and described its prospects in the most confident terms it has used in years. The stock has gone the other way, falling 17.6% since that report while the S&P 500 was roughly flat. The September quarter is the first real test of whether that confidence was earned or whether the market was right to take profits.
The Street is looking for earnings of $0.25 a share on revenue of $374.7 million, a 31.1% jump from the $285.9 million reported a year ago. That revenue figure sits almost exactly at the midpoint of management's $370 million to $380 million guidance range. Analysts were closer to $359 million when the guide came out, so they have moved up to meet the company rather than leap past it. That puts the bar at a reasonable height: an in-range result will not surprise anyone, and the reaction will hinge more on the details. The earnings estimate deserves a closer look. It is more than triple the $0.08 earned a year ago but well below last quarter's $0.33, on revenue that is essentially flat sequentially. The Street appears to be baking in some margin give-back from the 11.1% adjusted EBITDA margin posted in the June quarter, which is plausible given the full-year guide calls for a 10.3% margin. Holding margins closer to the fourth-quarter level would be the cleanest sign that operating leverage is structural rather than a one-quarter peak.
The two growth engines behind last year's acceleration face different tests. Home services, supercharged by the HomeBuddy acquisition, grew 88% in the fourth quarter to $141.6 million and now runs above a $500 million annual pace. Because the HomeBuddy comparison does not lap until the second half of the fiscal year, this segment should still post outsized growth now. Anything that looks like early fade would undercut the claim that integration ran ahead of schedule. Auto insurance is the more delicate story. Growth re-accelerated to 37% last quarter, but management shifted its language, describing a soft market in which several carriers have already cut rates. That is a notable change from earlier calls, which framed insurance as poised for another leg up. The question is whether strong carrier demand for customers can offset the loss of the pricing tailwind. Commentary on carrier budgets and rate actions may matter as much as the reported growth rate.
There are also newer threads to follow. Management said its QRP and 360 Finance businesses have moved past the heavy investment phase and should exceed $20 million in combined revenue this year, and it pointed to its integration with OpenAI's advertising platform in insurance and home services as potentially its largest future channel. It also signaled that one or two accretive acquisitions were likely, none of which is included in guidance. Progress on any of these would support the idea that internal plans carry more upside than the official outlook.
Sentiment remains bearish but has eased slightly from the prior quarter. The stock trades at $16.22, comfortably above its 200-day moving average of $14.44 but well off its post-earnings high of $22.29 and closer to the $13.96 low, suggesting the initial enthusiasm has been largely unwound.
Ultimately, this report comes down to whether QuinStreet can deliver revenue in its guided range while holding margins near the 10% threshold it worked so hard to cross, even as auto insurance pricing softens. Reaffirming or nudging up the full-year guide would validate last quarter's optimism. A margin stumble or cautious insurance commentary would suggest the selloff was more than profit-taking.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-13 | |
| Sep-24 | |
| Aug-14 | |
| Aug-12 | |
| Aug-07 | |
| Aug-06 | |
| Jul-23 | |
| Jun-02 | |
| May-11 | |
| May-08 | |
| May-07 | |
| May-07 | |
| May-07 | |
| Apr-23 |
