Royal Gold's Deferred Copper Guidance Call Takes Center Stage As EPS Bar Eases
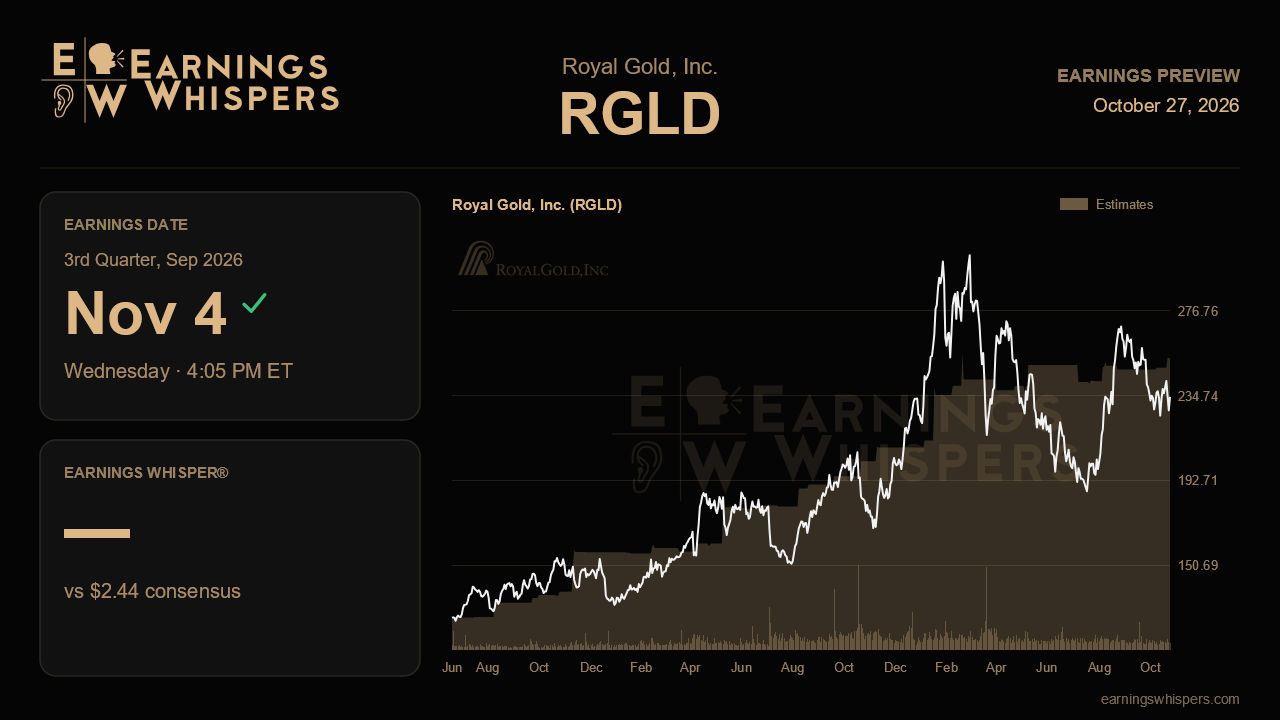
Last quarter, Royal Gold's management made an unusual choice. Its copper and other base-metal sales were running at or above the top of guided ranges, yet it declined to raise the outlook. It cited the volatility of its new Antamina net profits interest and pushed the decision to this report. That makes the November 4 release, due after the close, a test of more than the quarterly numbers. It will show whether management's caution was simple prudence or a sign that the base-metal tailwind was already peaking.
The Street is looking for earnings of $2.44 per share, up 18.5% from $2.06 a year ago. That is solid growth, but it trails the company's transformation on the revenue line. Quarterly revenue has roughly doubled from the $252.1 million posted a year earlier, and the gap tells the story of the 2025 acquisitions. The Sandstorm, Horizon and Kansanshi deals built a larger, more diversified company. They also brought heavier depreciation, which climbed to $96 million last quarter on stepped-up carrying values. Per-share accretion is real, but it arrives more slowly than headline revenue suggests.
The estimate also sits below last quarter's $2.56, and that sequential step down looks sensible rather than worrying. The prior period included roughly $22 million of one-time revenue from settling the Relief Canyon delivery obligation, and that will not recur. Management also described the earlier dip from a record $469 million to $451 million as delivery timing, not a slowdown. A clean quarter without one-offs that still lands near consensus would support the view that the underlying run rate has settled at a much higher level. A shortfall blamed again on timing would start to test that explanation.
The operating details matter as much as the headline figure. Antamina is the swing factor. The royalty produced about $26 million in the first half, against $16 million to $17 million in full-year totals for 2023 and 2024. Continued strength there, along with zinc at Antamina and nickel at Voisey's Bay, would give management cover to finally lift base-metal guidance. A softer contribution would justify last quarter's restraint and keep the formal outlook merely reaffirmed. The Chilean assets also deserve a look. Andacollo and Casarones had temporary winter-weather problems, and the company said those would not alter its outlook. Evidence that both are back to normal would close that loop. Mt. Milligan, a modest year-over-year drag last time, is worth tracking as well.
The balance sheet and capital-return story offers another checkpoint. Royal Gold repaid $200 million on its revolver last quarter and laid out another $175 million over the summer. It now targets full repayment by year end, well ahead of earlier timelines that kept getting pulled forward. It also made its first purchases under the $500 million buyback, about $30 million worth. Faster debt reduction or a larger buyback would reinforce the shift in management's tone from digesting deals to returning cash. Investors should also want an update on Platreef, which delivered its first stream ounces and is targeting Phase 1 commercial production in the fourth quarter.
The market has leaned in, if cautiously. Shares are up 8.8% since the last report while the S&P 500 slipped, and sentiment has improved from clearly bearish to only mildly negative. Still, at $234 the stock trades below its 200-day moving average of about $242. It is also well off its post-earnings high of $271, which suggests some of the earlier enthusiasm has faded. Ultimately, the report hinges on whether Antamina and the broader base-metal book hold up well enough for management to deliver the guidance raise it deferred. A raise would confirm that the reshaped Royal Gold is compounding. Another reaffirmation would keep the story intact but leave investors waiting for proof.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-20 | |
| Oct-01 | |
| Oct-01 | |
| Sep-23 | |
| Sep-15 | |
| Sep-14 | |
| Sep-09 | |
| Sep-09 |
Golden Royalties Have This Gem Polishing A Breakout As These Trends Sparkle
RGLD
Investor's Business Daily
|
| Sep-03 | |
| Aug-31 | |
| Aug-27 | |
| Aug-26 | |
| Aug-18 | |
| Aug-05 |
