Royal Gold Misses On EPS But Posts Record Volumes And Turns Debt-Free A Year Early, As Sandstorm Dilution Narrows Per-Share Growth
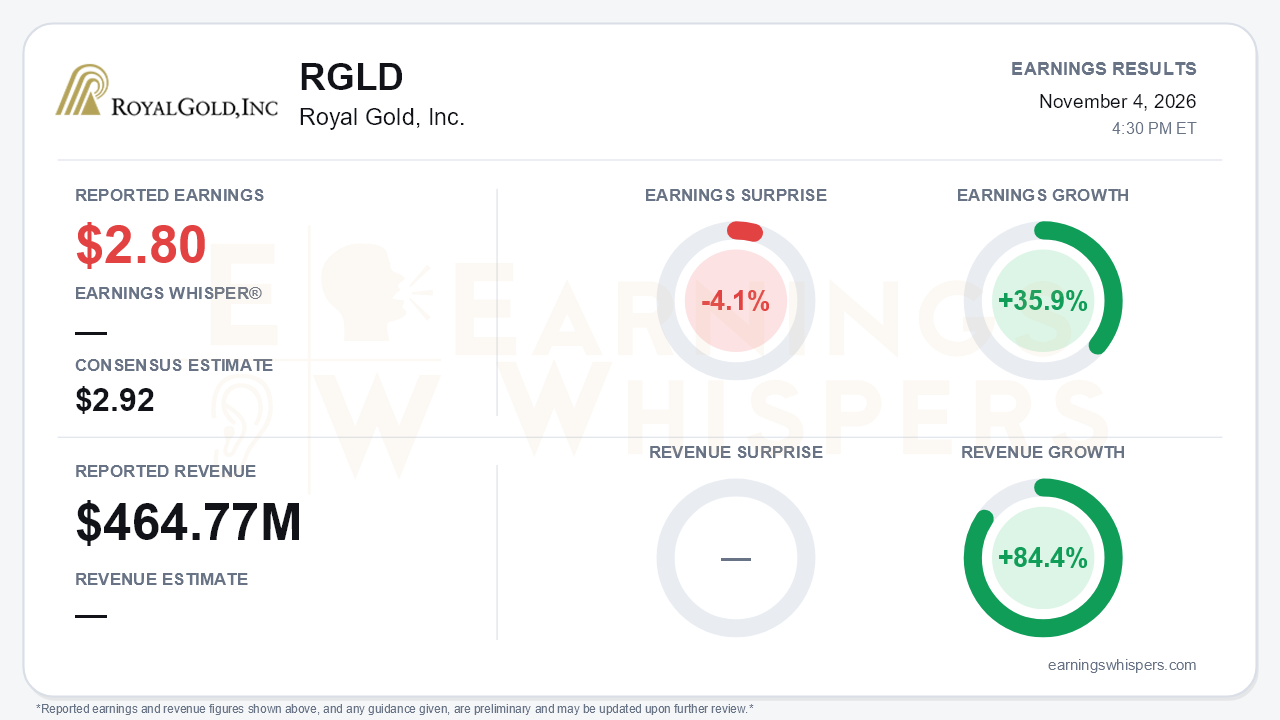
Royal Gold delivered a quarter that looked strong on every operating measure except the one Wall Street was watching most closely. Adjusted earnings of $2.80 per share missed the $2.92 consensus by 4.1%. Revenue of $464.77 million grew 84.4% year over year, but adjusted EPS grew a far slower 35.9%. That gap is the central tension. The Sandstorm and Horizon acquisition roughly doubled the revenue base. It also lifted the diluted share count to about 84.9 million from 65.8 million and more than doubled quarterly DD&A to $82.0 million. Per-share leverage to the larger portfolio is real, but it is not proportional.
The quality of the quarter holds up better than the miss implies. GEO sales hit a record 109,000, up from 100,000 in Q2 and 96,300 in Q1. Operating cash flow reached a record $344.4 million, and the adjusted EBITDA margin edged up to 84% from 83%. Sequentially, adjusted EPS improved from $2.56 in Q2 and $2.72 in Q1. Revenue, however, was essentially flat against Q1's $469 million. Record volumes were partly offset by a softer price deck: gold averaged $4,262 in Q3 versus $4,545 year to date, and silver averaged $62.59 versus $73.24. Year-over-year revenue growth of 84% also marks a deceleration from the 111% nine-month pace, as the acquisition anniversary approaches. GAAP EPS of $2.68 absorbed a $15.7 million fair-value loss on Entrée Resources shares, which helps explain why the net income margin slipped to 49% from 52% a year ago.
The call preserved a credible growth story built on volume and balance sheet, not just metal prices. The biggest development was the revolver payoff on October 19. Management had initially targeted mid-2027 for repaying the $1.225 billion drawn at closing, then pulled that in to early 2027 and then Q4 2026. Royal Gold is now debt-free with the full $1.4 billion facility undrawn. Guidance moved modestly higher:
- Other-metals sales were raised to $53–$56 million.
- Silver and copper are now expected at or above the top of their ranges.
- Gold sales are tracking only around the midpoint, so upside there is limited.
At Cortez, the Legacy Zone ramp lifted the blended royalty rate to 4.45%, above the 3.5%–4% guide, and management sounded constructive on 2027. CEO Bill Heissenbuttel said the Sandstorm deal has delivered "only pluses" and that cash flow has "never been stronger."
Bears still have legitimate ammunition at the operator level. Antamina, which contributed roughly $40 million of revenue over nine months, suspended production on October 27 after a fatality. First Quantum cut the top of its Kansanshi copper range to 185,000 tonnes from 205,000, which caps gold deliveries. Teck now expects Andacollo at the low end after flooding. The gold share of revenue slipped to 73% from 76% in Q2, and G&A is tracking near the top of its $50–$60 million range. Stream cost per gold ounce rose to $893 from $693 a year ago as price-linked payments climbed. Management also signaled it may favor building cash over buybacks, after repurchasing $49 million of stock in Q3. Kinross's Great Bear buyback will bring in about $43 million but trims that royalty to a 1.5% NSR.
The forward catalyst list is unusually long:
- MARA received RIGI approval ahead of expectations.
- The Barrick-Newmont settlement folds the fully royalty-covered Fourmile project into NGM.
- Red Chris is targeting a final investment decision in early 2027.
- A Côté reserve expansion update is expected by year-end.
- Platreef reached 70% of design throughput in October.
With no debt and a pipeline management described as busy, including Australia opening to streaming, capital redeployment is now the next lever.
Investor sentiment improved meaningfully into the report, rising from -0.27 to -0.04. That is close to neutral but not yet positive, suggesting skepticism has largely, though not fully, faded. Shares have gained 14.4% since the open after the August report, to $246.08, and sit just 2.0% above the 200-day moving average of $241.16. That leaves the stock near a level the market has been treating as a pivot rather than extended well above it. The Earnings Whispers trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Royal Gold missed the consensus number but strengthened its fundamental position. Record volumes, record cash flow, a slightly higher margin and an early debt payoff outweigh a modest EPS shortfall driven by dilution, depletion and softer quarterly prices. The open questions are how much operator setbacks at Antamina, Kansanshi and Andacollo weigh on 2027, and how quickly management can turn a clean balance sheet into accretive growth.
Read our earnings preview for Royal Gold, Inc.: https://www.earningswhispers.com/article/RGLD/21924
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-27 | |
| Oct-20 | |
| Oct-01 | |
| Oct-01 | |
| Sep-23 | |
| Sep-15 | |
| Sep-14 | |
| Sep-09 | |
| Sep-09 |
Golden Royalties Have This Gem Polishing A Breakout As These Trends Sparkle
RGLD
Investor's Business Daily
|
| Sep-03 | |
| Aug-31 |
