Rayonier's Lumber Rebound Faces Its Proof Point As Shares Slump Ahead Of Q3
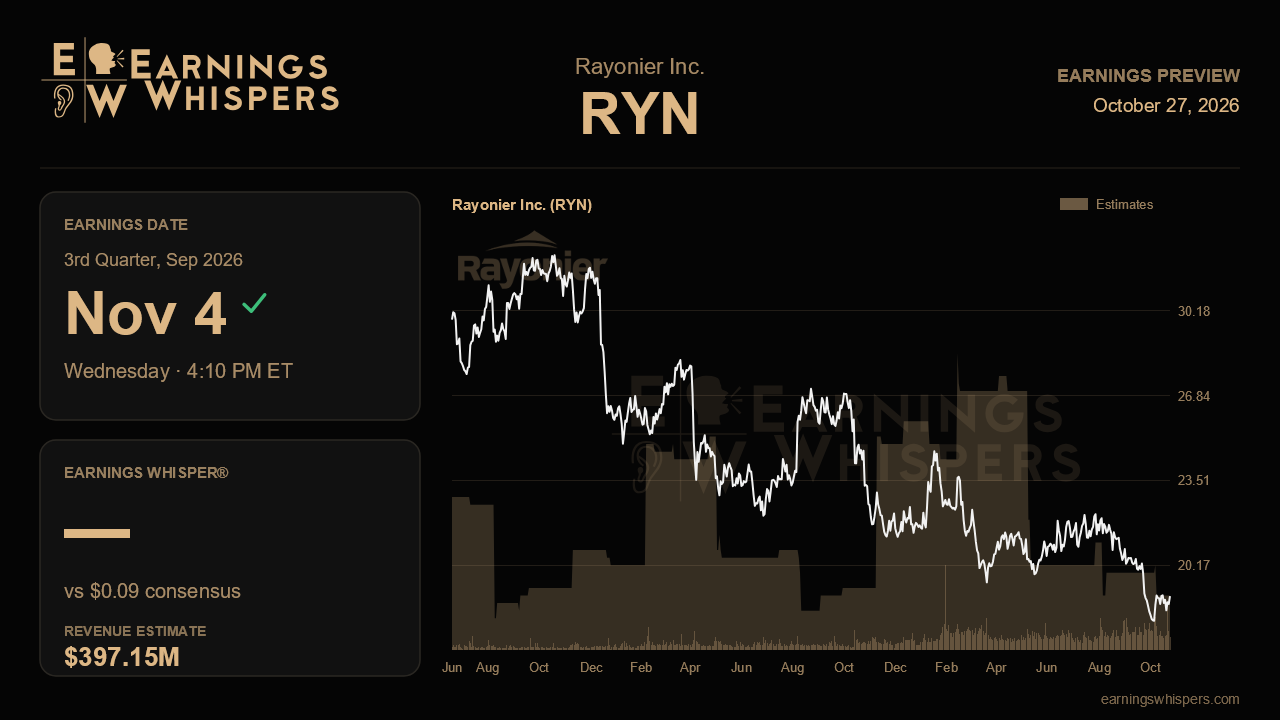
Rayonier heads into its third-quarter report with an awkward disconnect. Last quarter management laid out its most upbeat story in a year, built on a lumber recovery that defied the usual summer swoon, yet the shares have fallen 14.1% since that call while the S&P 500 barely moved. The November 4 release, due after the close, is the market's first real chance to judge whether the wood products turnaround was a durable shift or a well-timed spike.
The Street is not asking for much on the surface. Consensus calls for earnings of $0.09 a share on revenue of $397.2 million, essentially flat with the $0.10 and $396.5 million posted last quarter. The year-over-year comparisons look dramatic, with revenue expected to more than double while EPS falls roughly 72%, but that mostly reflects the combination with legacy PotlatchDeltic, which brought sawmills and a larger, lower-margin revenue base along with merger-related noise. The more useful yardstick is sequential: a flat quarter after adjusted EBITDA climbed from $62 million to $94 million to $124 million over three periods would suggest the momentum has paused rather than reversed.
Lumber is the hinge. Wood products EBITDA reached $25 million in the second quarter, the best showing for the legacy Potlatch mills since 2022, as realizations jumped about 18% to $505 per thousand board feet. Management stressed that the post-spring price weakness of the prior two years never arrived, noted that early July pricing was modestly higher still, and guided third-quarter shipments to 320 million to 330 million board feet, above the prior quarter's target. Validation would mean shipments landing inside or above that range with realizations holding near or above $505. A slide back toward the low $400s would undercut the central argument that tighter supply, not seasonality, is driving prices.
The timber side carries its own tests. Southern harvest guidance for the quarter of 3.1 million to 3.3 million tons is a step up from the second-quarter range, and the full-year outlook was tightened toward the upper part of its prior band. Hitting it while absorbing salvage wood from the Georgia fires, which burned roughly 9,300 acres, would show the network can handle extra regional supply without eroding prices. Pulpwood is the swing factor worth watching closely. After quarters of heavy pricing pressure, management described the market as stabilized, citing containerboard price increases and better mill operating rates. Any evidence that stabilization is turning into actual price improvement would be a meaningful upgrade; renewed weakness would revive a long-running drag. In the Northwest, indexed Idaho log prices were expected to move modestly higher.
Real estate is set up to be a softer contributor. The full-year EBITDA outlook of $180 million to $200 million has not budged across three calls despite strong first-half closings, and the third-quarter guide of $25 million to $35 million implies a lighter back half. A result in range is already priced as a neutral; the bigger question is whether management finally lifts the annual figure or quietly signals the low end. Updates on the Washington-for-Texas and Alabama timberland swap, solar land interest and the pace of buybacks, which accelerated to $72 million last quarter, will shape the cash flow narrative.
Sentiment has warmed noticeably, moving from modestly bearish before the last report to moderately bullish now, even as the stock trades below its 200-day moving average near $21 and sits closer to the bottom of its post-earnings range than the top. That combination suggests investors like the story but have not yet paid for it. The report ultimately turns on one question: can lumber pricing and volumes hold their second-quarter gains through a period that has historically disappointed? If they do, the recent selloff looks premature. If not, the improving narrative loses its strongest pillar.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-16 | |
| Oct-14 | |
| Sep-16 | |
| Aug-20 | |
| Aug-14 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-17 | |
| Jul-16 | |
| Jul-15 | |
| May-26 | |
| May-15 | |
| May-15 |
