Rayonier Beats As Merger Scale Lifts EBITDA, But Fading Lumber Prices And Rising Leverage Test A Disposition-Funded Buyback Pivot
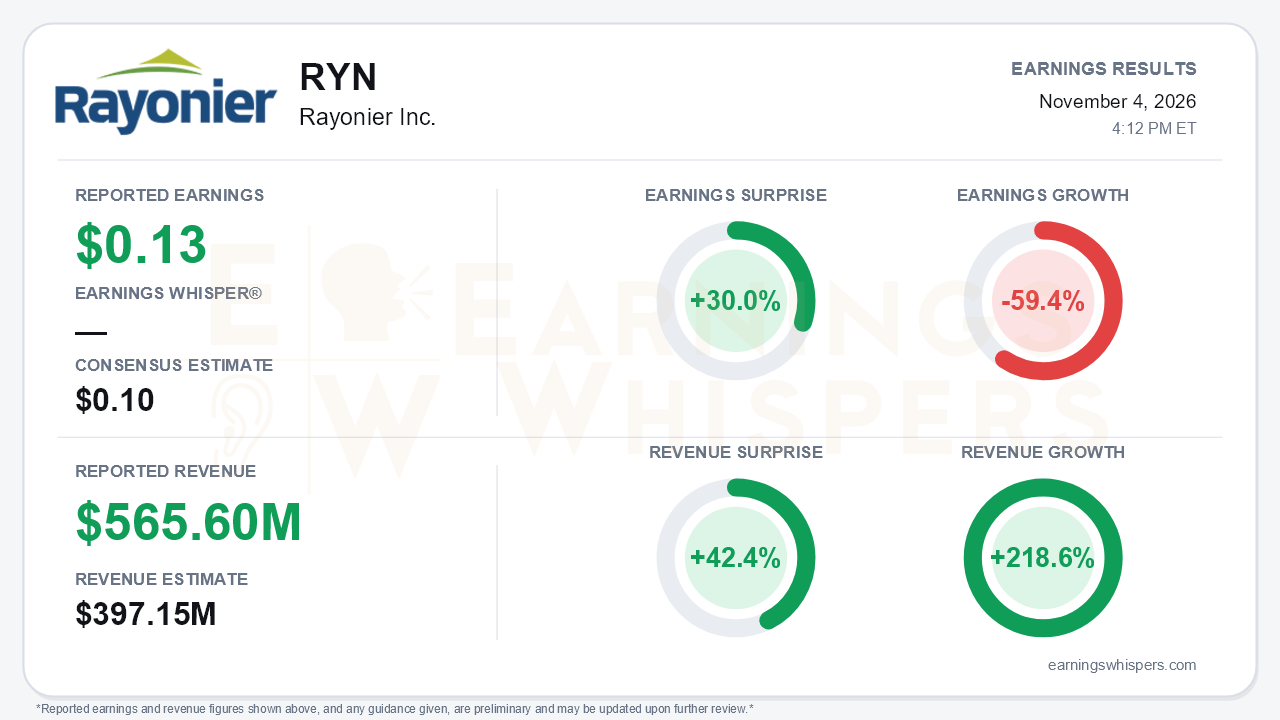
Rayonier delivered a clean beat on paper. Pro forma earnings of $0.13 per share topped the $0.10 consensus by 30.0%, and revenue of $565.6 million beat the $397.15 million estimate by 42.4%. Revenue grew 218.6% year over year, while earnings fell 59.4%. That gap is the first thing investors need to understand. The PotlatchDeltic merger roughly doubled the diluted share count, from about 156 million to nearly 300 million. Adjusted EBITDA climbed to $144.6 million from $114.3 million a year ago, but the per-share result shrank from $0.32. The quarter showed real sequential operating improvement. It also showed that the combined company is still earning less per share than standalone Rayonier did. The central tension is what comes next. The lumber and log-price tailwinds that powered the second and third quarters are already fading, and management is pivoting toward buybacks funded partly by asset sales.
The quality of the beat deserves scrutiny. Reported revenue includes a $145 million Large Disposition of roughly 36,000 Washington acres, part of the RMS like-kind exchange. GAAP net income of $0.41 per share likewise carried $90.6 million of disposition income. Strip that out and pro forma sales were $420.6 million. That still cleared consensus, but by a far narrower margin than the headline surprise suggests. Sequentially, the trend is genuinely better. Adjusted EBITDA rose from $123.7 million in the second quarter and about $94 million in the first. Pro forma EPS improved from $0.10. Real estate EBITDA of $48.5 million crushed the $25 million to $35 million guide. Even so, real estate was down from $73.8 million a year ago, as acres sold fell to 7,127 from 23,348 despite much higher per-acre pricing.
The segment detail shows where the strength came from and why it may not repeat. Wood Products generated $27.0 million of EBITDA on lumber realizations of $528 per thousand board feet, the highest since 2022, helped by tariffs, mill curtailments and trucking shortages that constrained supply. Northwest Timber EBITDA rose to $32.3 million, driven by added Idaho volume and stronger sawlog pricing. Southern Timber is the steadier core, and it looks stalled. EBITDA was flat sequentially at $52.4 million. Delivered pine sawtimber and pulpwood prices were lower year over year on geographic mix and softer markets, and the call noted pulpwood remains about 15% below prior-year standalone levels.
The outlook tilts softer. Quarter-to-date fourth-quarter lumber realizations are running about 6% below the third quarter, and the composite benchmark is 12% lower. Shipments are guided to 295 million to 305 million board feet, down from 327 million. Idaho log prices are expected to fall. Full-year harvest ranges were narrowed again, to 12.2 million to 12.4 million tons in the South and 2.0 million to 2.1 million tons in the Northwest, effectively trimming the top end for a second straight quarter. Management also cited homebuilders pulling back from August through October and solar developers optimizing rather than expanding their pipelines. Real estate is the offset. Management guided fourth-quarter EBITDA of $60 million to $70 million and steered the full year toward the upper end of $180 million to $200 million. Merger synergies have passed a $20 million run rate on the way to $40 million.
Capital allocation is the other major development. The board approved a new $300 million repurchase authorization on top of $66.2 million remaining. Rayonier has bought back $163 million of stock this year, including $59.8 million in the third quarter at an average of $21.00. Shares now sit near $20. Bears have legitimate ammunition here. Cash has fallen to $361.4 million from $842.9 million at year-end. Net debt to enterprise value rose to 22% from 18%, and management acknowledged leverage is approaching its 3x target. As a result, the company now explicitly plans additional timberland dispositions over the next 12 to 18 months to fund buybacks and deleveraging. That approach can create value if asset sales clear at prices above what the stock implies. The trade-off is a shrinking productive land base.
Investors have warmed to the story. Earnings Whispers sentiment moved from slightly negative at -0.108 to a modestly positive 0.259, a meaningful improvement. The tape has not followed. Shares are down 8.6% since opening at $22.07 after the August report and sit 3.6% below the 200-day moving average of $20.93. The trend readings are split along the same line: sequential growth and momentum are positive, while price and AVWAP remain negative.
The bottom line is that Rayonier's third quarter validated the merger's earnings power at the EBITDA level and beat expectations. The headline revenue beat leans on a one-time land sale, however, and per-share earnings remain well below last year. With lumber and Idaho log prices rolling over and harvest guidance drifting lower, the near-term case rests on two things. Real estate must keep delivering, and the disposition-funded buyback must prove accretive without stretching the balance sheet.
Read our earnings preview for Rayonier Inc.: https://www.earningswhispers.com/article/RYN/21931
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-16 | |
| Oct-14 | |
| Sep-16 | |
| Aug-20 | |
| Aug-14 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-17 | |
| Jul-16 |
