Schrodinger's Hosted Shift Faces Its Toughest Test As Revenue Is Expected To Shrink
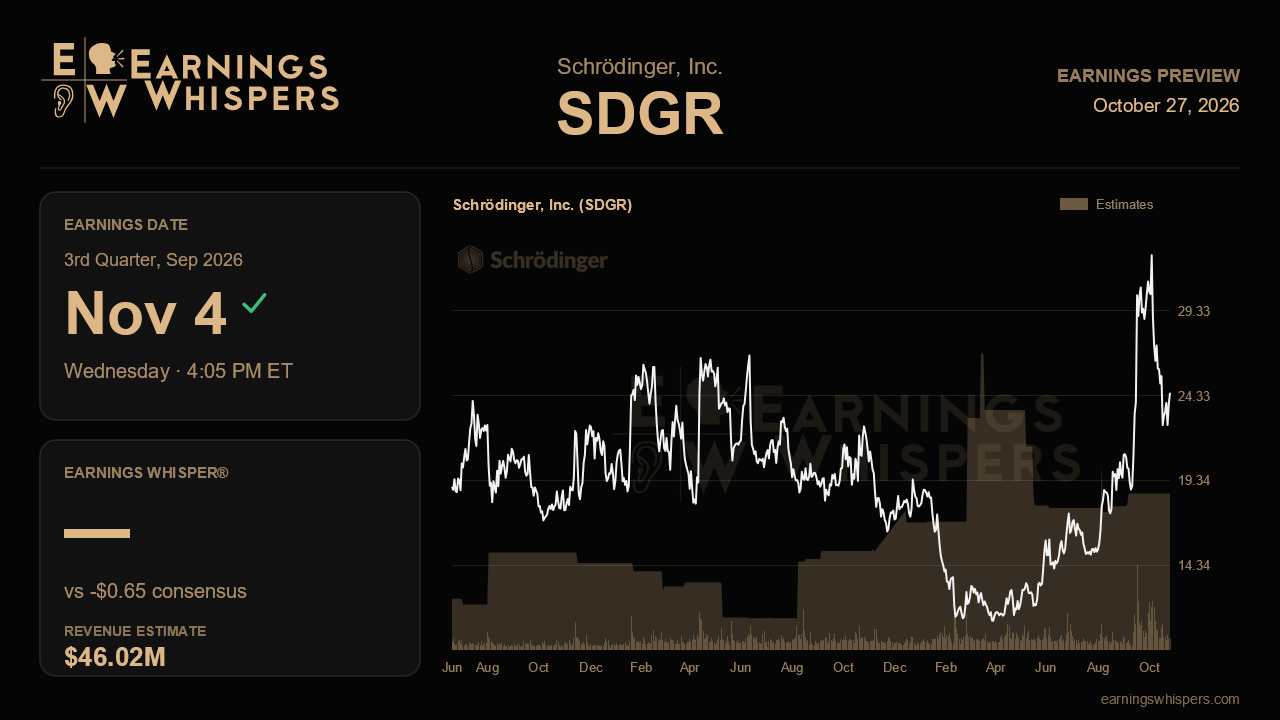
Schrödinger heads into its third-quarter report with a story that sounds better than the numbers Wall Street expects it to print. Last quarter, management described a clear turn: biotech demand recovering, annual contract value growth re-accelerating, and the Bunsen AI co-scientist landing Bristol Myers Squibb as its first major commercial customer. The market bought in. Yet the consensus for the September quarter calls for revenue to fall and losses to widen. That gap between narrative and reported results is what makes this release worth close attention.
Analysts are looking for a loss of $0.65 per share on revenue of about $46.0 million. That would be roughly a 15% revenue decline from the $54.3 million reported a year ago and a loss about 44% deeper than last year's $0.45 per share. The sequential comparison looks even starker against the second quarter's $58.9 million in revenue and $0.08 profit, but that quarter was flattered by a $10 million Ajax milestone and a roughly $48.9 million other-income gain tied to Lilly's acquisition of Ajax. Strip those out and the swing to a loss is less dramatic than it appears. Management has not offered quarterly guidance, so the real yardsticks are the full-year targets: contract value of $218 million to $228 million, implying 10% to 15% growth, and drug discovery revenue of $65 million to $75 million, which was raised last quarter from $55 million to $65 million.
The biggest reason reported revenue can shrink while the business improves is the accelerated move to hosted software. Hosted deals recognize revenue over time rather than upfront, and management estimated each one-point increase in hosted mix trims reported revenue by about $2 million to $3 million. Hosted jumped to 47% of software revenue last quarter from 34% the quarter before. If that mix climbs again, a soft top line could actually confirm the strategy rather than undermine it. The cost is visible in gross margin, which slipped to 71% in software from 76% a year earlier. Further compression is expected, but a sharp drop without matching growth in contract value would raise questions about whether the transition is buying durable revenue or simply deferring it.
That makes contract value the number that matters most. Growth accelerated to 27% in the second quarter from 12% in the first, and management called it broad-based across large pharma, biotech and materials science. Even so, the full-year target was reaffirmed rather than raised, and more than half of annual contract value typically lands in the fourth quarter. A third quarter that sustains double-digit growth, plus confident commentary on the year-end renewal season, would validate the recovery thesis. Investors should also look for evidence that Bunsen is expanding beyond BMS, that Predictive Toxicology is growing its contribution after moving out of beta, and that operating expenses, down 6% year over year last quarter, stay disciplined as Gates Foundation contribution revenue rolls off.
Expectations around the stock have shifted dramatically. Shares have climbed 42% since the last report while the S&P 500 slipped slightly, and sentiment has swung from modestly bearish heading into the prior release to overwhelmingly bullish now. At $24.50, the stock sits well above its 200-day moving average near $16.56, though it has retreated meaningfully from a post-earnings peak of $33.78. That pullback suggests some enthusiasm has already cooled, but the bar is clearly higher than it was three months ago.
Ultimately, the headline revenue and earnings figures are likely to look weak by design. The question is whether contract value growth, hosted adoption and new Bunsen traction show the recovery management described is real and broadening. If those indicators hold, a shrinking top line becomes a temporary accounting story. If they stall ahead of a heavily back-loaded fourth quarter, the rally will have gotten ahead of the evidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-21 | |
| Oct-14 | |
| Oct-14 | |
| Oct-08 | |
| Sep-17 | |
| Sep-14 | |
| Sep-09 | |
| Sep-03 | |
| Sep-01 | |
| Sep-01 | |
| Aug-14 |
