Schrodinger Beats On A Milestone-Fueled Quarter And Raises ACV Guidance, But Slower ACV Growth And Cash Burn Keep The Bar High
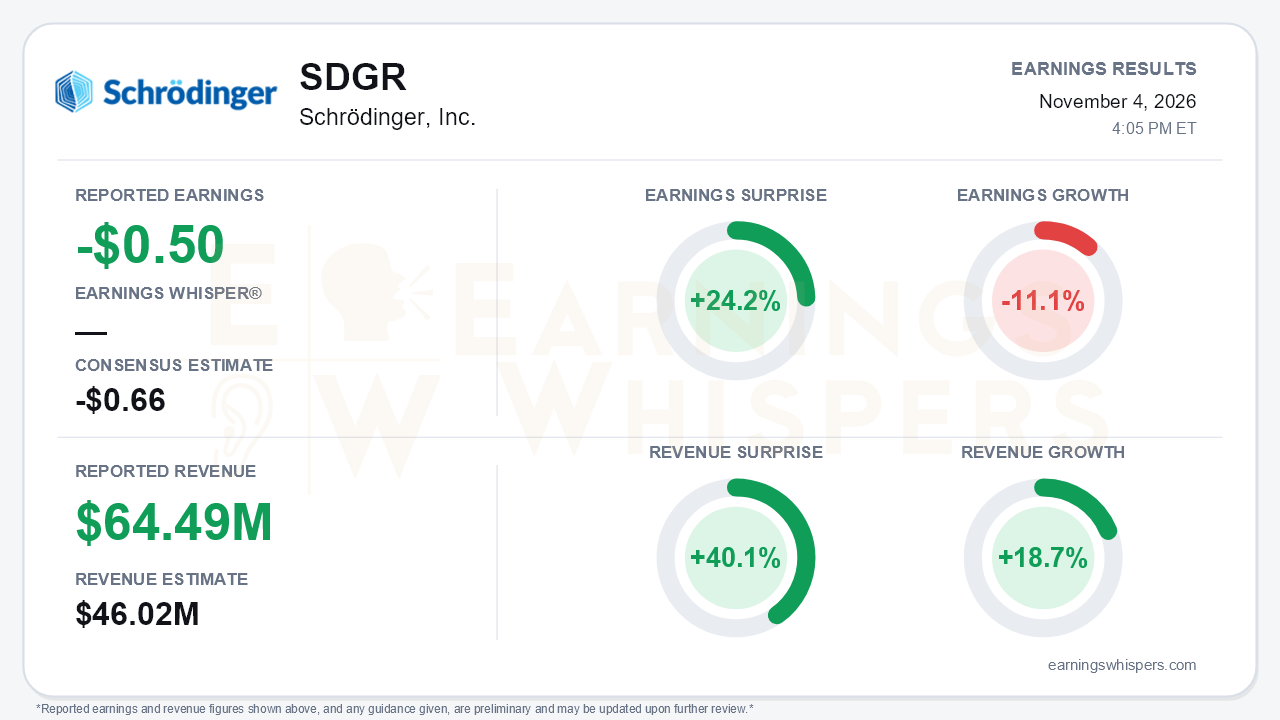
Schrödinger delivered a decisive beat for the September quarter. It reported a loss of $0.50 per share against a consensus estimate of -$0.66, a 24.2% earnings surprise. Revenue of $64.49 million topped the $46.02 million consensus by 40.1% and grew 18.7% year over year. More important for the investment case, management raised full-year 2026 ACV guidance for the first time this year, to $222-232 million (12-17% growth) from $218-228 million. It also lifted drug discovery revenue guidance for a third straight quarter, to $75-85 million. The central tension is that the beat leaned heavily on a lumpy milestone, while headline ACV growth slowed sharply from the prior quarter. The setup is better, but it is not cleaner.
The quality of the beat deserves scrutiny. Drug discovery revenue nearly doubled to $24.2 million from $13.0 million, primarily because of a milestone payment from Structure Therapeutics tied to its oral amylin program. That single line explains most of the revenue upside. Management framed the underlying drug discovery baseline at roughly $50 million a year, so the raised guidance relies on milestones with limited visibility. On a per-share basis, earnings fell 11.1% year over year as the loss widened from $0.45. That headline obscures a genuine operating improvement. Operating loss shrank to $26.1 million from $45.9 million, operating expenses fell 13% to $64.4 million, and adjusted EBITDA loss was halved to $16.8 million. The wider GAAP loss came from a $14.8 million mark-to-market loss on equity investments, compared with a $9.7 million gain a year earlier. Below the operating line, the noise worked against the company.
The software story is where the hosted-license transition shows up. Hosted revenue jumped 49% to $17.2 million and reached 45% of software revenue. Reported software revenue rose only 6% to $38.2 million. The source materials conflict on the prior-year comparison: the call analysis cites $40.9 million for the year-ago quarter, implying a decline, while the release shows $35.9 million. The release's figure reflects the newly reclassified presentation that separates contribution revenue. Either way, the ratable shift is temporarily depressing reported software revenue. Software gross margin of 75% sat below last year's 77%, but it has recovered sequentially from 69% in Q1 and 71% in Q2.
ACV is the metric to watch, and it sent mixed signals:
- **Results:** Q3 ACV of $44.7 million rose 17%, or 24% excluding contribution. That landed at the top of the prior $41-45 million guide.
- **Deceleration:** headline growth slowed from 27% in Q2, partly because contribution ACV declined.
- **Trailing trend:** trailing four-quarter ACV climbed steadily from $201 million to $208 million to $214 million.
- **Demand tone:** management's commentary is markedly better than a year ago, when software guidance was cut on pharma scale-up delays and biotech weakness. Management now says biotech funding stress has largely disappeared, and both top-20 pharma and materials science are growing.
- **Execution risk:** Q4 typically accounts for more than half of annual ACV, so the raised range still depends on year-end closes.
The catalyst slate broadened meaningfully:
- **Pipeline:** SGR-1505 data will be presented orally at ASH in December, and Takeda's zasocitinib, which Schrödinger co-invented, is under FDA Priority Review.
- **New company:** the co-founded Tectora Therapeutics raised $55 million and took two internal immunology programs. Schrödinger retains equity, milestones and royalties.
- **Platform:** management highlighted its Bunsen platform, which now runs about 80% of internal high-throughput calculations, and an expanded 80-target predictive tox panel already contributing to ACV.
Bears have legitimate ammunition here. There is no disclosure on Bunsen pricing. Cash and securities fell to $373 million from $419 million in Q2. Nine-month operating cash flow was an outflow of $96.5 million.
Investor expectations shifted dramatically heading into the report. Earnings Whispers sentiment swung from -0.16 after the prior report to +0.78, a genuinely large move from mildly negative to strongly positive. The stock tells the same story. Shares closed at $27.18 on November 3, up 57.5% from the $17.26 open after the August report and 61.3% above the 200-day moving average. They also entered earnings 19.5% below the 52-week high of $33.78 set on October 6. Most of the post-August rally held, but some enthusiasm had already been taken out. Price, momentum and AVWAP trend readings are positive, while sequential growth remains negative. That mirrors the slowdown in headline ACV.
Earnings Whispers also flagged that Schrödinger's outlook implies revenue below estimates. The company guides ACV and drug discovery revenue rather than total revenue. That caveat matters for a stock priced for continued upside. Raised segment guidance and street revenue expectations may not line up neatly, especially with software revenue still muted by the hosted transition.
The bottom line is that Schrödinger delivered the guidance raise and demand commentary that turnaround skeptics were not positioned for six months ago. Opex discipline is visibly narrowing operating losses. However, the revenue beat was milestone-driven, headline ACV growth decelerated, and cash continues to decline. With sentiment now strongly positive and shares far above long-term trend, the Q4 ACV close will determine whether the narrative has truly caught up with the stock.
Read our earnings preview for Schrödinger, Inc.: https://www.earningswhispers.com/article/SDGR/21933
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 8 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-21 | |
| Oct-14 | |
| Oct-14 | |
| Oct-08 | |
| Sep-17 | |
| Sep-14 | |
| Sep-09 | |
| Sep-03 |
