STAAR's China EvoPlus Ramp Faces Supply Test As Messy Comparison Masks Underlying Growth
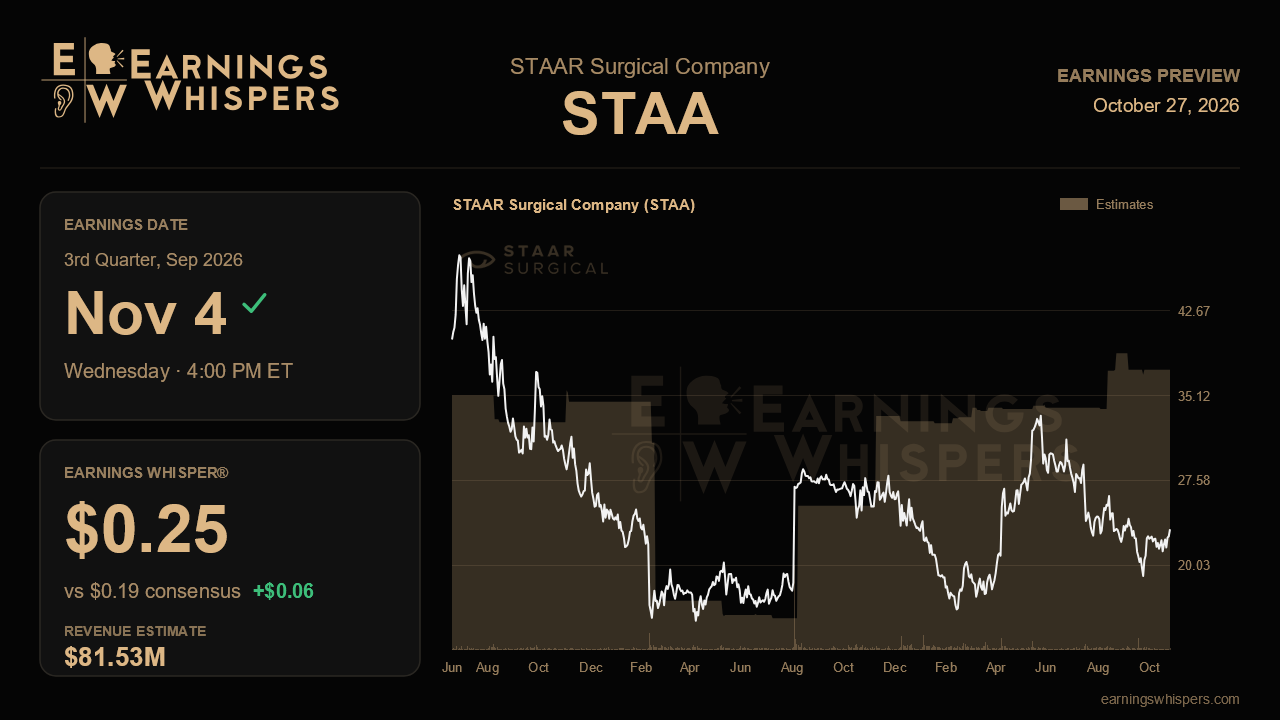
The headline number in STAAR Surgical's fiscal third-quarter report will almost certainly show a decline, and that is the least interesting thing about it. A year ago the company booked a one-time $25.9 million order in the same period, which flatters the comparison base. The real question when results arrive after the close on November 4 is whether the China-driven recovery management described last quarter is still gaining ground, or whether supply limits have started to cap it.
Wall Street expects non-GAAP earnings of $0.19 per share on revenue of about $81.5 million, a 13.9% drop from the $94.7 million reported a year earlier. Strip out that one-time order and the clean base was roughly $68.8 million, so consensus actually implies underlying growth in the high teens. The sharper concern is sequential. Revenue reached $93.5 million last quarter with earnings of $0.23 per share, so analysts are modeling a step-down of about $12 million. The Earnings Whisper of $0.25 sits well above consensus, and above last quarter's result, signaling that more optimistic investors suspect the Street is being too conservative. Management still offers no formal guidance, which leaves estimates anchored to the narrative rather than a stated range.
That narrative leans heavily on China. Net sales there climbed to $52.3 million last quarter, up 10% sequentially, and the newer EvoPlus lens ended the period at roughly a third of China units, ahead of the cautious early-demand framing management used in the two prior calls. Executives said demand had outstripped their ability to supply it and saw no inventory buildup at distributors or hospitals, which matters because it suggests sales reflect real procedures rather than channel stuffing. Validation this quarter would mean China revenue holding near or above that level with EvoPlus penetration rising further. A meaningful sequential drop in China, especially one blamed on supply, would challenge the idea that the ramp is demand-led and sustainable, particularly since the broader Chinese refractive market is only growing at a mid-single-digit pace.
Margins and cash are the second test. Gross margin improved to 74.5% last quarter, but tariffs on US-made product shipped to China will weigh on it until production moves fully to Switzerland by the end of 2026. Holding margins near that level despite tariffs would reinforce the profitability story, which went from roughly breakeven two quarters ago to $8.1 million of net income. Management also set a target of well over $200 million in cash by year-end, up from $181.5 million, so progress toward that figure is a useful check on execution. Outside China, the picture softened: US sales slipped sequentially on backorders for made-to-order lenses, Japan's growth was eroded by currency, and EMEA dipped on Middle East disruption. Any sign those constraints are easing would broaden the recovery beyond a single market.
Sentiment has improved noticeably, with bullish readings nearly doubling from last quarter, yet the stock has not followed. Shares are down 3.5% since the last report, trailing the S&P 500 by a little over two points, and sit just below the 200-day moving average in the upper half of a post-earnings range between about $19 and $26. That range is far narrower and lower than the prior quarter's, suggesting the market wants proof before paying up for the turnaround.
Ultimately, this report hinges on whether STAAR can show that China's EvoPlus momentum survived the supply bottleneck. If China holds firm and margins absorb the tariff pressure, the whisper number looks reasonable and the shift from stabilization to execution remains intact. If supply forces a visible stall, the year-over-year decline will stop looking like an accounting quirk and start looking like a ceiling.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-08 | |
| Sep-29 | |
| Sep-24 | |
| Sep-24 | |
| Sep-11 | |
| Sep-10 | |
| Sep-08 | |
| Sep-02 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 |
