STAAR Surgical Beats On Demand, But Margin Slide And Supply Limits Complicate The Story
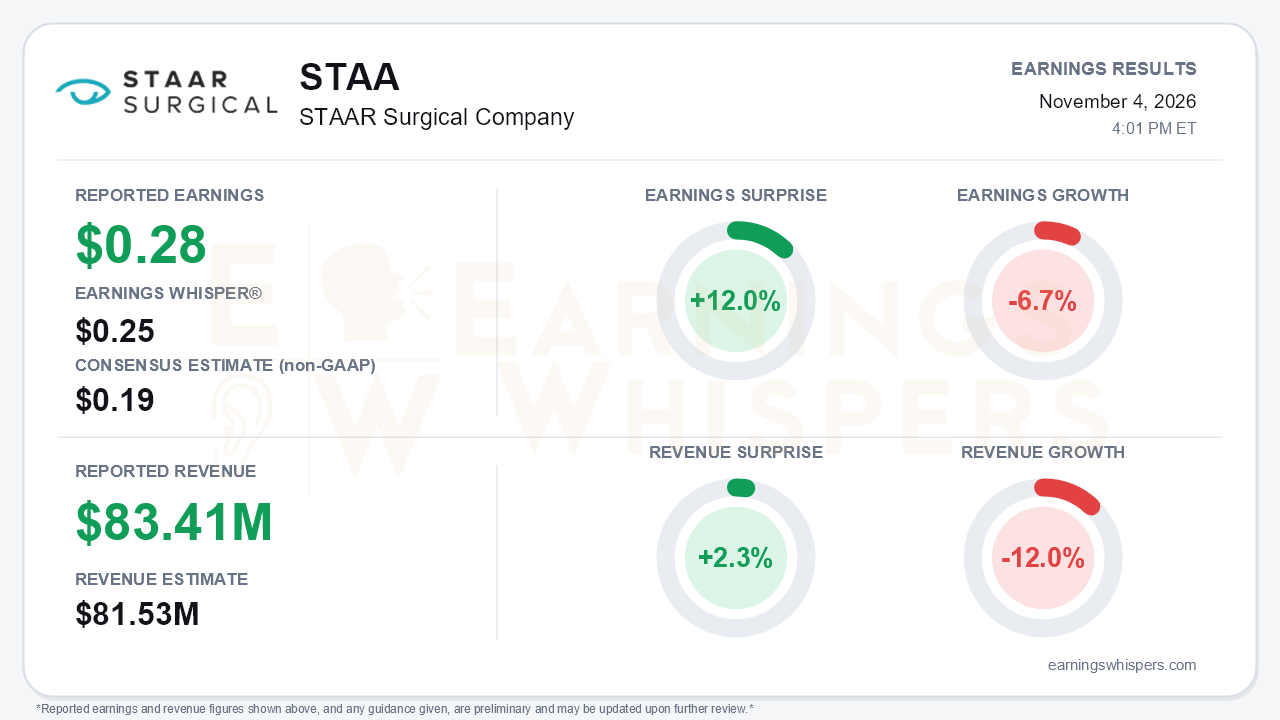
STAAR Surgical (NASDAQ: STAA) reported third-quarter earnings of $0.28 per share, measured as adjusted EBITDA per diluted share. That beat the $0.19 consensus and the $0.25 Earnings Whisper number, a 12.0% surprise. Revenue of $83.41 million topped the $81.53 million consensus by 2.3%. On a reported basis, earnings fell 6.7% year over year and revenue fell 12.0%. That decline is distorted by $25.9 million of previously deferred China sales that STAAR recognized in the year-ago quarter at a 100% gross margin. Excluding that item, net sales rose 21% against a $68.8 million base. The central tension is that demand is clearly accelerating while profitability is moving the other way. STAAR is selling more value per lens but making less money on each dollar of sales.
The quality of the beat deserves scrutiny. GAAP net income was $5.6 million, or $0.11 per share, down from $8.1 million in the second quarter. Adjusted EBITDA has now fallen for two straight quarters, from $24.4 million in Q1 to $20.0 million in Q2 and $14.4 million in Q3. Gross margin dropped to 70.9% from 74.5% in Q2 and 73.6% in Q1. Management cited several drivers:
- higher unit costs from depressed Q2 production during the ERP implementation;
- higher freight costs;
- tariffs on U.S.-made lenses shipped to China;
- larger provisions for expiring inventory.
Management calls these pressures temporary. Still, the earlier aspiration to exit the year near 75% has been reframed to a softer goal: Q4 margin above Q3, with real unit-cost improvement pushed into 2027. Cash flow was the bright spot. Free cash flow reached $26.4 million, helped by a $12.1 million reduction in receivables, and cash and investments rose to $206.4 million with no debt.
Beneath the headline, the commercial story improved meaningfully.
- **China:** Sales of $39.3 million rose 31% excluding the deferred revenue. Distributor in-market unit growth reached 12.4% year to date, versus mid-single digits in 2025. Channel inventory is now below the six-month target, so shipments should track underlying demand more closely.
- **Outside China:** Growth accelerated to 13% from 6% in each of the first two quarters. EMEA rose 31%, or 51% excluding the Middle East. The Americas grew 14%, and U.S. sales topped $6 million for a third straight quarter even as U.S. laser vision correction procedures fell 5.8%.
That is the strongest evidence yet for management's laser-to-lens thesis.
Bears have legitimate ammunition. All of China's growth this quarter came from higher average selling prices, driven by EVO+ and toric mix, because STAAR could not fully meet lens demand. In Q2, management had expected supply to catch up by the end of Q3. Instead, manufacturing yields remain below historical levels after the ERP transition. Mix-driven pricing is a genuine tailwind, but a quarter with no China volume growth leaves the durability of unit expansion as an open question until capacity catches up. Other soft spots:
- APAC outside China slowed to 4% growth, hurt by weakness in South Korea and currency pressure in Japan.
- STAAR still offers no formal guidance.
- Management flagged a seasonal sequential decline in China in Q4.
The forward catalysts are more tangible than a quarter ago.
- **Pipeline:** First-in-human trials for two Collamer-based presbyopia lenses are expected to begin enrollment within months, pending remaining regulatory authorizations.
- **Leadership:** The bench was rebuilt, including a new CTO and the return of former CEO David Bailey as Chief Commercial Officer.
- **Tariff exposure:** All China-bound manufacturing has moved to Switzerland, supported by a newly certified second clean room.
- **Capital return:** The board authorized a $50 million buyback, explicitly citing undervaluation.
- **Label expansion:** The U.S. eligibility age rose to 60 and Brazil's minimum prescription dropped, adding to the addressable market.
Investors appear to be leaning into that narrative. Earnings Whispers sentiment rose from 0.15 to 0.40, a substantial move from barely positive to solidly positive. Shares stood at $27.17 at the report date, up 12.8% from the $24.08 open after the August report and about 15% above the 200-day moving average of $23.66. The stock therefore entered the report having already rewarded the growth story. That raises the bar for a quarter whose profit trajectory is still heading lower.
The bottom line is that STAAR delivered a quarter in which demand, regional breadth, cash generation, and pipeline progress all improved, while gross margin, EBITDA, and supply execution deteriorated. The beat is real, but it rests on top-line momentum rather than operating leverage. The next leg of the story depends on management delivering the promised Q4 margin recovery and closing the gap between China demand and manufacturing capacity.
Read our earnings preview for STAAR Surgical Company: https://www.earningswhispers.com/article/STAA/21943
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-08 | |
| Sep-29 | |
| Sep-24 | |
| Sep-24 | |
| Sep-11 | |
| Sep-10 | |
| Sep-08 |
