SiTime's Renesas Deal Faces Its First Full-Quarter Test As Stock Slumps Toward Lows
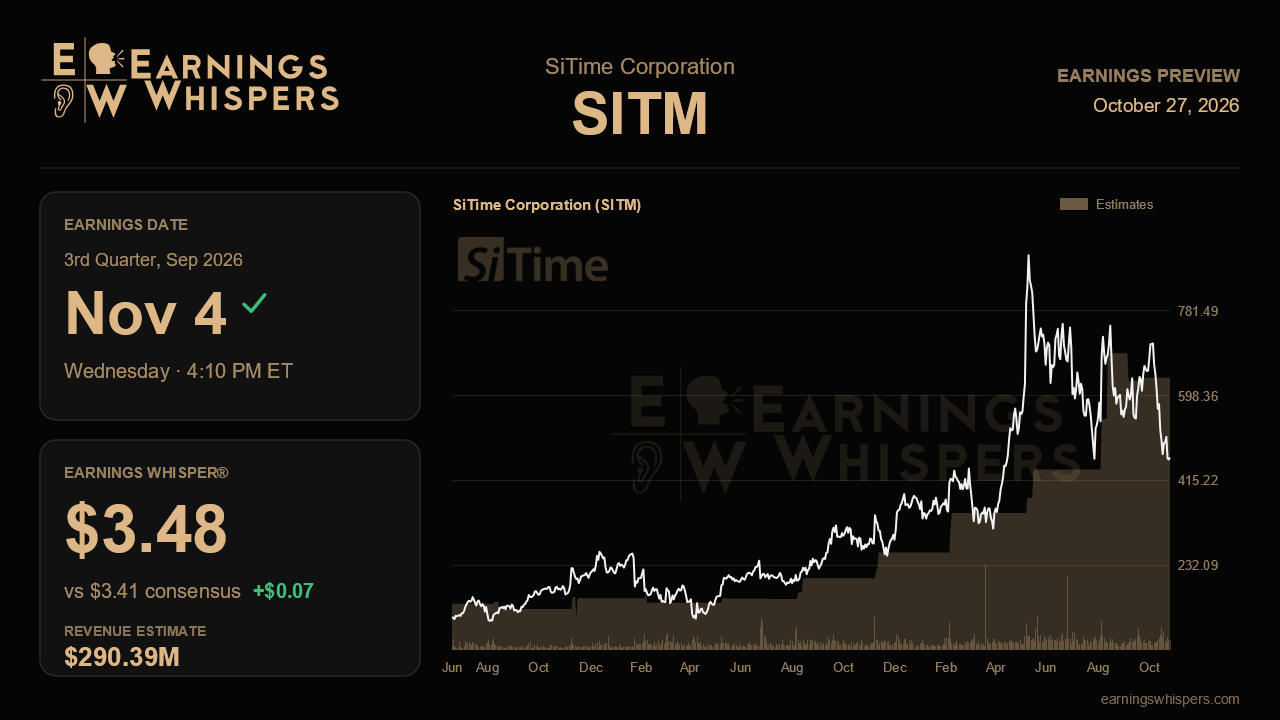
SiTime heads into its third-quarter report with an unusual disconnect. On its last call, management delivered the strongest numbers in the company's history, closed the transformational Renesas timing acquisition ahead of schedule and guided to another step change. Since then, the stock has dropped about 32% while the S&P 500 has been roughly flat. The November 4 report, due after the close, is the first quarter to include the acquired timing business, now called TPD. It should show whether that pessimism reflects real cracks in the story or simply nerves about a stock that had run very far, very fast.
The Street is looking for non-GAAP earnings of $3.41 a share on revenue of about $290.4 million. That revenue figure sits right in the middle of management's combined guidance of $285 million to $295 million and implies growth of roughly 248% from the $83.6 million reported a year ago. The more telling detail is on earnings. Management guided to $3.50 to $3.65 a share, yet consensus sits below the bottom of that range. The whisper number of $3.48 is a bit higher, but it is still short of the guided low end. That suggests some analysts are building in a cushion, possibly for integration costs or the loss of the roughly $12.2 million in interest income that boosted the second quarter before the convertible proceeds went toward the deal. If SiTime simply delivers what it promised, it would clear the bar by a comfortable margin.
The composition of revenue matters as much as the total. Management guided the legacy SiTime business to $200 million to $210 million, a 30% sequential jump on top of a quarter that had already grown 39%. TPD was expected to add about $85 million, well ahead of the original pace of about $300 million over 12 months. Investors should check both pieces separately. A strong headline number propped up by TPD while the core business falls short of its range would undercut the organic story. That story has been driven by the communications, enterprise and datacenter segment, which crossed $100 million last quarter after nine straight quarters of triple-digit growth. Fresh evidence on 1.6T optical modules, rack-level synchronization wins and new AI datacenter customers beyond the big hyperscalers would support management's growing confidence about 2027.
Margins are the other pillar. Gross margin has risen every quarter for a year, reaching 67.1%, and management guided to about 68% even after folding in TPD, which carries gross margins near 70%. Hitting that target would show the acquisition is adding to profitability rather than diluting it. On the risk side, TPD still relies on Renesas transition agreements for manufacturing and test, and customers have flagged supply constraints in that business. Any sign those bottlenecks are limiting shipments or squeezing margins would be the clearest challenge to the bullish case. Cash conversion is also worth a look after days sales outstanding rose to 51, along with whether free cash flow builds on last quarter's $27.1 million.
Sentiment has warmed modestly, to 11.2% bullish from 2% heading into the prior report, but the chart tells a gloomier story. At $464.70, shares trade well below the 200-day moving average of $543.38 and only about 4% above the post-earnings low of $445.10, far from the $762.65 peak reached after the last report. In other words, the market is already pricing in a fair amount of doubt.
The central question is whether the acquisition can perform as advertised while the core business keeps accelerating. If SiTime lands near the top of its guidance, holds margins around 68% and reports no worsening in TPD supply, the recent selloff will look like a gap between the share price and the fundamentals. If integration friction or a softer organic number shows up, it will look like the market was early rather than wrong.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-15 | |
| Oct-07 | |
| Sep-23 | |
| Sep-17 | |
| Sep-02 | |
| Aug-22 | |
| Aug-20 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 |
