SiTime Crushes Estimates And Lifts Margin Framing, But The TPD-Fueled Blowout Meets A Stock Down 35% Since Its Last Report
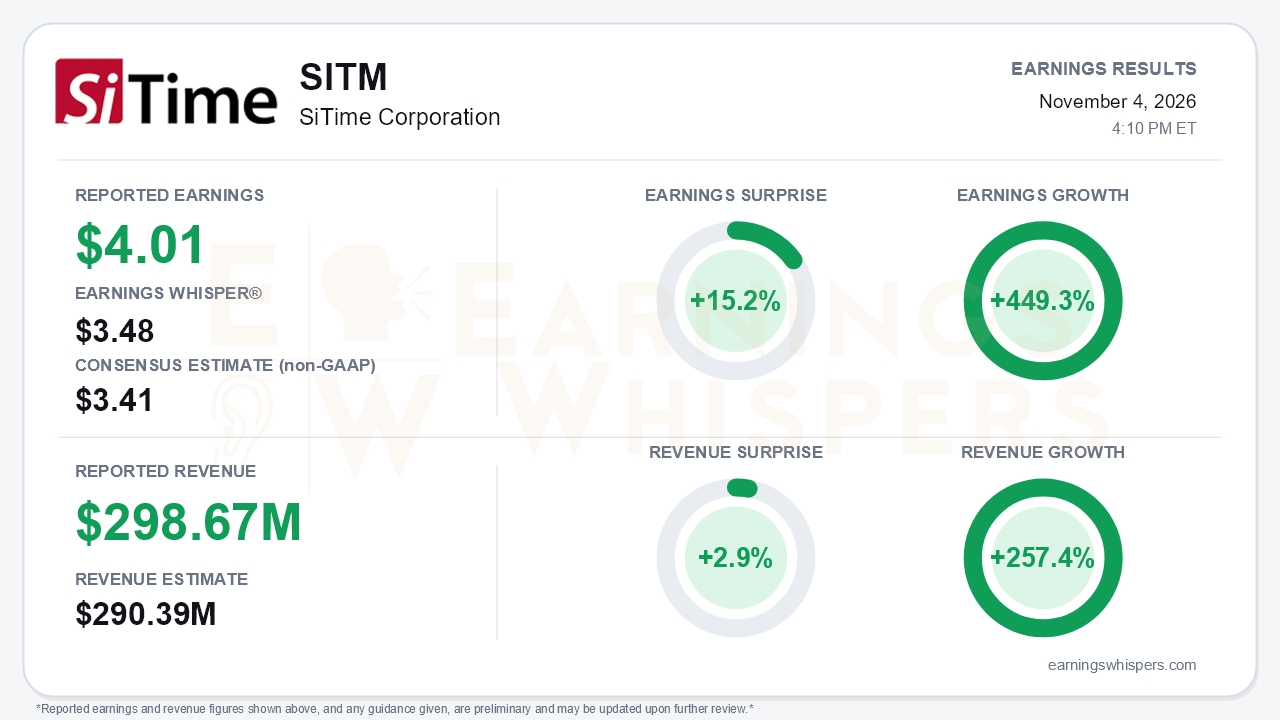
SiTime delivered the kind of quarter that usually ends debates. Non-GAAP earnings of $4.01 per share beat the $3.41 consensus by 15.2% and cleared the $3.48 Earnings Whisper number by a wide margin. Revenue of $298.67 million topped the $290.39 million consensus by 2.9%. Earnings grew 449.3% year over year on revenue growth of 257.4%, and the company beat its own guidance on every major line.
The central tension is that this fundamental surge arrived with the stock sitting near the bottom of its post-August range. Shares are down 35% since the open following the prior report.
The quality of the beat deserves some scrutiny, mainly because the TPD acquisition now dominates the reported numbers. TPD contributed $86.3 million, slightly above its roughly $85 million guide. Even so, the organic story is formidable. Core SiTime revenue excluding TPD was $212.4 million, up 154% and above the $200-210 million guide. Core CED revenue grew 202%, its fourth straight quarter of acceleration after 158% in Q1 and 181% in Q2.
Non-GAAP gross margin reached 70.7%, up from 67.1% in Q2 and 64.5% in Q1. Non-GAAP operating margin climbed to 43.4% from 34.0% one quarter earlier.
GAAP results tell a far thinner story. GAAP net income was just $4.4 million, or $0.14 per diluted share, down from $0.66 in Q2. GAAP gross margin fell to 51.6% from 63.0% as $61.8 million of intangible amortization, $21.3 million of acquisition costs and $35.0 million of stock compensation absorbed nearly all of the operating leverage. Those charges are largely deal-related and non-cash. Still, the gap between a $4.01 headline and a $0.14 GAAP print is one investors should not ignore. Diluted non-GAAP share count also rose to 32.5 million from 28.1 million.
The call strengthened the growth narrative rather than merely defending it. Acceleration was broad:
- **MIC:** Revenue grew 133%, after 85% in Q2 and a 1% decline in Q1. The large consumer customer contributed $42.7 million, up from $22.8 million.
- **AID:** Revenue rose 76%, up from 51%.
Management guided Q4 revenue to $331-341 million, with both core SiTime and TPD growing sequentially, and non-GAAP EPS to about $4.76. More notably, it reset its structural targets. Gross margin is now expected to hold around 70%, plus or minus one point, against a 60-65% long-term target set as recently as February. Management now frames a roughly 40% operating margin as sustainable, up from its earlier above-30% framing.
Demand indicators supported those targets. Book-to-bill improved from Q2, and the total funnel reached $10 billion, quadruple its 2025 level. A new semiconductor-company sales effort expanded that segment's funnel eightfold to more than $4 billion, though that business ramps in 2028-29. Management also said 2027 forecasts at its largest accounts are up 2-5x on TPD cross-selling. It cited optics design wins carrying 2-3x content uplift, along with AI smart-glasses designs ramping in 2027.
Bears still have legitimate ammunition:
- **Cash flow:** Operating cash flow swung to a $6.6 million outflow from a $40 million inflow in Q2. Days sales outstanding rose to 61 from 51, and inventory climbed to $112 million.
- **Balance sheet:** Cash has fallen to $324 million from $789 million in Q1, against about $1.35 billion of convertible notes. Q4 interest income is guided down to $2-2.5 million.
- **Supply and costs:** TPD wafer constraints are now expected to persist through 2027, with continued reliance on Renesas transition services. Operating expenses will rise sequentially through 2027 to build out TPD infrastructure.
- **Concentration:** Exposure to one large consumer customer and to AI data-center spending remains a real risk.
The market setup is more complicated than the surprise implies. Investor sentiment improved meaningfully into the report, rising from essentially neutral at 0.02 to 0.16. That is more constructive but hardly euphoric. Price action has been far harsher. Shares peaked at $762.65 on August 7, just after the last report, then slid to an inter-earnings low of $414.82 on November 2. They entered this release at $444.88, about 7% above that low, 42% below the high and nearly 19% under the 200-day moving average.
The Earnings Whispers trend signals reflect that split. Sequential growth and momentum readings are positive, while price trend and AVWAP remain negative. The three-for-one stock split announced alongside results is cosmetic but signals management confidence.
The bottom line is that SiTime's operating story has rarely looked stronger. Organic growth is accelerating, margins have structurally reset higher, guidance points up again, and the company is now running above a $1 billion annualized revenue rate. Yet the stock spent the quarter being de-rated, and the report exposed real pressure points: negative operating cash flow, a leveraged post-deal balance sheet, persistent TPD supply limits and a GAAP profit that barely registered. The fundamentals answered the growth question decisively. The cash-conversion and integration questions are what will determine whether the market's skepticism eases.
Read our earnings preview for SiTime Corporation: https://www.earningswhispers.com/article/SITM/21937
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-15 | |
| Oct-07 | |
| Sep-23 | |
| Sep-17 | |
| Sep-02 | |
| Aug-22 | |
| Aug-20 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 |
