Teknova Has Already Flagged A Record Quarter, So Margins And 2027 Targets Matter Most
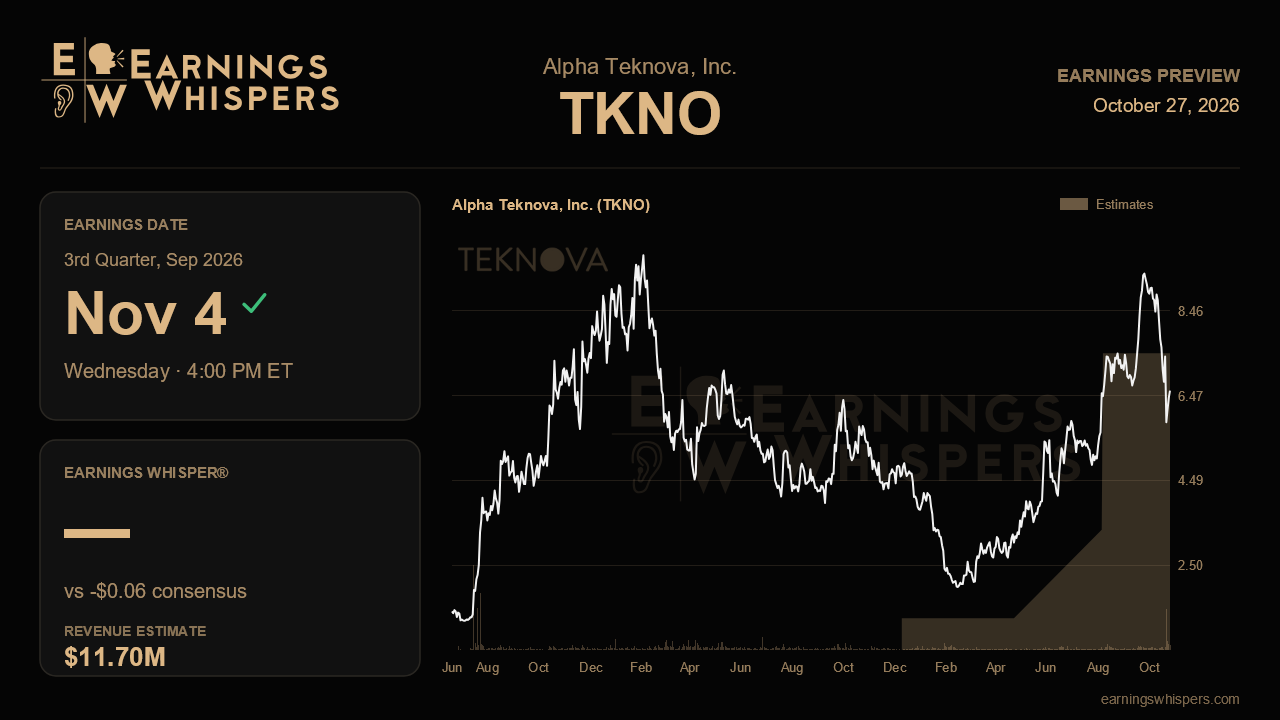
Alpha Teknova has done something unusual ahead of its third-quarter report: it has largely told the market what the top line will look like. The company guided to revenue of $12.5 million to $12.7 million, a figure that would top the record $12.2 million it posted last quarter. That shifts the focus of the November 4 release, due after the close, away from whether sales show up and toward what the revenue is worth. The real questions are gross margin, spending discipline, the health of the cell and gene therapy business, and whether management is finally willing to lift its 2027 ambitions.
The consensus looks stale. Analysts expect a loss of $0.06 per share, flat with last quarter and better than the $0.08 loss a year ago, on revenue of about $11.7 million. That revenue estimate sits below the bottom of management's range. It implies growth of roughly 12% against the $10.5 million reported a year earlier, while the guidance implies something closer to 19% to 21%. That would extend the reacceleration that took growth from 9% a year ago to 13% in the first quarter and 18% in the second. If Teknova lands inside its own range, a revenue beat against the Street is close to a formality. The market will judge whether the per-share loss also improves, given that operating expenses are slated to run at a minimum of $8 million a quarter through year-end as the company funds a bigger sales and lead-generation push.
Gross margin may be the most revealing number. Last quarter's 40.1% was a sharp improvement on the low-to-mid 30s of the prior year and the first quarter. Yet management only nudged its full-year view to the mid-to-upper 30s, which implicitly allows for some second-half giveback. A margin holding near 40% on record volume would suggest real operating leverage in the Hollister manufacturing base. A slide back toward the mid-30s would raise questions about how much of the second quarter was mix or timing. Free cash flow matters too. The company cut its full-year outflow ceiling to under $8 million after burning just $0.6 million in the second quarter, and another quarter of modest burn would reinforce that guide.
Cell and gene therapy is the test of whether the recovery is truly broad. The segment, about a quarter of 2025 revenue, was the only end market to decline last quarter, partly because one order slipped into the third quarter. That pushed order should flatter this period's results. The more useful signal is whether management describes the early-stage softness as easing, or whether the segment still drags while liquid biopsy, spatial biology, sequencing, pharma and CDMO customers carry the load. Updates on BuildTech, the AI-driven custom-order tool that is already converting catalog buyers into custom quote requests, would help show whether the commercial investments are working ahead of the early-2027 payoff management has described.
Sentiment has swung meaningfully. Readings are only mildly bearish now, compared with clearly negative positioning heading into the last report. The shares have gained about 15% since then while the S&P 500 slipped slightly. At $6.59, the stock trades well above its 200-day average of $4.81 but sits in the middle of a volatile post-earnings range that ran from $4.94 to $9.48. That suggests enthusiasm has cooled from its peak without disappearing.
With the quarter's revenue largely telegraphed, the narrative hinges on the outlook. Management kept its 2027 target in the low $50 million range and declined to bake in improving biotech funding or the payoff from its sales investments. A third consecutive increase to 2026 guidance, or any movement on 2027, would signal that the funding tailwind is arriving on schedule. A reaffirmation paired with margin slippage would leave the stock leaning on a recovery story that management itself has not yet underwritten.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-02 | |
| Sep-16 | |
| Aug-18 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 |
