Teknova's Revenue Acceleration Is Real, But The Strength Is Concentrated In Clinical Solutions While The Catalog Business Slows
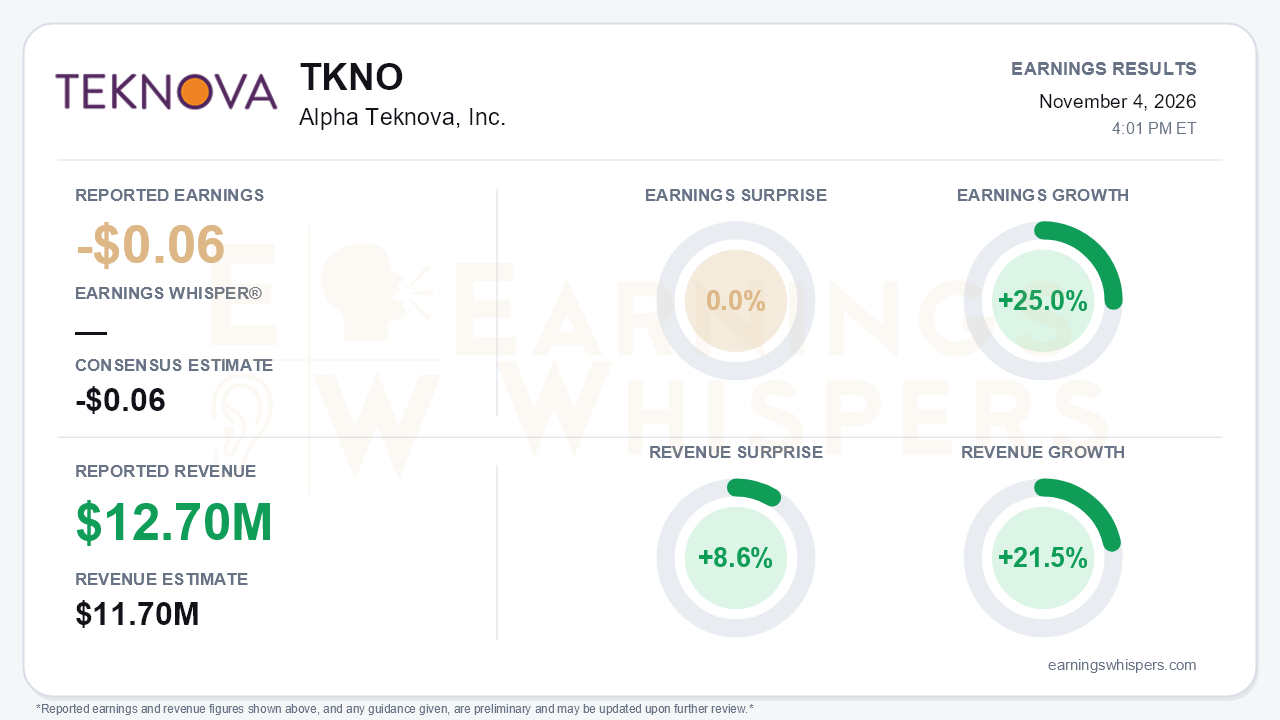
Alpha Teknova (NASDAQ: TKNO) matched the bottom-line consensus with a loss of $0.06 per share. Revenue was the more important number: $12.7 million beat the $11.7 million consensus by 8.6% and grew 21.5% year over year. Per-share earnings improved 25.0% as the net loss narrowed to $3.5 million from $4.3 million a year earlier. This was the company's second consecutive record quarter. Revenue growth has now accelerated four straight quarters, from 8% to 13% to 18% to roughly 22%, its first quarter above 20% in more than four years. Management raised full-year revenue guidance for the second quarter in a row, to $46-48 million. The central tension is that the acceleration is narrowly sourced. Beneath the top line, the larger and steadier part of the business is cooling.
The segment detail tells the story. Clinical Solutions revenue jumped 86% to $3.2 million, compared with 18% growth in Q2. Lab Essentials, which is about 70% of revenue, grew just 9% after growing 18% the prior quarter. Management also said catalog products, roughly 60% of sales, slowed to mid-single-digit growth year to date from low double digits through Q2. Small and mid-sized biotech discovery work and early-stage cell and gene therapy spending remain soft. Clinical Solutions is a business management itself describes as lumpy and early in its recovery. That makes the quarter's growth profile more fragile than the headline acceleration implies.
The quality of the margin story also deserves scrutiny. Gross margin expanded sharply to 38.0% from 30.7% a year ago. However, it slipped sequentially from 40.1% in Q2, and the company credited part of the gain to lower fixed-cost absorption tied to finished-goods inventory changes, a benefit that may not repeat. Operating expenses rose to $8.0 million, driven by sales and marketing headcount, and management expects Q4 opex of at least $8 million. On a sequential basis, profitability worsened:
- Adjusted EBITDA was negative $1.0 million, compared with negative $0.7 million in Q2.
- Free cash outflow widened to $1.4 million from $0.6 million in Q2.
Both measures still improved year over year. The full-year free cash outflow target of less than $8 million was reaffirmed, as was the target of an EBITDA-positive quarter before the end of 2027 at $52-57 million in annualized revenue.
The call did preserve a credible demand narrative. The biggest change from Q2 is that management now sees biotech funding, up about 70% over the trailing twelve months, flowing into custom biopharma orders. That is earlier than the four-quarter lag the company had previously assumed. In Q2, biopharma had been described as muted. In Q3, management cited a broad uptick across cell and gene therapy, monoclonal antibodies, oligos and specialty CDMOs. Other operating indicators were supportive:
- Custom line items rose about 30% year to date, and the customer base grew about 10%.
- The newly launched Fill-Tek dispensing system is drawing quotes, more than 60% of them for GMP-grade orders.
- The AI-driven configurator has generated more than 140 quote requests from over 100 organizations.
- Management expects at least one supported therapy to reach commercialization by the end of 2027.
The guidance raise is less aggressive than it looks. Year-to-date revenue of about $36.0 million implies Q4 revenue of roughly $10-12 million, below Q3's $12.7 million at the midpoint. Earnings Whispers characterizes the outlook as in line, which suggests the Street had largely anticipated the increase. Management also declined to offer 2027 guidance, after citing a low-$50 million target in Q2. That leaves investors without confirmation of the revenue level the breakeven framework depends on.
The October equity raise reshapes the setup. Teknova sold 9.2 million shares at $5.00 for about $42.9 million in net proceeds. That fixes a balance sheet that held just $16.6 million in cash and investments against $13.2 million of borrowings at quarter end. It also adds meaningful dilution relative to roughly 53.7 million weighted shares. Management plans to use part of the money for tuck-in M&A in proteins, enzymes, antibodies and cytokines, which introduces integration and valuation risk.
The stock's path reflects that financing. Shares hit a 52-week high of $9.48 on September 25, then slid to an inter-earnings low of $4.94 on October 21, right as the offering priced. They rebounded to $7.34 ahead of the report, up 28.5% since the open after the Q2 release and about 49% above the 200-day moving average. Investor sentiment improved to -0.16 from -0.42. That is a meaningful shift, but expectations remain net skeptical. Earnings Whispers momentum and AVWAP trend readings are positive, consistent with the post-offering recovery.
The bottom line is that Teknova delivered a genuine top-line acceleration, a solid revenue beat and a stronger balance sheet, and management's tone has turned confident. Bears still have legitimate ammunition. The growth leaned heavily on a lumpy Clinical Solutions segment while the catalog core slowed. Margins and EBITDA softened sequentially, and the implied Q4 and missing 2027 outlook leave the breakeven timeline unproven. With the stock already well off its offering-driven low, the next leg depends on whether biopharma custom demand broadens into the catalog business rather than staying concentrated in one segment.
Read our earnings preview for Alpha Teknova, Inc.: https://www.earningswhispers.com/article/TKNO/21950
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-02 | |
| Sep-16 | |
| Aug-18 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 |
