TaskUs Faces A Higher Bar As Street Models Revenue Above Its Own Guidance
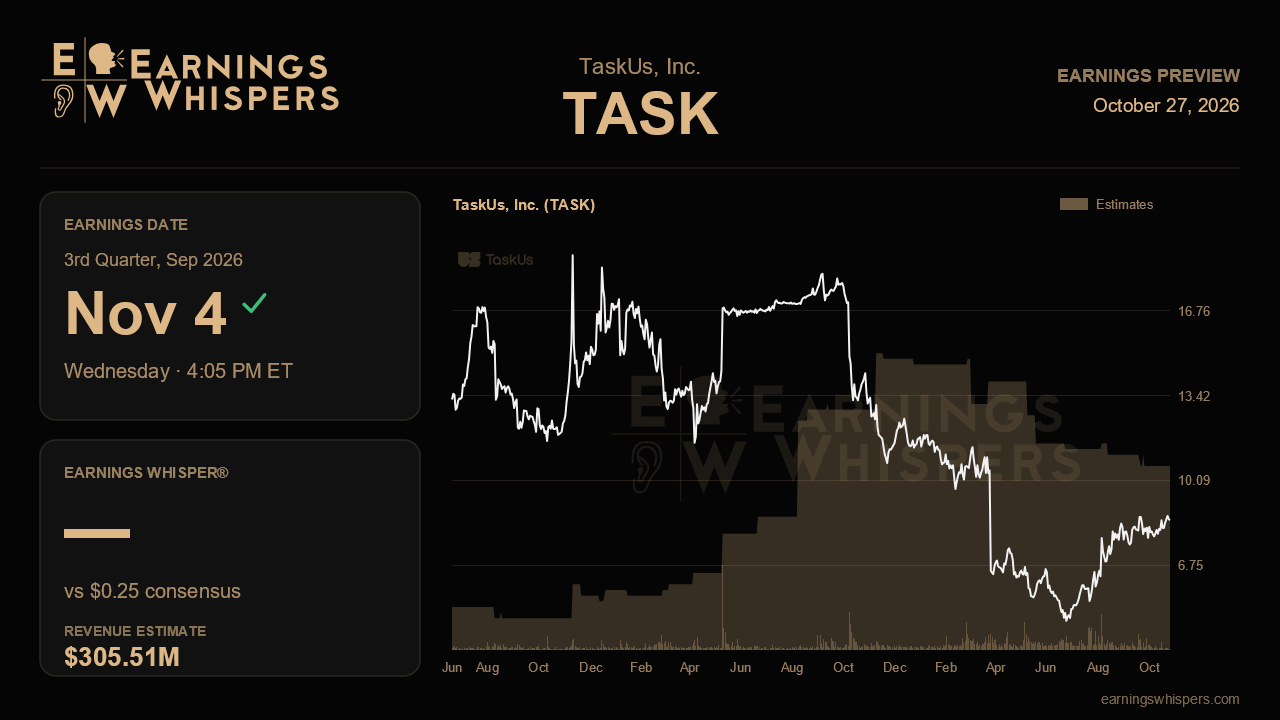
TaskUs heads into its third-quarter report with a peculiar setup: the stock has rallied hard, sentiment has soured, and Wall Street is asking for more revenue than management promised. After two straight quarters of beating and raising, the market has stopped grading the company against its guidance and started grading it against its habit of clearing it. That makes the November 4 release, due after the close, less about whether TaskUs can hit a number and more about whether its diversified growth engine can keep outrunning the shrinking business at its largest client.
Consensus calls for earnings of $0.25 per share on revenue of $305.5 million. That revenue figure implies growth of roughly 2.3% from the year-ago $298.7 million, modest but positive, while earnings are expected to fall about 31% from $0.36. Management guided the quarter to $300 million to $302 million, so analysts sit a few million dollars above the top of the range. That is not an unreasonable leap given that second-quarter revenue of $308.9 million topped the high end of guidance by nearly $11 million. Still, it means a result merely at the guided midpoint would read as a miss, and a repeat of last quarter's cushion is effectively baked in. The full-year outlook of $1.22 billion to $1.24 billion, nudged up at the low end last time, also leaves room for another raise if the quarter lands well.
The central story from the last call was a tale of two businesses. Revenue outside the top client grew about 15% in the second quarter, accelerating from roughly 13% in the first, while that top client shrank to 20% of revenue from 26% two quarters earlier as it automates work TaskUs once handled. Management warned that the headwind persists through the back half of the year and possibly into 2027, and trust and safety revenue, the segment most exposed to it, swung to a 12.3% decline. Validation this quarter would mean ex-top-client growth holding in the mid-teens and the customer experience business extending its acceleration beyond the 6.4% pace posted last quarter, particularly in the higher-value sales and lead-generation work that made up a big share of recent signings. A slip in either would undercut the claim that TaskUs is gaining share fast enough to absorb the erosion.
AI services is the other swing factor. Growth there cooled to about 26% from 36% as a social media client scaled back project work, ending a long streak above 30%. Management guided for similar growth this quarter and a return above 30% in the fourth. Hitting the near-term figure matters less than any evidence, through pipeline commentary or new project wins, that the reacceleration is on track, since that segment underpins the bull case for the company's AI positioning.
Margins are the reason earnings are expected to fall even as revenue edges higher. Management guided third-quarter adjusted margin to about 18.7%, down from roughly 21% last year, citing a heavier mix of costlier U.S. onshore delivery and deliberate investment that it said will continue into next year. Anything below that level would raise doubts about cost discipline, while comments from new chief financial officer Rishabh Gupta on when spending normalizes could shape 2027 expectations. Cash generation offers some support: free cash flow guidance was lifted to $110 million to $120 million, helped by a trimmed capital spending plan.
The stock has gained about 21% since the last report while the S&P 500 slipped, trading at $8.53, comfortably above its 200-day average and not far below its post-earnings high of $8.86. Yet bearish sentiment has deepened to 42.4% from 33.3% a quarter ago, suggesting skepticism that the rally is sustainable. Ultimately, the report hinges on one question: can the diversified core grow fast enough to deliver another beat above guidance while margins compress by design? If it can, the narrative of a company outgrowing its concentration problem stays intact. If not, the recent run leaves little room for disappointment.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Sep-28 | |
| Aug-05 | |
| Jul-21 | |
| Jun-23 | |
| Jun-22 | |
| May-06 | |
| May-06 | |
| May-05 | |
| Apr-20 | |
| Mar-10 | |
| Mar-05 | |
| Mar-02 | |
| Mar-02 |
