TaskUs Beats And Raises Again As Diversified Growth Accelerates, But Its Largest Client Is Still Eroding The Headline
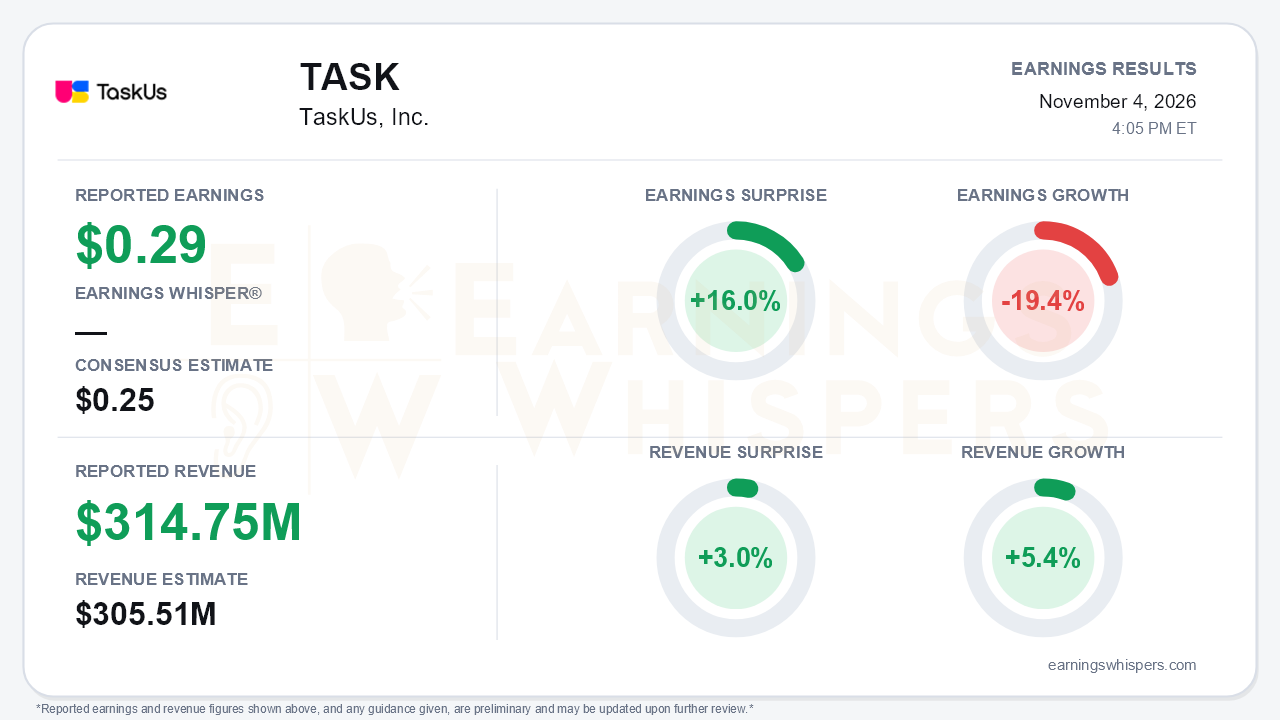
TaskUs (NASDAQ: TASK) delivered its second straight beat-and-raise in the third quarter. Underneath that result is a business split in two: a fast-diversifying growth engine, and a shrinking legacy relationship that still caps reported growth and margins. Earnings Whispers recorded EPS of $0.29, 16.0% above the $0.25 consensus, on record revenue of $314.75 million, which beat expectations by 3.0%. Earnings still fell 19.4% year over year while revenue grew 5.4%. Note that the $0.29 normalized figure differs from the company's own reporting: GAAP diluted EPS was $0.28 and adjusted EPS was $0.34, down from $0.42. On every basis, profits declined from last year even as the top line hit a new high.
The quality of the earnings decline matters. Much of the drop sits below the operating line. Financing expenses nearly doubled to $8.9 million from $4.6 million after the March refinancing, which added $500 million of debt and funded a $332.8 million special dividend. Shareholders' equity fell from about $600 million to $322 million as a result. Operating income slipped only modestly, to $36.5 million from $37.9 million, because lower SG&A offset a sharp rise in cost of services to 65.4% of revenue from 62.1%, a shift management tied to onshore AI work and pricing pressure. Adjusted EBITDA margin was 18.8%, versus 21.2% a year ago, but it has been essentially flat sequentially (19.1%, 18.7%, 18.8%). Cash flow was weaker than the year-to-date story suggests. Third-quarter free cash flow fell 47.5% to $22.0 million, with conversion of 37.3%. Nine-month adjusted free cash flow of $101.6 million is still running well ahead of last year.
The call is where the bull case lives. Excluding the largest client, growth accelerated to roughly 20%, up from about 13.5% in Q1 and 15% in Q2. The cohort of clients ranked 2 through 20 grew 37%. AI Services reaccelerated to 27.7% growth from 25.8%, topped $250 million in trailing revenue, and became the second-largest service line. Management sized autonomous-vehicle and robotics revenue at more than $100 million in 2026, over three times the 2025 level. Digital Customer Experience accelerated for a third straight quarter (5.4%, 6.4%, then 7.1%), and management guided for further acceleration. New wins include:
- remote teleoperation of a tech company's last-mile delivery robots;
- an expanded consumer-robotics partnership with a physical AI lab;
- an AI-safety engagement with a leading LLM developer;
- two agentic AI commitments from existing clients.
The drag is equally clear. The largest client fell to 17% of revenue from 24% in Q1 and 27% a year ago, and its dollar headwind has widened every quarter. Trust and safety declined 15.8%, worse than the 12.3% drop in Q2, and management expects a steeper decline in Q4 with no year-over-year growth from that client in the first half of 2027. That is why fourth-quarter revenue guidance of $319 million to $321 million implies only about 2.3% growth and came in below estimates, even as the full-year range was raised to $1.249 billion to $1.251 billion. Adjusted free cash flow guidance rose a third time, to $115 million to $125 million, helped by capex cut to about $45 million. There was also a subtle softening in tone. Management's Q4 AI Services language shifted from 'over 30%' last quarter to 'meaningfully accelerate.' Management also said AI and growth investment will 'meaningfully increase' in 2027 beyond this year's $25 million, which limits near-term margin expansion.
The forward catalyst worth watching is the largest client itself. Management said that client plans to consolidate trust and safety, CX and other volumes with TaskUs and add personal agentic AI work. It flagged possible year-over-year growth there in the second half of 2027. If that materializes, the headline drag eventually flips. Until then, top-10 client concentration has risen to 63%, and pricing competition, FX exposure and higher interest costs remain legitimate bear ammunition.
The market has leaned toward the optimists while investor sentiment has not. Shares entered the report at $8.32, up 18.2% from the $7.04 open after the August report and 7.6% above the 200-day moving average. That price was about 6% below the inter-earnings high of $8.86 set October 22 and well off the August low of $6.57. Earnings Whispers trend signals for price, momentum and sequential growth were positive heading in. Sentiment moved the other way, becoming more negative, from -0.33 to -0.41. That is a modest shift, but it shows skepticism persisting despite the rally.
The bottom line is that TaskUs is executing well where it controls the outcome. Diversified growth is accelerating, AI and robotics work is scaling, and guidance keeps moving higher. But the shrinking largest client, a heavier interest burden and a stepped-up 2027 investment cycle mean reported earnings and margins are not yet reflecting that progress. The soft Q4 growth guide keeps the tension in place for at least another few quarters.
Read our earnings preview for TaskUs, Inc.: https://www.earningswhispers.com/article/TASK/21947
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-21 | |
| Sep-28 | |
| Aug-05 | |
| Jul-21 | |
| Jun-23 | |
| Jun-22 | |
| May-06 | |
| May-06 | |
| May-05 | |
| Apr-20 |
