Mirum's Booming Rare Liver Drug Sales Face A Market Fixated On Velixibat's FDA Setback
Mirum Pharmaceuticals has a growing commercial business and a pipeline problem, and its stock is weighted toward the pipeline problem. Last quarter the company raised its sales outlook for the second time this year, widened its margins and refinanced its debt on attractive terms. It also disclosed that the FDA wants another Phase 3 study before it will accept an application for velixibat in primary sclerosing cholangitis (PSC). The shares have since fallen 7.7%, against a roughly flat S&P 500. When Mirum reports after the close on November 3, the question is whether more steady commercial execution can win back investors who have shifted their focus to regulatory risk.
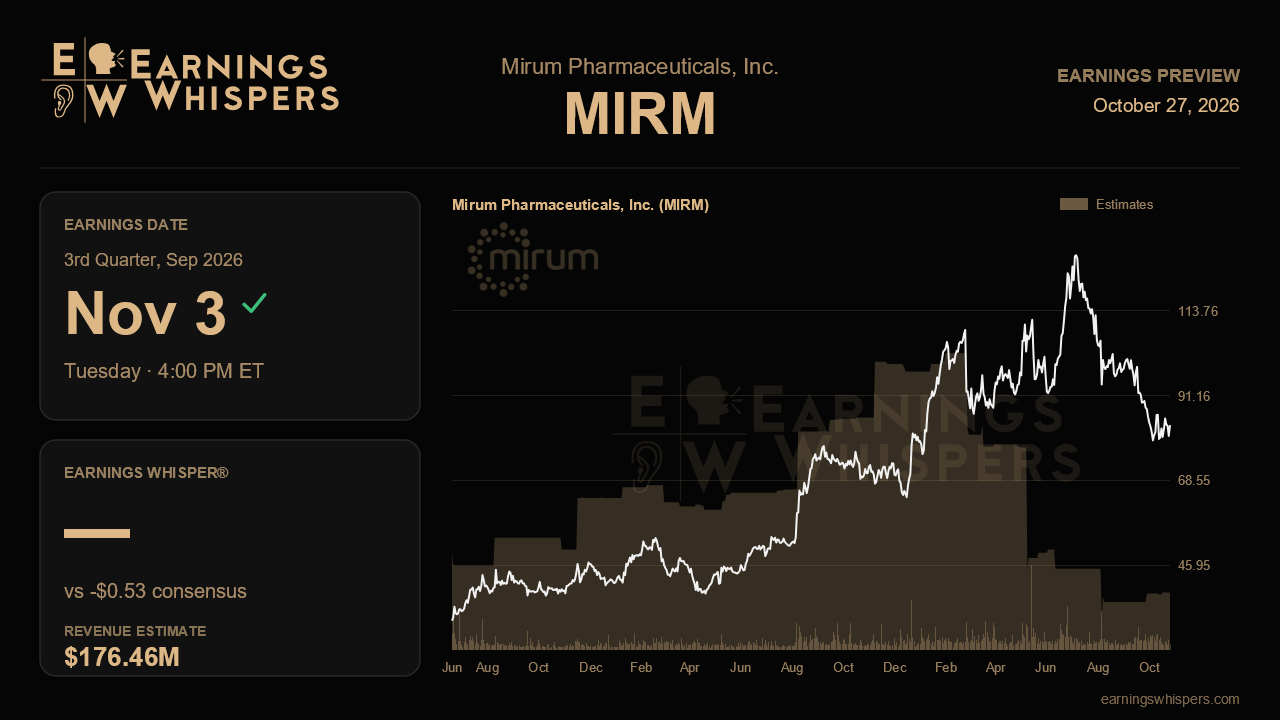
The Street expects third-quarter revenue of about $176.5 million, up roughly 33% from a year ago. That is essentially flat with the $176.2 million Mirum posted last quarter. The consensus loss is $0.53 per share, narrower than the $0.80 loss in the second quarter but well below the small profit of a year ago. The flat revenue forecast is the more telling number. Net product sales have risen every quarter through the past year, from $133 million to $149 million, then $160 million and $176 million. Management now guides to $680 million to $700 million for 2026, without any contribution from its FOP drug. After about $336 million in the first half, that range implies roughly $172 million to $182 million per quarter for the rest of the year. The full-year consensus of about $674 million still sits below the bottom of the range. Analysts appear unwilling to fully credit the latest raise, which leaves room for upside if Mirum's growth trend holds.
To confirm last quarter's story, Mirum needs a clean sequential gain in net product sales, ideally led by LivMarli. Management said demand in PFIC keeps surprising and newly estimated at least 2,000 addressable adult PFIC patients in the US. Evidence that this group is turning into prescriptions would make growth look durable rather than a one-time catch-up. Margins are the second check. The commercial cash contribution margin rose to the high 50s from the mid 50s, and holding or extending that gain would show operating leverage is building. A sequential dip in sales, or a guidance range left unchanged with soft quarterly results, would undercut the view that the base business can carry the company through the pipeline delay.
The pipeline update may matter even more. Velixibat's PSC filing has slipped to the first half of 2027, and management said it is not yet aligned with the agency on the submission package. Since then the program has received Breakthrough Therapy designation, which may give Mirum leverage in those talks. Investors will want to know whether discussions have moved toward an agreed path or whether a second Phase 3 now looks unavoidable. They will also want management to keep separating PSC from primary biliary cholangitis, where the FDA said the Vantage trial, due to read out in early 2027, could serve as a pivotal study. The report is also the first chance to hear about zolurgocertib after its September 26 PDUFA date for FOP. That decision determines whether the planned fourth-quarter launch, and a new revenue stream outside the current guidance, goes ahead.
Sentiment remains bearish, at negative 25.5% compared with negative 27.0% before the last report, so the mood has barely improved. The chart reflects the damage. At $83.27, the stock sits well below its 200-day moving average of $98.56 and in the lower part of its post-earnings range of $77.78 to $104.66. That entire range sits below the prior quarter's $90.59 to $130 band.
The low valuation helps Mirum, since the bar for a positive reaction is lower than the company's results might justify. The deciding issue is whether management can show that a fast-growing, more profitable commercial business is worth backing while the PSC timeline gets resolved. Another strong sales quarter, a firm FOP launch plan and a credible regulatory path for velixibat would support that case. Uncertainty on all three would leave the regulatory overhang in control of the stock.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-15 | |
| Oct-12 |
Mirum tees up Livmarli label expansion on Phase III liver disease study success
MIRM
Clinical Trials Arena
|
| Oct-12 | |
| Oct-12 | |
| Oct-11 | |
| Sep-30 | |
| Sep-28 | |
| Sep-28 | |
| Sep-27 | |
| Sep-25 | |
| Sep-25 |
