Mirum's Loss Widens Past Estimates As Pipeline Spending Swamps A Fourth Straight Guidance Raise
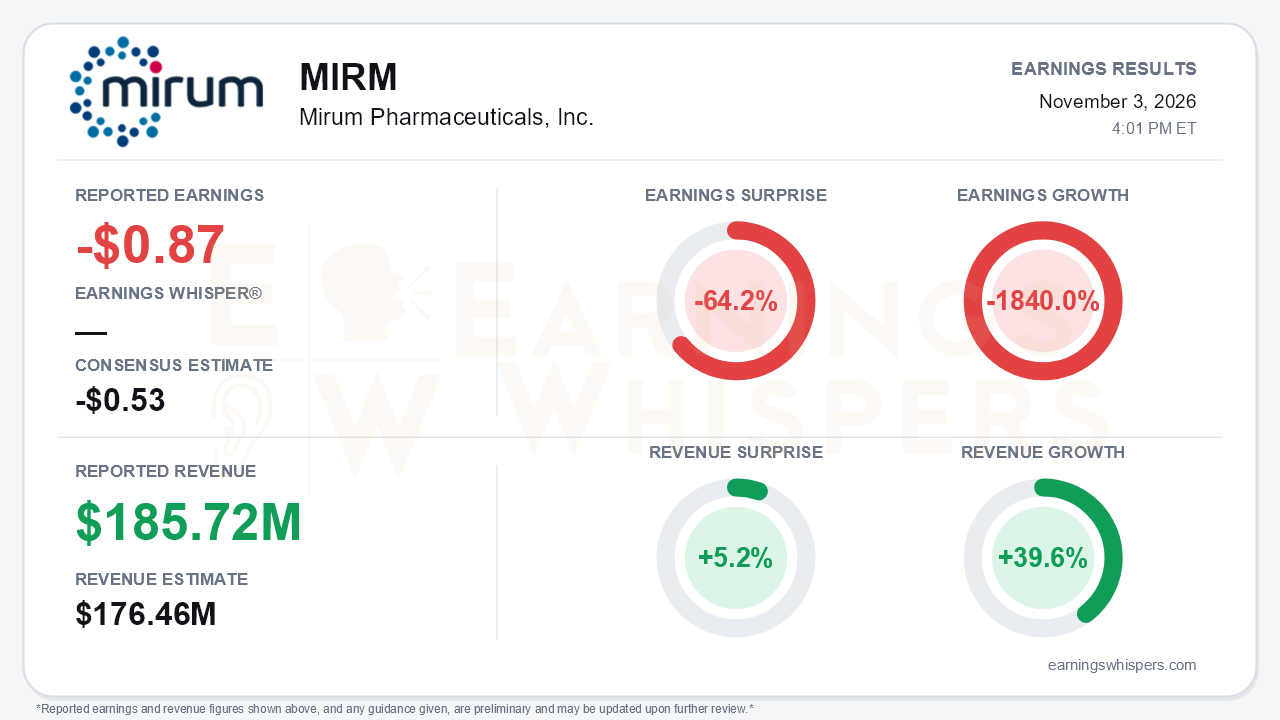
Mirum Pharmaceuticals delivered a quarter with two opposite stories. The diluted loss was $0.87 per share, 64.2% worse than the -$0.53 consensus and a reversal from a small profit a year earlier, which Earnings Whispers registers as an 1840.0% year-over-year earnings decline. Revenue of $185.72 million beat the $176.46 million consensus by 5.2% and grew 39.6%. Management also raised full-year net product sales guidance for the fourth time this year, to $715 million to $720 million. That is the central tension. The commercial engine keeps outrunning expectations, but Mirum is now spending like a company preparing for several launches at once, and the bottom line shows it.
The miss came from expenses, not demand. Total operating expenses nearly doubled to $245.5 million from $130.4 million. Reported R&D jumped to $107.9 million from $43.0 million, including $42.1 million for brelovitug, and the quarter also carried a $13.5 million IPR&D charge. Stock-based compensation rose to $33.3 million from $18.1 million. The result was a $59.7 million operating loss, versus a $2.6 million operating profit a year ago.
The per-share figures add another wrinkle. Net loss was $40.8 million, or $0.62 per basic share, but $0.87 diluted. That gap suggests the diluted calculation adjusted for convertible-note effects, likely tied to the $16.4 million of other income. Still, the release does not walk through the reconciliation, so investors should be cautious about reading the diluted figure as a clean operating comparison.
On the top line, the trend is steady but uneven. Net product sales moved from $160 million in Q1 to $176 million in Q2 and $186 million in Q3. The $10 million sequential gain was smaller than the prior quarter's $16 million and sits at the low end of the $10 million to $15 million quarterly step-ups management now projects through 2027. The brands diverged:
- LIVMARLI reached $133.4 million, up 45%, but rose only $4 million sequentially.
- U.S. LIVMARLI climbed to $100 million from $92 million, driven mainly by adult PFIC.
- Ex-U.S. LIVMARLI appears to have slipped, consistent with management's comment that Takeda/Japan orders were minimal, with none expected in Q4.
- Bile acid medicines grew 28% to $52.3 million.
- Cash contribution margin held in the high-50s percent range, up from roughly 55% in 2025.
The raised guidance implies Q4 sales of roughly $193 million to $198 million.
The call preserved a credible growth story, and the catalyst calendar is now crowded. ATEBRIOZ won FDA approval for FOP and launched in October, and management expects faster uptake than LIVMARLI saw. Three late-stage readouts all came back positive: AZURE-1 for brelovitug in HDV, EXPAND for LIVMARLI including biliary atresia, and PROGRESS Cohort 2 for pediatric ATEBRIOZ. Those results set up as many as five submissions in the first half of 2027. Brelovitug's BLA still depends on AZURE-4 data due this quarter, and management guided to cash-flow-positive operations in 2027.
Bears have legitimate ammunition, though:
- **PSC filing:** The volixibat PSC NDA, which slipped after the FDA recommended a Phase 3, remains unaligned with the agency. Management is seeking "familiarity, not necessarily complete alignment" and is presenting new IBD-subgroup analyses the FDA has not yet seen. The same liver division will review the EXPAND and PBC filings.
- **Generic exposure:** CHOLBAM is off orphan exclusivity, and the bile acid line is growing large enough to attract generics.
- **Spending:** Cash R&D rose to about $94 million, roughly half of revenue, and is expected to stay elevated for about two more quarters.
- **Cash and leverage:** Cash and investments of $500.5 million are up from $391.4 million at year-end but down from about $561 million in Q2. The release cites $20 million of 2029 notes repurchased, while the call attributes about $62 million of cash outflow to convertible repurchases, a gap the materials do not fully reconcile. Overall convertible debt sits at $731 million, and stockholders' equity has swung to a $54 million deficit after this year's heavy acquired-IPR&D charges.
Investors entered the report skeptical. Earnings Whispers sentiment improved modestly from -0.27 to -0.22 but remains negative. Shares closed at $85.74 the day before the release, down 5.0% from the open after the August report. That leaves the stock 13.0% below its 200-day moving average of $98.50 and 18.1% below its August 19 inter-earnings high of $104.66, though 10.2% above the October 6 low. The market has given back the post-August rally despite repeated guidance increases. The trend readings reflect the same split: sequential growth is positive, while price and AVWAP trends remain negative.
The bottom line is that Mirum's EPS miss reflects a deliberate surge in late-stage investment, not a crack in demand. Revenue, guidance and margins all moved higher, and the pipeline delivered a rare run of clean readouts. But the stock now depends on execution over the next two to three quarters: AZURE-4, the ATEBRIOZ launch, Q4 sales meeting the implied step-up, and a still-unresolved FDA path for PSC. Until spending eases and that regulatory overhang clears, the market appears unwilling to pay for the commercial momentum alone.
Read our earnings preview for Mirum Pharmaceuticals, Inc.: https://www.earningswhispers.com/article/MIRM/21984
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-15 | |
| Oct-12 |
Mirum tees up Livmarli label expansion on Phase III liver disease study success
MIRM
Clinical Trials Arena
|
| Oct-12 | |
| Oct-12 | |
| Oct-11 | |
| Sep-30 | |
| Sep-28 | |
| Sep-28 |
