Corcept Must Prove Its Lifioly Ramp Can Support A $1.1 Billion Guide
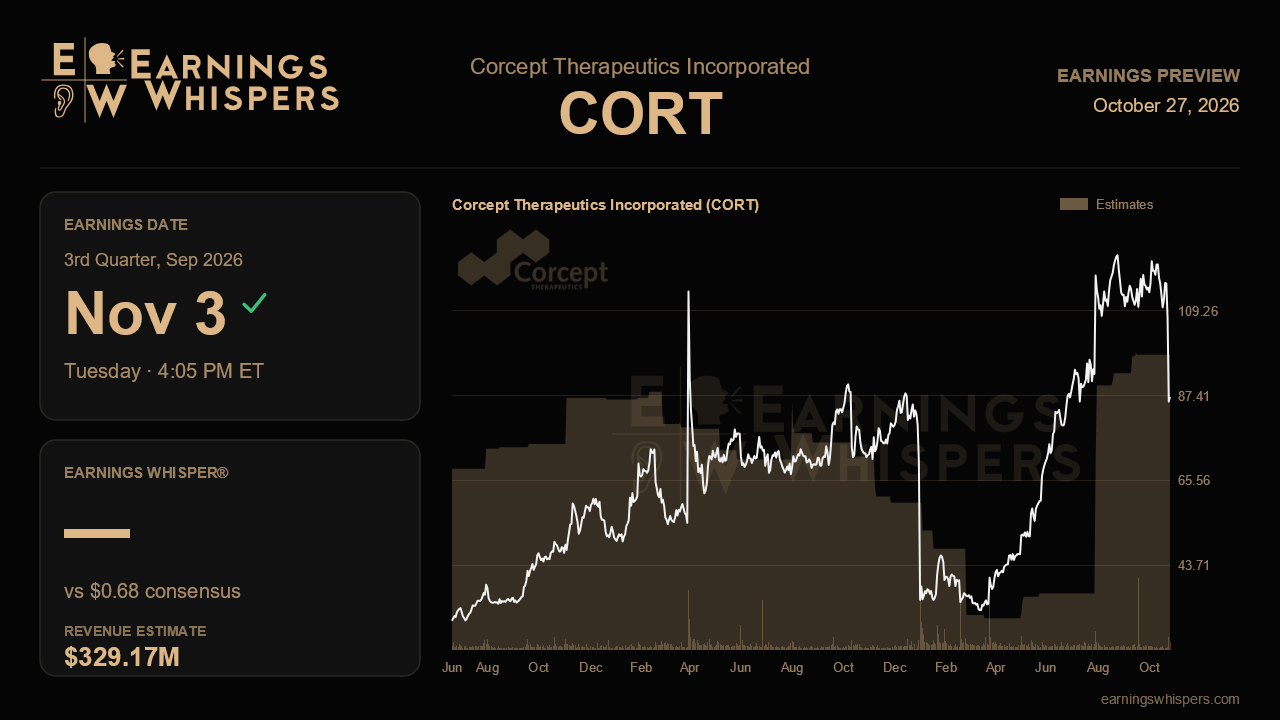
Corcept Therapeutics heads into its third-quarter report with a peculiar disconnect. Management has raised its full-year revenue outlook twice in three quarters, its new cancer drug Lifioly got off to an unusually fast start, and the pharmacy disruption that clouded much of last year is behind it. Yet the stock has fallen more than 22% since the last report while the S&P 500 gained 4%. The November 3 release, due after the close, is the first real chance to show whether the operating story deserves more credit than the market has been giving it.
The Street is looking for earnings of $0.68 per share on revenue of $329.2 million. That would mean revenue up about 58.5% from a year ago and earnings more than quadrupling from $0.16. Sequentially, it implies roughly $73 million of added revenue on top of the $256.1 million reported last quarter, a jump of nearly 29%. That is a steep climb, but it is also what the guidance arithmetic requires. Corcept generated about $421 million in the first half, so reaching the low end of its new $1.1 billion to $1.2 billion range calls for roughly $340 million per quarter over the back half, and the top end needs closer to $390 million. Notably, the full-year consensus of about $986 million still sits below management's floor, suggesting some analysts either have not caught up or doubt the company can deliver. A third-quarter figure well above $329 million would go a long way toward closing that credibility gap.
Lifioly is the swing factor. The drug brought in $47.6 million in its first quarter, with more than 1,300 patients started and over 1,000 prescribers, up from just 200 or so a little over a month into the launch. Early preferred placement in treatment guidelines and formal coverage for more than 70% of insured lives remove the usual barriers that slow oncology launches. What would validate the story is continued growth in new patient starts and evidence that early patients are staying on therapy, which turns launch momentum into recurring revenue. One nuance worth noting is that about 70% of oncology volume flows through distributors. Management described inventory effects as minimal, but any sign that initial stocking flattered the second quarter would quickly undercut the ramp narrative.
The Cushing's syndrome business matters just as much. Management cited record new prescriptions and prescribers and declared the transition to its new specialty pharmacy complete. This quarter should be the first clean read without that disruption, so softness here would be harder to explain away. Generic pressure on Korlym remains a background factor, though the authorized generic mix had stabilized, and a shift in that balance or in net pricing could pinch an otherwise very high margin profile.
Sentiment has warmed considerably, with bullish readings rising to about 62% from 41% ahead of the prior report, even as the share price has moved the other way. At $87.13, the stock trades near the bottom of its post-earnings range of $84.13 to $126.38, though it remains comfortably above its 200-day moving average of $73.62. That combination suggests the stock has shed much of the enthusiasm that followed last quarter, leaving room for a reaction if results are strong, but also little cushion of goodwill if the ramp stalls.
Looming over everything is the December 17 decision date for Relacorlin in Cushing's syndrome, a resubmission following last year's surprise rejection. The quarter will not settle that question, but any update on the review and on the late-stage readouts expected into early 2027 will shape how investors value the pipeline. Ultimately, the report comes down to whether Lifioly and the core endocrinology franchise are growing fast enough to make the raised guidance look conservative rather than aspirational. A clean beat with reaffirmed or higher guidance would reinforce the turnaround narrative; anything that makes the $1.1 billion floor look stretched would explain the stock's recent skepticism.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 50 min | |
| 5 hours | |
| Oct-26 | |
| Oct-23 | |
| Oct-20 | |
| Oct-15 | |
| Oct-06 |
Corcept, IBD Stock Of The Day, Setting Up Amid Booming Earnings Growth
CORT
Investor's Business Daily
|
| Sep-23 | |
| Sep-18 | |
| Sep-04 | |
| Sep-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-31 | |
| Jul-30 |
