Corcept's Breakout Quarter Collides With A Static Guide And A Stock Near Its Lows
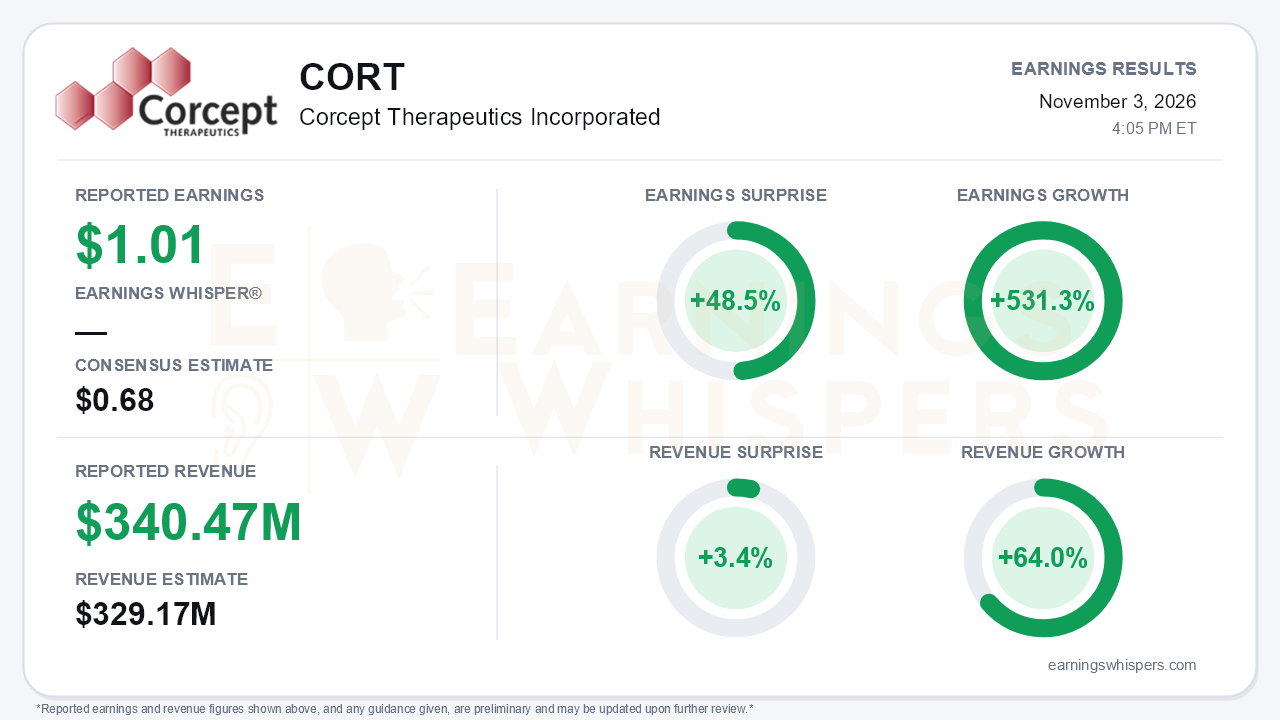
Corcept Therapeutics delivered a decisive beat in the third quarter. It earned $1.01 per diluted share against a $0.68 consensus, a 48.5% surprise, and EPS grew 531.3% from $0.16 a year ago. Revenue of $340.47 million topped the $329.17 million estimate by 3.4% and rose 64.0% year over year. The quarter extended a steep 2026 ramp, with revenue climbing from $164.9 million in Q1 to $256.1 million in Q2 and now $340.5 million. Profitability turned just as sharply: a $31.8 million Q1 loss became $43.0 million of net income in Q2 and $126.8 million in Q3. Yet management only reiterated its $1.1–$1.2 billion revenue guide rather than raising it for a third time, and that is the central tension. The business is accelerating, but the outlook did not move with it.
The quality of the beat holds up well, with one caveat. The improvement is mostly operating leverage, not accounting. Revenue rose $84.4 million sequentially while total operating expenses grew only $10.9 million, to $225.7 million. Operating income reached $114.7 million, versus $10.2 million a year ago. SG&A jumped to $164.4 million from $124.0 million to support the oncology launch, but R&D fell to $56.7 million from $68.8 million, which flattered the year-over-year comparison. The caveat is taxes. A $6.5 million income tax benefit lifted GAAP net income above pre-tax income of $120.3 million, so the bottom line was modestly helped by taxes. Cash and investments rose $117.7 million to $662.3 million, even after $43.7 million of buybacks.
Both franchises contributed to the quarter. Lifyorli, launched in April for platinum-resistant ovarian cancer, generated $91.4 million, up 92% from $47.6 million in Q2. Prescribers rose to more than 1,700 from more than 1,000, and patients treated rose to more than 2,300 from more than 1,300. Management said the launch exceeded expectations, with repeat prescribing rising and use moving into earlier lines of therapy. The legacy Korlym and authorized generic business was not merely a cash cow. It grew to $249.1 million from $208.6 million sequentially, which management attributed to rising awareness of Cushing's syndrome. That narrative gained outside support when the ADA/EASD consensus report recommended screening for hypercortisolism in poorly controlled type 2 diabetes and cited mifepristone. One nuance matters, though: the sequential dollar gain of about $84 million was slightly smaller than Q2's roughly $91 million.
That nuance makes the guidance more consequential. Nine-month revenue of $761.5 million implies Q4 revenue of roughly $339–$439 million. The low end of that range would mean essentially no sequential growth after a quarter that grew 33%. Analysts pressed management on the static guide, and the call did not fully resolve the question. Whether the guide is conservative or reflects a real flattening is now the key debate. Management did reaffirm its long-range ambitions: at least $2 billion for the Cushing's business by decade end, more with relacorilant, and over $1 billion for Lifyorli in ovarian cancer.
The catalyst calendar is dense but carries binary risk. Relacorilant for Cushing's syndrome has a December 17 PDUFA date after a prior complete response letter, and liver-enzyme questions went unaddressed on the call. A European approval of relacorilant for ovarian cancer is expected by year-end after a positive CHMP opinion. BELLA Part A data supported earlier-line use, showing 7.2 months of median PFS, a 59% ORR, and stronger results in bevacizumab-naïve patients. Bears still have legitimate ammunition:
- Analysts raised emerging ovarian-cancer competition, including Genmab's Rina-S.
- The endocrinology president was replaced.
- The ALS Phase 3 start has slipped again, from mid-2026 to next year.
- The MASH program needs another Phase 2 study before Phase 3.
- The cervical cancer trial STELLA was initiated but does not appear among the readouts expected in 2027.
The market had already turned skeptical before the report. Shares entered at $80.46, down 28.2% from the $112 open after the July report and about 36% below the $126.38 52-week high set in late August. They sat just 1.3% above the inter-earnings low struck the day before the release, though still about 7.6% above the 200-day moving average. Investor sentiment remained positive but weakened, falling from 0.41 to 0.24. The Earnings Whispers trend signals are mixed, with momentum positive but AVWAP negative, consistent with a stock whose fundamentals improved while its price slid.
The bottom line is that Corcept produced a genuine breakout quarter. A rapid Lifyorli launch, a re-accelerating Cushing's franchise, and real operating leverage turned the company into a strongly profitable grower. However, the unchanged guide, a binary December PDUFA, and pipeline delays give the market reasons to hesitate. With shares near their lows and sentiment cooler, the setup now hinges less on whether the quarter was strong and more on whether Q4 and the relacorilant decision prove the stall in guidance was merely caution.
Read our earnings preview for Corcept Therapeutics Incorporated: https://www.earningswhispers.com/article/CORT/21983
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-23 | |
| Oct-20 | |
| Oct-15 | |
| Oct-06 |
Corcept, IBD Stock Of The Day, Setting Up Amid Booming Earnings Growth
CORT
Investor's Business Daily
|
| Sep-23 | |
| Sep-18 | |
| Sep-04 | |
| Sep-04 |
