TAT Technologies Must Prove Its Record Quarter Was No Fluke After A One-Third Stock Slide
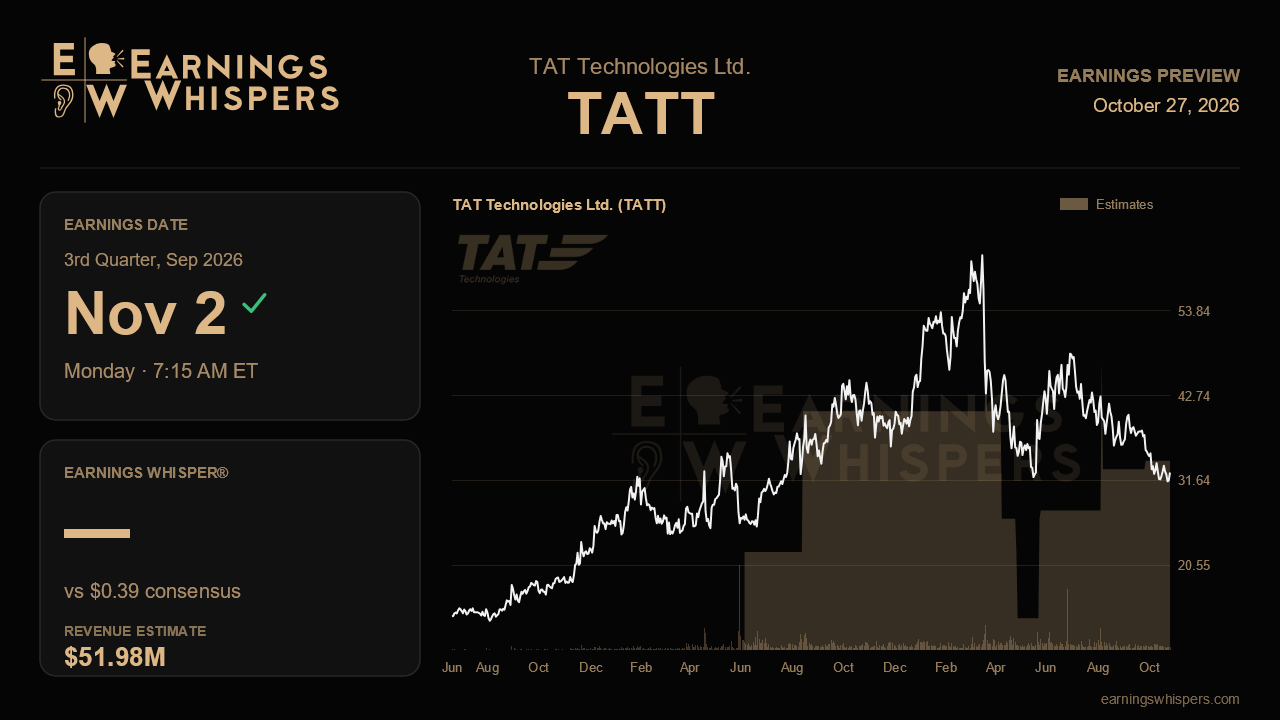
TAT Technologies enters its third-quarter report with an awkward split between story and stock. Last quarter, management described the business as reaching an inflection point. Revenue rebounded to a record, backlog climbed to another high and the Honeywell relationship deepened. Yet the shares have since fallen about 34%, while the S&P 500 slipped only modestly. The report due before the open on November 2 needs to show whether that optimism was justified or whether the second quarter was a one-time catch-up.
The Street is looking for earnings of $0.39 a share on revenue of about $52.0 million. That would mean revenue growth of roughly 12% from the year-ago $46.2 million, but EPS growth of only about 5% from $0.37. The gap between those two rates says a lot. Analysts expect the top line to keep growing, but they are not assuming much margin expansion. That is a sensible bar given what management said last time. The forecast is also slightly below the second quarter's $52.9 million. Management explicitly cautioned against treating that figure as a run rate and suggested the first-half average was a better baseline. That average sits closer to $47 million, so consensus effectively assumes the company can hold near its record level. That is a more demanding call than the modest headline growth rate implies.
The second quarter got help from previously stuck APU and landing-gear work orders, worth about $15.5 million at the end of the first quarter, finally shipping. The key question now is whether new demand can fill that gap. The evidence would include fresh long-term APU contract wins converting into revenue and early sales from TAT's new role as Honeywell's sole global authorized distributor for 331-200/250 APU spare parts. Investors will also want progress from the three 131-9A APUs bought for trading and leasing. Backlog, which went from $550 million to $580 million to $615 million over three quarters, should keep rising or at least hold. A pause would not break the thesis, but a decline would raise questions about how durable the momentum is.
Margins and cash are the more likely sources of surprise. Gross margin has stayed around 25%, held back by higher procurement costs from lingering supply-chain inefficiencies. A strong shekel caused an FX loss of more than $600,000 last quarter, and landing-gear lead times are now over a year. Operating margin reached 10.6% and adjusted EBITDA margin 14% in the second quarter. Holding those levels on similar revenue would support the operating-leverage argument. Operating cash flow turned slightly negative last quarter because of inventory stocking for the distribution deal and collections that slipped into the third quarter. A clear rebound in cash flow this time would go a long way toward easing concerns, especially as management prepares to put its $105 million credit facility and $43 million net cash toward acquisitions.
Sentiment has improved from clearly bearish before the last report to mildly bullish now. The price action tells a harsher story. At $32.68, the stock sits well below its 200-day moving average of $42.73 and near the bottom of its post-earnings range of $30.47 to $52.99. Expectations embedded in the share price look low, even if analysts' numbers do not.
The central issue is whether third-quarter revenue near $52 million comes with steady margins and recovering cash flow. If it does, the inflection story holds and the recent selloff looks overdone. If revenue falls back toward the first-half average while inventory keeps absorbing cash, the market's skepticism about the record quarter will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Sep-14 | |
| Aug-05 | |
| Aug-04 | |
| Jul-23 | |
| Jul-14 | |
| Jun-29 | |
| Jun-03 | |
| May-20 | |
| May-20 | |
| May-19 | |
| Apr-30 | |
| Apr-08 | |
| Mar-19 |
