TAT Technologies Posts A Clean, Margin-Driven Beat, But Lumpy Trading Revenue And A Trimmed Backlog Temper The Run Rate
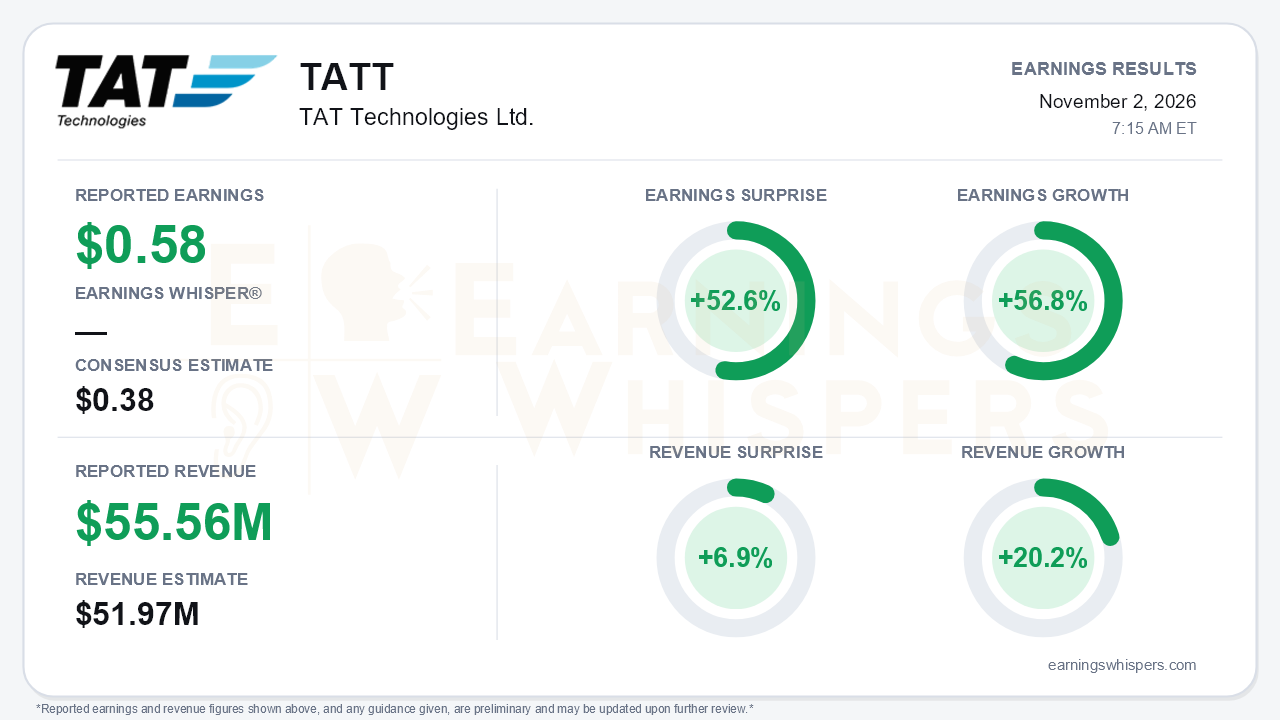
TAT Technologies delivered one of the cleanest beats of its recent history. Third-quarter EPS was $0.58, ahead of the $0.38 consensus by 52.6% and up 56.8% from a year ago. Revenue reached a record $55.56 million, beating the $51.97 million estimate by 6.9% and rising 20.2%. The quarter had no one-time items, so GAAP and adjusted diluted EPS were identical at $0.58. Whatever happens to the stock, investors cannot dismiss this result as accounting noise. The central tension is elsewhere. The report showed record profitability, yet the shares had fallen 35.5% since the open after the August report and entered earnings just 4.4% above a fresh 52-week low.
The beat was a margin story more than a top-line story. Revenue growth of 20.2% was a touch slower than the 23% pace in the second quarter, though sales still rose sequentially to a record. The real change was in profitability:
- Gross margin jumped to 30.9%, from roughly 25% in Q2 and 24.4% in Q1.
- Operating margin rose to 16.3%, from 10.6% and 7.3% in the prior two quarters.
- Adjusted EBITDA reached $10.9 million, a 19.6% margin. That essentially hits the roughly 20% aspiration CEO Igal Zamir described at the start of the year, when he attached no timeline to it.
This leverage came almost entirely from gross profit. Operating expenses grew about 28%, faster than revenue, as R&D more than doubled and G&A climbed 25%. The quality of the beat holds up on the income statement. It deserves more scrutiny on the cash flow statement. Operating cash flow fell to $3.8 million from $7.5 million a year earlier because TAT added $10.6 million of inventory. Capital spending was $4.4 million, so the quarter was roughly free-cash-flow neutral.
That inventory build is the operating story, and management framed it as offense rather than slippage. The money supports the expanded Honeywell relationship, which runs through 2036 and includes sole global distribution of the 331-200/250 APU. Management said that arrangement is now contributing high-margin profit. Segment growth showed the same shift:
- APU revenue rose 34.4%, with the line back at full run rate as supply chains normalized and new long-term agreements ramp.
- Trading, leasing and distribution revenue surged 85.5%, up from 17% growth in Q2.
- Heat exchangers grew a steadier 7.3%.
The tone also escalated. Q1 was described as a "temporary disruption" and Q2 as an "inflection." This quarter management said "fundamentals never stronger" and expressed explicit confidence in Q4 and 2027.
The headline margin needs context, however. Management itself warned that trading revenue will stay lumpy and pointed to year-to-date growth of 42.9% as the better base. The CFO also framed the trailing three-quarter gross margin of about 27%, not the 30.9% print, as the representative level. That is a meaningful upgrade from the prior roughly 25% framing, but it implies Q3 overstated the sustainable run rate. Bears also have other legitimate ammunition:
- Backlog and long-term agreements fell to roughly $577 million from a record $615 million in Q2. The drop came after $34 million of landing gear contracts were removed because components are unavailable. Excluding that removal, backlog was roughly flat, so it is no longer setting records.
- Landing gear has shrunk to under 4% of revenue, with capacity shifted to APU work.
- TAT expects to begin paying cash taxes of roughly 15% to 19% in 2027 as its net operating losses run out. Reported EPS already carries a tax provision of about 19% of pretax income, so the larger impact will likely fall on cash flow rather than earnings.
- M&A received less attention on the call, and no deal has been announced despite the stated goal of at least one in 2026.
- Management flagged higher jet fuel prices but said it has seen no impact on maintenance activity or aircraft retirements.
On the positive side, a new $100 million U.S. revolver and $42.6 million of net cash give TAT room to fund both inventory and acquisitions.
The market setup is more complicated than the surprise implies. Investor sentiment improved sharply, from -0.399 to essentially neutral at -0.005, so skepticism largely dissipated going into the print. Price has not followed. The stock sits at $31.80, about 24.9% below its $42.35 200-day moving average. It is 40% below the $52.99 inter-earnings high, which was set the day after the August report, and only modestly above the October 23 low of $30.47. The Earnings Whispers trend readings reflect that split: sequential growth and momentum are positive, while price and AVWAP remain negative.
The bottom line is that TAT produced a high-quality quarter that turnaround skeptics were not positioned for: record revenue, a step change in margins and an earnings beat with no one-time help. Management's own guidance points to a 27% gross margin baseline rather than 31%, backlog has stopped climbing, and inventory is absorbing cash. Even so, a stock trading near its 52-week low sets a low bar for a company that has just raised its profitability framework.
Read our earnings preview for TAT Technologies Ltd.: https://www.earningswhispers.com/article/TATT/21982
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 10 hours | |
| Oct-27 | |
| Oct-27 | |
| Sep-14 | |
| Aug-05 | |
| Aug-04 | |
| Jul-23 | |
| Jul-14 | |
| Jun-29 | |
| Jun-03 | |
| May-20 | |
| May-20 | |
| May-19 | |
| Apr-30 |
