UroGen's Zysturi Ramp Faces A Summer Test As Wall Street Pencils In A Profit
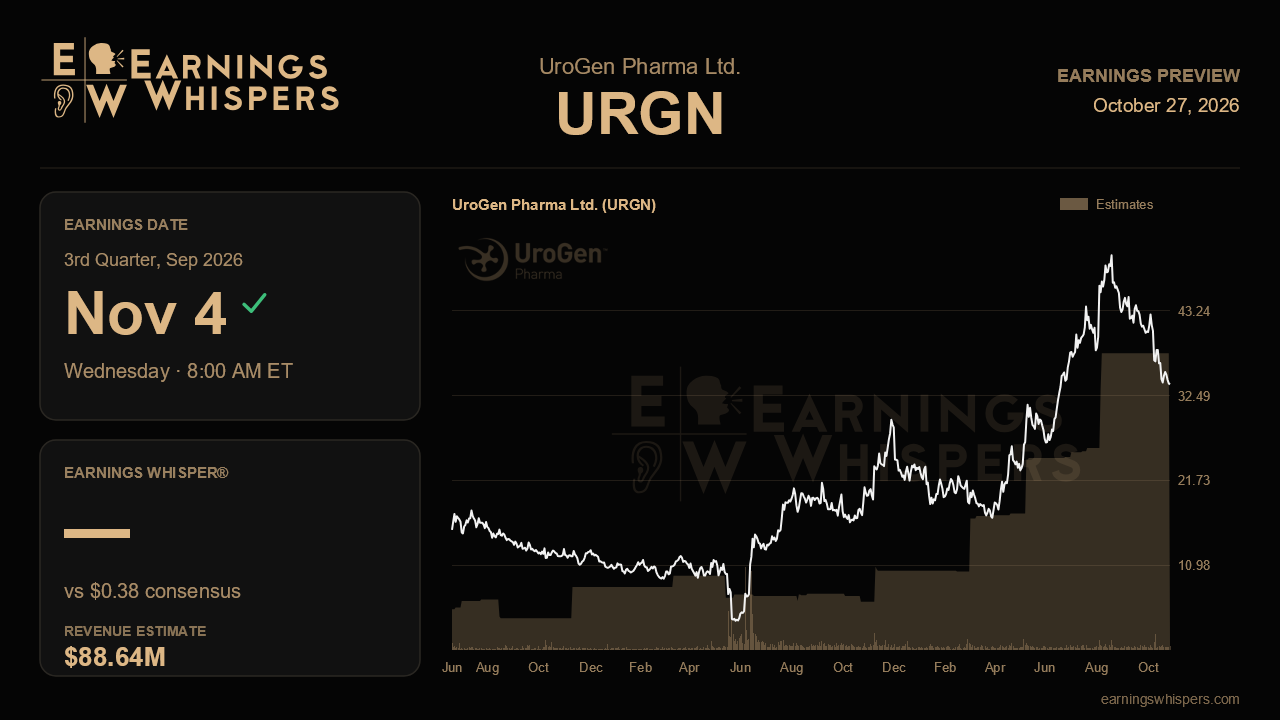
UroGen Pharma enters its third-quarter report with an awkward contradiction. The operating story coming out of the last call was the strongest the company has told, with its bladder cancer drug Zysturi growing faster than management's own linear roadmap. Yet the stock has fallen about 19% since then, trailing the S&P 500 by nearly 18 percentage points. The report, due before the open on November 4, has to show that the launch is still compounding after management deliberately talked down expectations for a summer quarter.
The Street is looking for revenue of about $88.6 million, up roughly 222% from $27.5 million a year ago and about 22% above the second quarter's $72.5 million. More striking is the earnings call. Consensus sits at a profit of $0.38 a share, a swing from a $0.28 loss last quarter and a $0.69 loss a year earlier. That bar deserves scrutiny. A roughly $16 million sequential revenue gain would have to carry a lot of weight, especially since management raised full-year operating expense guidance to $260 million to $270 million from $240 million to $250 million. Investors should look closely at what drives any profit and whether it reflects the core business or items that will not repeat.
The revenue number looks more reasonable once you break it apart. Jelmyto, the older upper tract product, has been a steady low single-digit grower at about $22 million a quarter, against reaffirmed annual guidance of $97 million to $101 million. If it holds there, consensus implies Zysturi sales in the mid-$60 million range, an increase of about $15 million. That is smaller than the $21 million jump from the first to the second quarter and close to the $15 million gain before that. In other words, analysts appear to have accepted management's warning against assuming further acceleration. A Zysturi figure that grows by roughly the same dollar amount as before would confirm the linear path toward the more than $1 billion peak management has described. A figure that clearly falls short of that increment would raise the question the stock price already seems to be asking: was the second quarter a high point rather than a new baseline?
The launch indicators matter as much as the revenue total. Last quarter, unique prescribers rose to 452 from 256, activated accounts climbed to 1,444, and repeat prescribers reached about 45% of writers. The mix also kept shifting toward community urology, where most of the addressable market sits. Continued gains in repeat prescribing and community share would suggest demand is broadening and becoming routine, not just drawing on early adopters. Payer access is already above 95% open coverage, so growth has to come from behavior, not reimbursement wins. On the pipeline, the UGN-103 NDA submission was promised for the third quarter. Confirmation that it was filed, along with progress on starting the UGN-501 Phase 1 trial and completing UGN-104 enrollment, would show that the higher spending is producing results.
Sentiment has soured sharply. Bearish readings now outnumber bullish ones by about 51%, compared with only a mild bearish tilt before the last report. The chart tells the same story. Shares ran to nearly $51 after the second-quarter print and have since given back the entire move, closing at $34.04, just above the post-earnings low of $33.40. The stock still sits above its 200-day moving average near $31, but it is testing the bottom of its range heading into the print.
This leaves a lower bar on sentiment but a demanding one on earnings. The central issue is simple. If Zysturi adds dollars at roughly the pace of prior quarters despite seasonality, and prescriber depth keeps improving, the selloff will look like an overreaction to management's caution. If the increment shrinks meaningfully, the market will conclude the linear ramp is bending, and the raised spending plan will start to look less like offense.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-19 | |
| Sep-09 | |
| Sep-04 | |
| Sep-02 | |
| Aug-20 | |
| Aug-17 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-21 | |
| Jul-15 | |
| Jul-08 |
