UroGen Misses EPS Target But Edges Toward Breakeven As ZUSDURI Scales; JELMYTO Cut And A Normalizing Launch Curve Complicate The Story
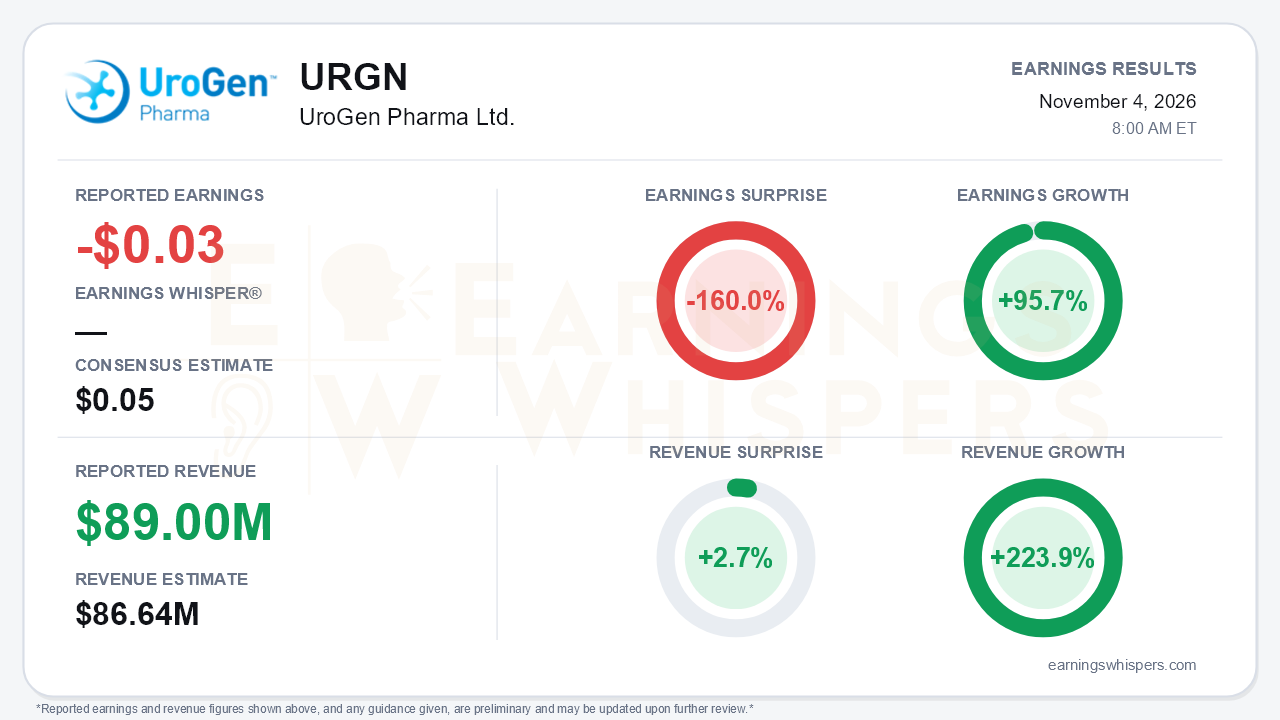
UroGen Pharma reported a third-quarter loss of $0.03 per share, missing the $0.05 consensus estimate by 160.0%. Revenue of $89.0 million beat the $86.64 million consensus by 2.7% and rose 223.9% from a year ago. Earnings improved 95.7% year over year as the net loss shrank to $1.5 million from $33.3 million. On a sequential basis, the loss also narrowed from $14.4 million in the second quarter and $23.6 million in the first. That is the central tension. The ZUSDURI launch is carrying UroGen to the edge of profitability, but the quarter fell short of the profit the Street expected. It also brought a JELMYTO guidance cut and clear signs that ZUSDURI's percentage growth is normalizing after the first-half surge.
The miss deserves context. On a GAAP basis, UroGen produced operating income of $8.3 million, compared with an operating loss of $27.4 million a year ago. Gross profit rose to $81.5 million. Below the operating line, the company still carries about $9.4 million of quarterly financing costs: $4.5 million of non-cash expense on the RTW prepaid forward obligation and $4.8 million of interest on long-term debt. Interest expense rose after the company added $75 million of borrowings earlier this year. Those costs left pre-tax results just under breakeven, and a $1.0 million tax expense turned the result into a net loss. The operating business crossed into profitability this quarter, but the balance sheet structure absorbed the gain. That structure includes $397 million of liabilities and a $125 million shareholders' deficit.
ZUSDURI net revenue reached $68.0 million, up 35% from $50.4 million in the second quarter. Adoption metrics remain strong:
- Unique prescribers rose to 662 from 452.
- Repeat prescribers climbed to 331 from 204, lifting the repeat share to roughly 50% from 45%.
- Primary, non-adjuvant use now exceeds 60%.
The growth math is shifting, however. Percentage growth slowed from 73% in the second quarter, and the absolute sequential gain of about $18 million trailed the roughly $21 million added in the prior quarter. That is consistent with management's linear framework of $15 million to $20 million in added revenue per quarter. Management also cited summer seasonality, flagged a fourth-quarter holiday slowdown, and said it does not expect an inflection for several quarters. The full direct-to-consumer campaign is not planned until mid-2027. Activated sites of care rose to 1,538 from 1,444, a slower pace of account additions than the prescriber figures might suggest. The call preserved a credible growth story, just a steadier one than investors may have hoped for in the summer.
JELMYTO is the clearer blemish. Third-quarter revenue fell to $21.0 million from $25.7 million a year earlier and $22 million in the second quarter. The decline included a one-time $1.5 million gross-to-net hit tied to a CMS discarded-drug true-up. More concerning for the outlook, competing clinical trial enrollment in low-grade upper tract urothelial cancer is diverting patient starts. According to the call, that competition includes UroGen's own UGN-104 study. Full-year JELMYTO guidance was cut to about $90 million from the $97 million to $101 million range the company had reaffirmed on each of its prior three calls. Operating expense guidance of $260 million to $270 million, already raised from $240 million to $250 million last quarter, is now expected to land at the upper end. Cash fell to $90.5 million from $108 million in June and $140.3 million in March. That burn makes management's first explicit target of profitability and positive cash flow in the fourth quarter the most important near-term promise to monitor.
The longer-term catalysts are substantive:
- The FDA accepted the UGN-103 NDA, with a June 14, 2027 PDUFA date.
- A method-of-treatment patent extending ZUSDURI and potential UGN-103 coverage into July 2044 is now issued and Orange Book listed.
- The LONGVIEW-HR Phase 3 trial in high-risk NMIBC is slated to start this quarter.
- UGN-501 dosed its first Phase 1 patient.
Management also said it is comfortable with full-year ZUSDURI consensus. These developments strengthen the durability of the franchise, but none changes near-term earnings.
Investor sentiment deteriorated sharply heading into the report, falling from -0.098 to -0.631, a meaningful move deeper into negative territory. Price action tells the same story. Shares hit a 52-week high of $50.81 on August 19 after the prior report, then slid to an inter-earnings low of $32.39 on October 30. They entered earnings at $34.40, down 18.4% from the post-report open, 32.3% below the high and just 6.2% above the low. The stock still sits about 9.4% above its 200-day moving average of $31.44. The Earnings Whispers sequential growth and momentum trends remain positive, while AVWAP is negative, reflecting the gap between improving fundamentals and recent selling.
The bottom line is that UroGen's quarter was better operationally than the EPS miss implies but less clean than the revenue beat suggests. ZUSDURI is scaling steadily, operating income has turned positive, and the pipeline and patent estate lengthen the runway. Bears still have legitimate ammunition. JELMYTO guidance was cut, expenses are drifting higher, cash continues to decline, and ZUSDURI growth is settling into a linear pace. With sentiment already deeply negative and shares near the bottom of their range, delivering the promised fourth-quarter profit and positive cash flow is now the key test.
Read our earnings preview for UroGen Pharma Ltd.: https://www.earningswhispers.com/article/URGN/21989
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-19 | |
| Sep-09 | |
| Sep-04 | |
| Sep-02 | |
| Aug-20 | |
| Aug-17 | |
| Aug-05 | |
| Aug-05 |
