Flex Beats And Raises Again As Axiom Power Business Accelerates, But Spin Costs, Debt And A Battered Stock Complicate The Setup
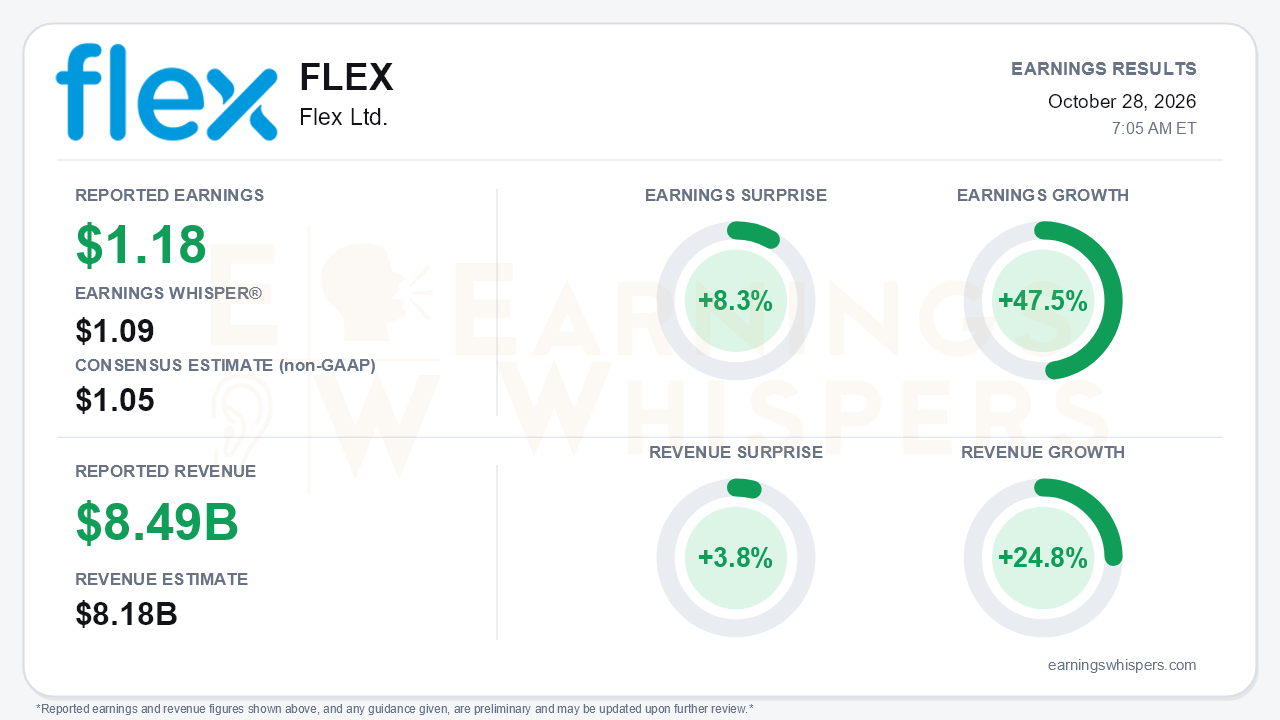
Flex delivered the kind of quarter that should have reassured investors who drove the shares sharply lower over the past three months. Adjusted EPS of $1.18, a company record, topped the $1.05 consensus by 8.3% and cleared the $1.09 Earnings Whisper number. Revenue of $8.491 billion beat the $8.18 billion consensus by 3.8%. Earnings grew 47.5% year over year and revenue grew 24.8%. More important than the beat is the trajectory. Revenue growth has gone from 17% two quarters ago to 21% last quarter to roughly 25% now. Adjusted operating margin reached 7.1%, up from 6.7% in the prior quarter and 6.0% a year ago. Management also raised full-year guidance for the second consecutive quarter. Fiscal 2027 adjusted EPS guidance is now $4.84 to $5.16, up from $4.42 to $4.74, implying 52% growth at the midpoint.
The quality of the beat deserves some scrutiny, mainly because of what sits between GAAP and adjusted results. GAAP EPS was $0.70 against adjusted EPS of $1.18. The gap is driven largely by $110 million of "legal and other" charges. About $91 million of that relates to the planned spin-off of the Cloud and Power Infrastructure segment, and $19 million reflects acquisition costs. These are plausibly one-time, but they are real cash: free cash flow fell to $261 million from $305 million a year ago, with $61 million of separation costs weighing on the quarter. Capex rose to $241 million from $150 million. Full-year free-cash-flow conversion is still guided to only about 40% including spin costs. Inventory climbed to $7.3 billion, up 39% year over year, and inventory days net of advances rose to 60 from 56. The earnings are clean on an operating basis. The cash conversion is not yet.
Beneath the headline, the story is increasingly about CPI, the power and cloud infrastructure business being spun off as Axiom. CPI grew 54%, above its 45% to 55% guide and well ahead of the prior quarter's 35%. Segment margin expanded to 10.7% from 9.7%, and power margins reached roughly 16%. Management lifted CPI's fiscal 2027 growth outlook to 75% to 85% and now expects about 240 basis points of margin expansion, up from roughly 100. Third-quarter CPI growth is guided at 105% to 115%, helped by acquisitions. Management also noted that about half of the roughly $950 million full-year CPI raise is organic. The legacy RMS and ITS businesses grew 16% for a fourth straight quarter, and ITS guidance was raised again on communications and networking strength. There are soft spots: lifestyle and consumer weakened, RMS margin slipped 20 basis points sequentially, and second-half comparisons get harder.
The forward catalysts are substantial. EPC Power closed on October 14, adding roughly $800 million in annual revenue, and management expects it to be accretive in fiscal 2027. The Axiom name has been unveiled, the Form 10 has been filed, and the spin remains on track for early calendar 2027. Flex also introduced prefabricated AI modules and plans liquid-cooling launches over the next six months. A November 10 investor day will set long-term targets for both companies. The cost of this push is a heavier balance sheet. Long-term debt rose to $5.2 billion from $3.75 billion at fiscal year-end, and the $4.4 billion EPC financing lifts Q3 interest and other expense to about $120 million from roughly $58 million. A planned $2 billion Axiom convertible preferred sale is meant to repay about half of that debt. That interest drag helps explain why Q3 EPS guidance of $1.19 to $1.25 sits only modestly above this quarter's $1.18 despite 28% projected revenue growth. Bears also have legitimate ammunition in Axiom's customer concentration: the top two customers could represent 60% to 70% of sales. Management also expects component shortages to persist for years.
The market setup is far more complicated than the surprise implies. Shares entered the report at $83.35, down 16.7% from the $100.01 open after the July report and 18.7% below the 200-day moving average of $102.50. The stock spiked to $131.63 in mid-August, then collapsed to $73.48 on October 23 and entered earnings only 13.4% above that low. Investor sentiment remained positive but weakened, slipping from 0.44 to 0.37. The Earnings Whispers trend readings are split: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Flex's fundamentals improved on nearly every operating measure that matters, including accelerating revenue, expanding margins, a breakout quarter in CPI and a second straight guidance raise. The stock's slide suggests investors are worried about something other than near-term demand, likely spin execution, leverage, cash conversion and AI-infrastructure concentration. This report answered the growth question convincingly. The cash and balance-sheet questions will be tested at the November investor day and in the quarters leading up to the Axiom separation.
Read our earnings preview for Flex Ltd.: https://www.earningswhispers.com/article/FLEX/20846
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 8 hours | |
| 10 hours | |
| 13 hours | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-07 | |
| Oct-05 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-08 |
