Ridgepost's First Full Stellis Quarter Puts A 20% Revenue Jump To The Test
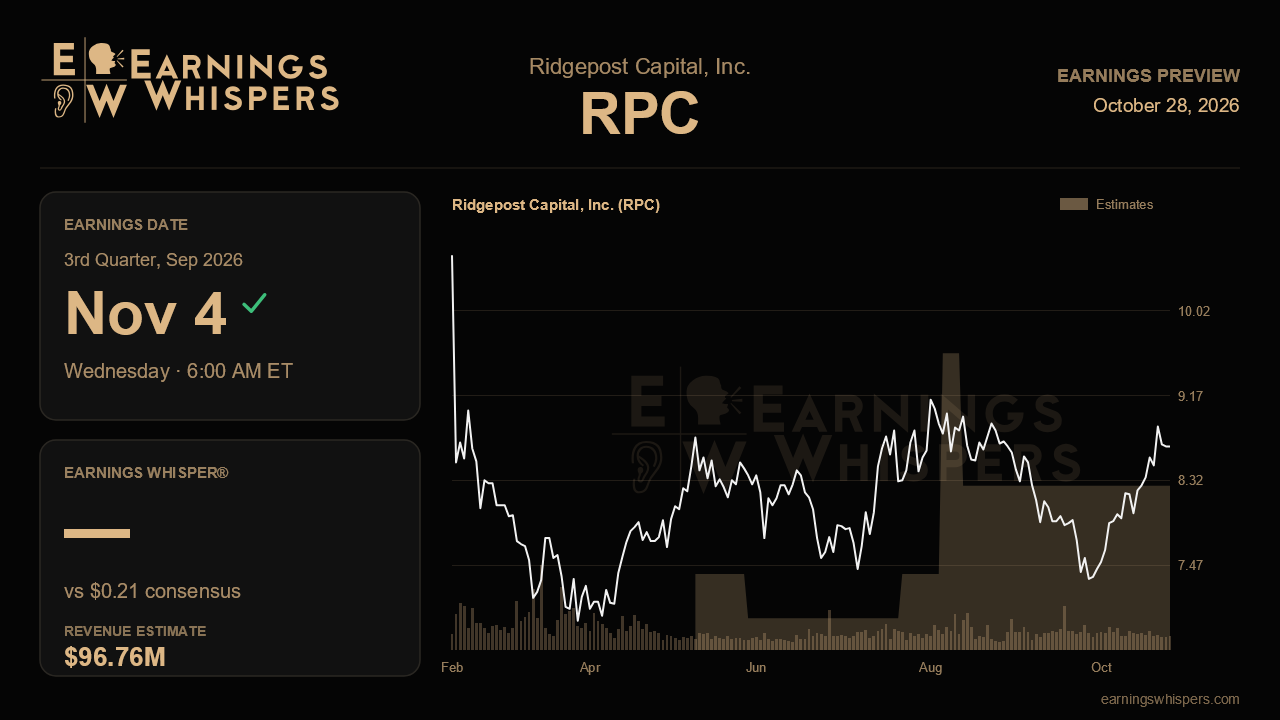
Ridgepost Capital heads into its September-quarter report with a striking disconnect. Management sounded more confident on its last call than it has in some time, citing accelerating asset growth and a freshly closed acquisition. Yet the stock has slipped 8.2% since that report, trailing a roughly flat S&P 500 by more than seven points. The November 4 release, due before the open, is the first quarter to include a full three months of Stellis. That makes it the cleanest look yet at whether the deal is delivering the growth that justified piling on debt to buy it.
The Street has set a demanding bar. Consensus calls for earnings of $0.21 a share on revenue of $96.8 million, up from $0.16 and $80.9 million last quarter. That is a sequential revenue jump of roughly 20%, and Stellis must supply much of it, since Q2 contained only about a week of the business after the June 22 close. Management did not issue fresh quarterly guidance. It did reaffirm its full-year framework: a core fee rate of 103 basis points, a fee-related earnings margin in the mid-40s, and $6 million to $8 million in catch-up fees from its direct and secondary funds. Hitting that fee rate is no small task. The rate was 97 basis points in Q1 and 100 in Q2, so the back half must run noticeably above 103. A visible step-up this quarter, perhaps helped by catch-up fees, would make the annual target look credible. Another reading near 100 would raise doubts.
The operating story rests on fee-paying assets. Management said growth since its September 2024 investor day had accelerated to a 20% annual pace, up from the 16% cited a quarter earlier. Fee-paying AUM reached about $35 billion. Fundraising looked lumpier. It fell to $1.1 billion in Q2 from a record of roughly $2 billion in Q1, although management called the first-half total of more than $3 billion on track for its $10 billion two-year goal. A rebound this quarter would validate that defense. Another quarter near $1 billion would leave a heavier lift for 2027. Investors should also look for early evidence on the new Stellis opportunity. Management sized it at $500 million to $1 billion in extra annual commitments by tapping the equity deployment of its credit platform's sponsor network. It is too soon for the full benefit, but signs of joint origination would help. Strong fund distributions, which had more than doubled year over year through late July, would support the fundraising pipeline as well.
The balance sheet is the other swing factor. Leverage stood near 2.8 times EBITDA pro forma for Stellis, above the mid-2x target. The revolver was fully drawn at SOFR plus 260 basis points, and $20 million had already been repaid early in the third quarter. Further paydown, and a clear deleveraging timetable, would ease a key worry. Management has also flagged a cash tax headwind: net operating losses run out by year-end, and the cash tax rate climbs to the mid-teens in 2027. Any update on how that hits distributable earnings will matter.
Sentiment remains bearish but has improved noticeably from the prior quarter, a sign skeptics are softening even as the stock lags. At $8.66, shares sit comfortably above their 200-day moving average of $7.19. They are in the upper half of a $7.23 to $9.51 post-earnings range, which closely mirrors last quarter's band. They are not near a breakout, so the report itself will likely set the direction.
The central question is whether Stellis turns management's confident tone into hard numbers. The deal needs to lift revenue toward consensus, push the fee rate toward 103 basis points and generate cash to pay down debt. If it does, the gap between improving fundamentals and a lagging share price looks like an opportunity. A miss on any of those fronts would suggest the market's caution was warranted.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-14 | |
| Aug-11 | |
| Aug-05 | |
| Aug-05 | |
| Jul-17 | |
| Jul-16 | |
| Jun-22 | |
| Jun-16 | |
| Jun-09 | |
| Jun-08 | |
| May-19 | |
| May-07 | |
| Apr-15 | |
| Mar-23 |
