Ridgepost Capital Misses Consensus, But Accelerating Fee Growth And A Margin 'Trough' Call Leave A Back-Loaded Q4 To Prove
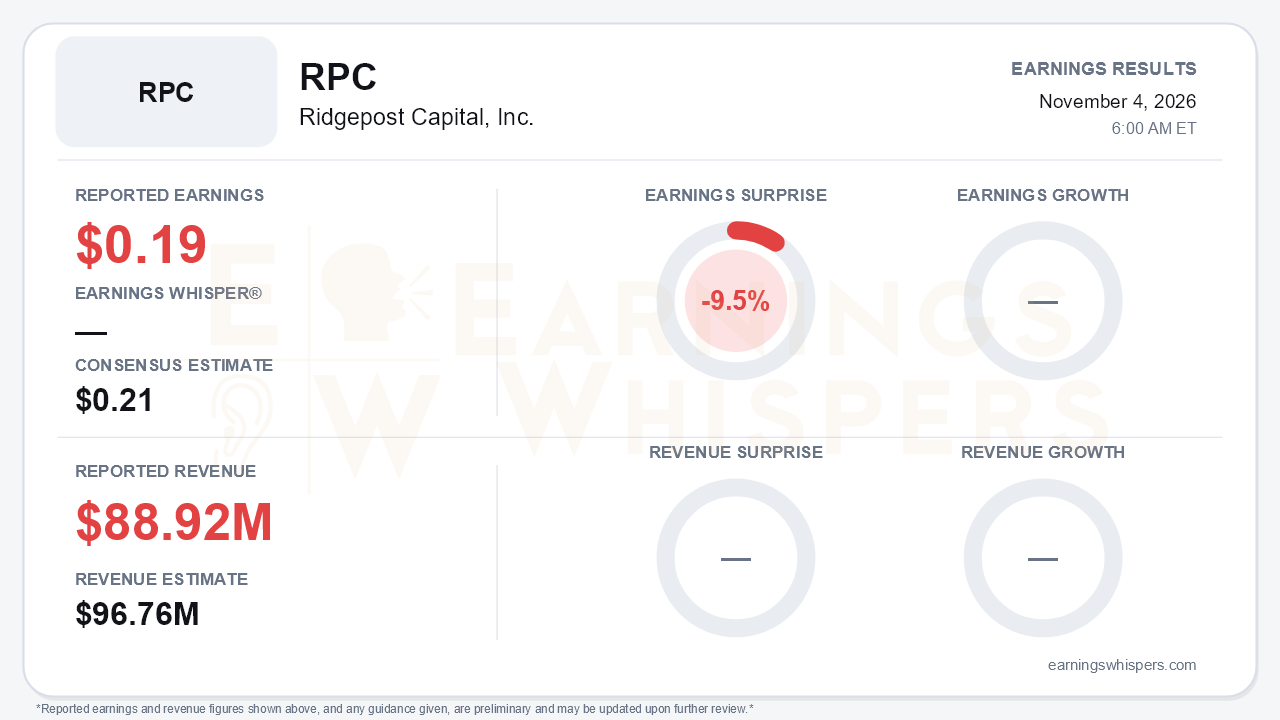
Ridgepost Capital (NYSE: RPC) reported third-quarter earnings of $0.19 per share on revenue of $88.92 million, short of the $0.21 consensus by 9.5% and below the $96.76 million revenue estimate by 8.1%. On the headline comparison, this was a clean miss. The operating story management told was different: its strongest growth quarter of 2026, with an explicit claim that fee-related earnings margins have bottomed. That is the central tension. The business appears to be accelerating, but the reported figures did not meet Street expectations. The fourth quarter now carries an unusually heavy burden on fee rates, catch-up fees and fundraising closes.
The quality of the quarter depends on which yardstick investors use. The company's own adjusted net income per share was $0.25, up from $0.24 in the second quarter. That figure sits well above the $0.19 Earnings Whispers result. Investors should recognize that the two measures differ and should not read the adjusted figure as a beat. Revenue of $88.92 million lines up with the $89 million in fee-related revenue management discussed. That total grew 17% year-over-year, a clear acceleration from 11% growth in both the first and second quarters. Fee-related earnings rose 19% to $43 million, compared with 10% growth in Q2. FRE margin held at 48%, matching Q2 and well above Q1's 44%. That brings the year-to-date margin to 47%, flat with last year.
The call firmed up the margin narrative. Management moved from a 'mid-40s' FRE margin framework to an expectation of a flat full-year margin. It also said margins have 'troughed', which would make 2026 the first stable margin year in several. Fee-paying AUM reached $35.2 billion, up 21%, compared with 19% growth in Q2 and 18% in Q1. Fundraising and deployment rose to $1.3 billion from $1.1 billion in Q2, lifting the year-to-date total to a record of nearly $4.5 billion. Management reaffirmed its $10 billion 2026-27 fundraising target and its $50 billion 2029 FPAUM goal. TrueBridge was the standout. Its FPAUM rose 32%, Venture Secondaries II closed above $500 million, more than double Fund I, and the flagship primary vintage has raised $851 million. Cross-selling has contributed about $1.7 billion since mid-2024, roughly 15% of fundraising, up from $1.2 billion and just over 10% in Q1.
Bears have legitimate ammunition. Excluding the Stellus acquisition, organic FPAUM growth was 11%, about half the headline rate. The core fee rate slipped to 99 basis points from 100, which management attributed to seasonality and fundraising pushed into Q4. Yet the 103 bp full-year guide was held, and hitting it implies a steep fourth-quarter step-up, possibly above 110 bp. Catch-up fees total only $2.1 million year-to-date against a $6-8 million full-year guide. Some closes slipped from Q3 into Q4. Funds in market fell to roughly 15 from about 20. Management also described credit deployment as 'somewhat muted', citing rate moves, software/SaaS concerns and geopolitics. Forward catalysts are real but sit mostly in 2027: the next TrueBridge flagship vintage and the fifth Stellus fund family with related SMAs are both slated for early 2027.
Capital return added support. RPC repurchased about 1.78 million shares at an average of $8.36, roughly $15 million, up from $6 million in Q1. The board added $30 million of authorization, and leverage eased to 2.7x from 2.8x. The quarterly dividend remains $0.04.
The market setup is more complicated than the miss implies. Investor sentiment remains negative but improved meaningfully, rising from -0.60 to -0.42. Shares closed at $9.40 ahead of the report, almost exactly where they opened after the August release ($9.43). That flat comparison hides a sharp round trip. The stock fell to an inter-earnings low of $7.23 in late September, then rallied about 30% to finish within 4% of the $9.79 high set just two days before earnings. It also sits nearly 27% above its 200-day moving average. Momentum and AVWAP trend readings are positive, while sequential growth is neutral. A stock that ran this hard into a headline miss leaves less cushion if the Q4 back-loading looks shaky.
The bottom line is that RPC missed on the reported numbers while delivering accelerating fee growth, a credible margin trough call and a record fundraising year. The investment case now rests on fourth-quarter execution. The slipped closes need to land, the fee rate needs to jump toward the 103 bp guide, and catch-up fees need to materialize. If they do, the miss will look like timing. If they don't, a stock priced near its quarterly high will have little margin for disappointment.
Read our earnings preview for Ridgepost Capital, Inc.: https://www.earningswhispers.com/article/RPC/22005
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-14 | |
| Aug-11 | |
| Aug-05 | |
| Aug-05 | |
| Jul-17 | |
| Jul-16 | |
| Jun-22 | |
| Jun-16 | |
| Jun-09 | |
| Jun-08 | |
| May-19 | |
| May-07 |
