Matrix Service Must Prove Margin Gains Can Outrun A Shrinking Backlog Without Guidance
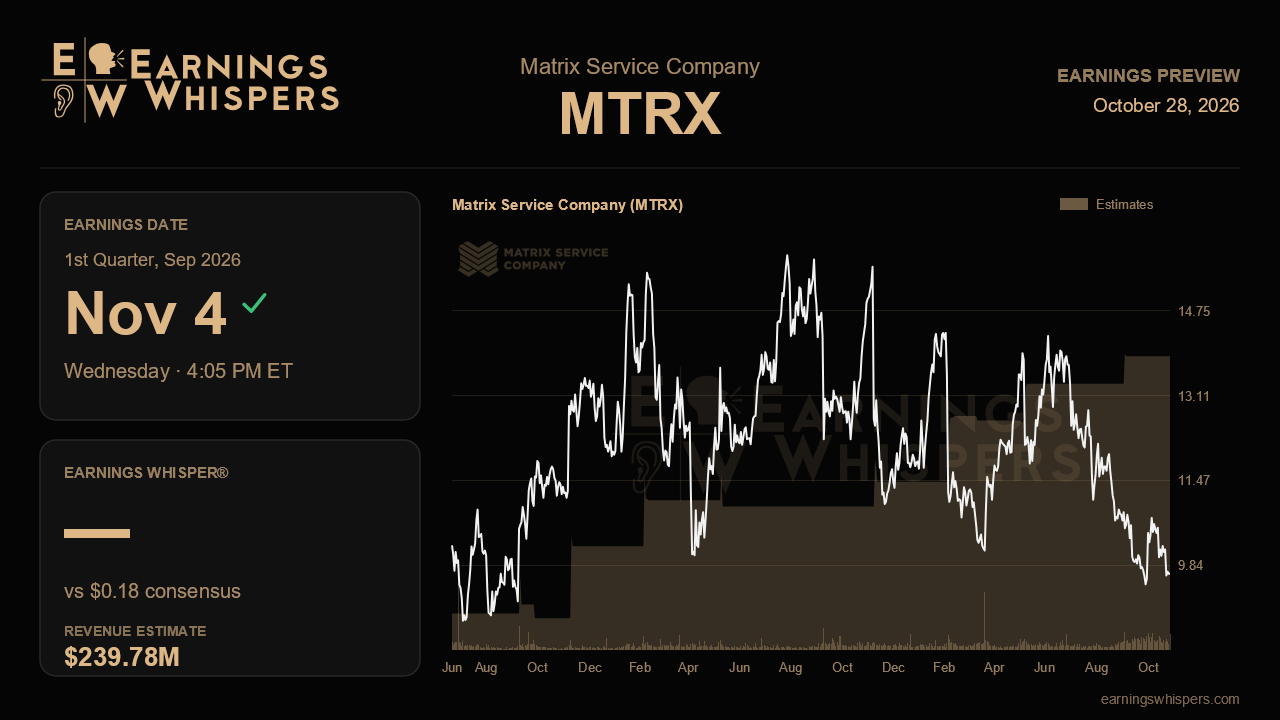
Matrix Service enters its fiscal first-quarter report with a split personality. On the income statement, the industrial contractor has finally started to look like a business that can make money, posting two straight profitable quarters and a gross margin near 8%. On the balance sheet of future work, though, backlog has slid for four consecutive quarters, and management pulled its outlook entirely pending a new chief financial officer. The report due after the close on November 4 is the first real look at whether the profitability turn can hold up while the company operates without a public roadmap.
The Street is asking for earnings of $0.18 per share on revenue of $239.8 million. That revenue figure is up about 13% from the $211.9 million of a year ago, when Matrix lost a penny a share, which explains the eye-catching expected EPS growth rate. The more useful comparison is sequential. Analysts are modeling slightly less revenue than the $244.5 million delivered last quarter but a couple of cents more profit than that period's adjusted $0.16. In other words, consensus assumes margins keep improving even as the top line flattens. With no company guidance to anchor that view, the estimate rests entirely on analysts extrapolating last quarter's execution, and that leaves little room for a stumble on project mix or one-time costs.
The most important numbers will be new awards and backlog. Matrix exited the fiscal year with $953 million in backlog, down from about $1.2 billion in the first quarter, and fourth-quarter book-to-bill was just 0.7. Management pointed to several sources of replenishment: a significant mining and minerals award that drove a 3.2 book-to-bill in Process and Industrial Facilities, data-center substation work in Northern Virginia and eastern Pennsylvania, and an opportunity pipeline in which LNG and NGL projects now make up more than 40%. The marquee item, the storage tank farm FEED for America First Refining in Brownsville, is not expected to convert into sizable backlog until late in fiscal 2027, so it should not move this quarter's figures. A book-to-bill at or above 1.0 would go a long way toward validating the idea that the award drought is ending. Another sub-1.0 quarter would sharpen concerns about revenue in the back half of the fiscal year.
Segment detail matters too. Storage and Terminal Solutions carried the prior quarter with 43% growth, and Utility and Power margins reached 12.8%. Process and Industrial, by contrast, saw revenue fall sharply and margin compress to 2.9%. Evidence that the new mining work is lifting that segment's volume and profitability would strengthen the recovery story. Investors should also look for clarity on cash usage, which management warned would be negative in the first half, on progress in the CFO search, and on whether the stock buyback under evaluation becomes an actual authorization backed by roughly $223 million of cash and no debt.
The market has not given Matrix much credit for its turnaround. Shares are down 6.7% since the last report, trailing the S&P 500 by nearly seven points, and at $9.67 they sit well below the 200-day moving average of $11.85 and only about 3% above the post-earnings low of $9.38. The entire trading range has shifted lower from the prior quarter, when the stock ranged between $10.61 and $14.28. Sentiment has also turned more bearish than it was heading into the last report. That combination suggests skepticism is already priced in, though it does not guarantee a favorable reaction.
Ultimately, this quarter hinges on whether Matrix can show that its improved margins are durable and that awards are beginning to refill a thinning backlog. Hitting the earnings estimate alone may not be enough. A return to book-to-bill above parity, steady margins near last quarter's level and some restored visibility on guidance would keep the turnaround narrative intact, while another backlog decline would leave the recent profitability looking like a peak rather than a foundation.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-19 | |
| Oct-19 | |
| Sep-03 | |
| Sep-02 | |
| Sep-02 | |
| Sep-02 | |
| Aug-18 | |
| May-21 | |
| May-20 | |
| May-18 | |
| May-06 | |
| May-06 | |
| Apr-30 | |
| Apr-21 |
