Matrix Service Beats On EPS, But A Stock-Comp Tailwind, Revenue Miss, And Shrinking Backlog Undercut The Quarter
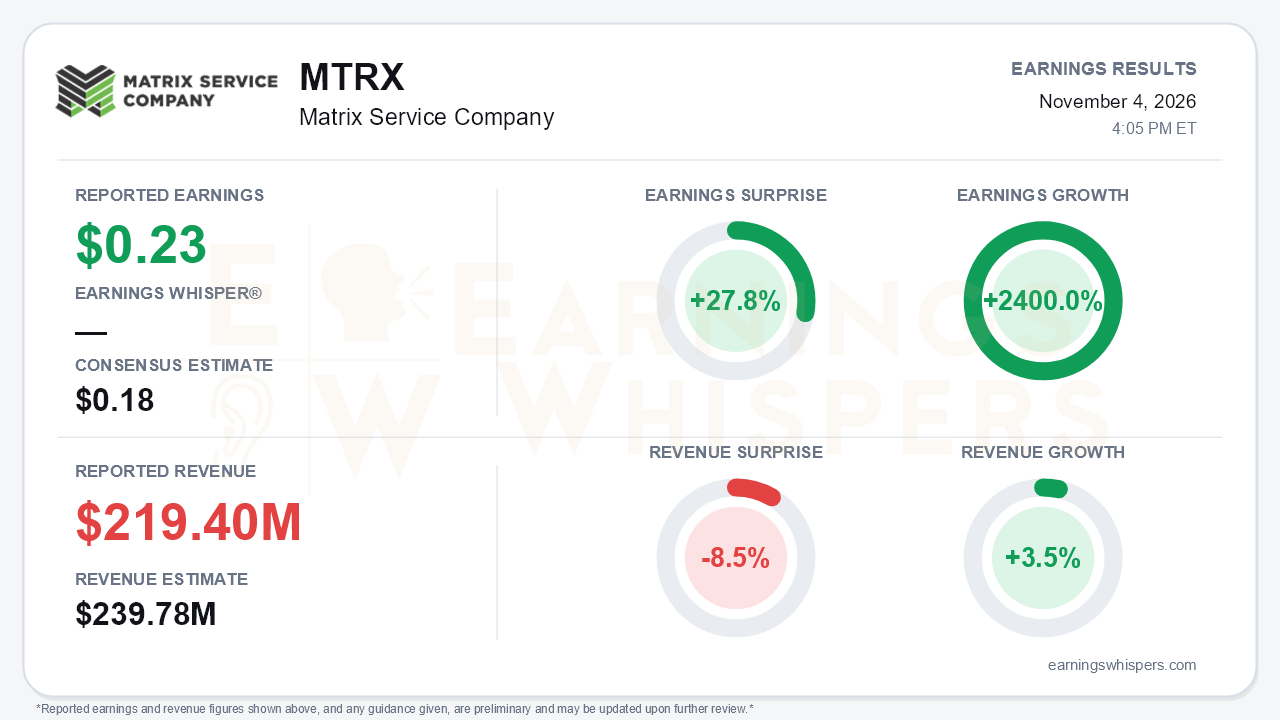
Matrix Service Company delivered a third consecutive profitable quarter in fiscal Q1 2027, reporting adjusted earnings of $0.23 per share against a $0.18 consensus, a 27.8% beat. Earnings grew 2400.0% year over year, a swing from an adjusted loss of $(0.01) a year ago, and the result improved sequentially from $0.16 in Q4 and $0.13 in Q3. Revenue told a different story. Sales of $219.4 million rose 3.5% year over year but missed the $239.78 million consensus by 8.5% and fell from $244.5 million in the prior quarter. The central tension is that profitability is clearly improving while the forward revenue base keeps eroding. Backlog fell again, and the earnings beat leaned partly on factors that will not repeat.
The quality of the beat deserves scrutiny. Gross margin expanded to 8.2% from 6.7% a year ago and 8.0% in Q4, a real operating gain driven by Storage and Terminal Solutions. That segment's margin reached 9.0%, up from 5.9% a year earlier, on better execution and overhead absorption. Below gross profit, however, SG&A fell to $13.3 million, and $1.9 million of that decline came from variable accounting on cash-settled stock compensation, largely because Matrix's own share price fell. That benefit alone exceeds the dollar value of the beat against consensus. Management's normalized SG&A run rate of $15.5 to $16 million also implies Q1 costs were flattered. Interest income of nearly $2.0 million made up a large share of the $6.2 million in pretax income, and valuation allowances kept the tax line near zero. Operating income of $4.5 million is a genuine turnaround from a $5.5 million loss, but the earnings power is thinner than the headline suggests.
The call preserved a credible longer-term growth story while conceding near-term softness. The opportunity pipeline rose roughly 11% to $8.2 billion, a new high, with growth across LNG, power generation, electrical, and mining. New wins included a limited notice to proceed on a data-center-related power generation project, additional mining and minerals work, and front-end engineering for the tank farm at the planned America First Refining facility in Brownsville. Management said revenue in the remaining FY27 quarters should average above Q1's level. Still, awards of just $138.8 million produced a 0.6x book-to-bill, down from 0.7x in Q4 and 0.8x in Q2. Storage and Terminal, the company's largest and most profitable segment, booked only 0.2x. Total backlog fell to $873 million from $953 million last quarter and about $1.1 billion two quarters ago. Some booked revenue also slipped into future periods again.
The mix beneath the segments is also shifting unfavorably in places. Utility and Power Infrastructure revenue dropped 21% as natural gas peak-shaving work rolled off, and segment margin slid to 8.6% from 12.8% in Q4 and 13.6% in Q3. Process and Industrial Facilities grew on mining volume, but its margin fell to 3.7% because of a legacy subcontractor dispute settlement. Management argues that settlement will be offset by lower legal costs. The bigger risk is timing. Management now frames the large LNG and storage awards, including America First Refining, as mainly FY28 revenue drivers, with decisions expected in the back half of FY27. Labor tightness and an unclear answer on margins for new work add uncertainty, and Matrix still offers no formal guidance.
Cash is the other pressure point. Operating activities consumed $37.0 million in the quarter as payables and advance billings unwound, and cash fell to $182.4 million from $223.0 million. Liquidity declined to $221.8 million from roughly $284 million a quarter earlier. The debt-free balance sheet remains a real asset. It supports a new $25 million buyback authorization, and the company has already repurchased $2.5 million of stock. The appointment of a permanent CFO, effective November 6, removes an overhang.
Investors were not buying the improvement story going into the print. Sentiment remained negative and weakened further, moving from -0.45 to -0.56. Shares have fallen 11.9% since the open after the September report to $9.13, leaving them 22.3% below the 200-day moving average of $11.75. The Earnings Whispers price and AVWAP trend readings are negative, while sequential-growth and momentum readings are neutral, consistent with a market that has been discounting the backlog decline rather than rewarding margin gains.
The bottom line is that Matrix is executing better, with higher margins, consistent profits, and a record pipeline. But a meaningful part of this quarter's beat came from a stock-price-driven compensation benefit, and the revenue miss, 0.6x book-to-bill, and shrinking backlog give bears legitimate ammunition. Until the large awards management is pointing to actually convert to backlog, the margin story is running ahead of the revenue foundation needed to sustain it.
Read our earnings preview for Matrix Service Company: https://www.earningswhispers.com/article/MTRX/22024
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-19 | |
| Oct-19 | |
| Sep-03 | |
| Sep-02 | |
| Sep-02 | |
| Sep-02 | |
| Aug-18 | |
| May-21 | |
| May-20 | |
| May-18 | |
| May-06 |
