Fortuna's Cost Retreat Faces Its First Test As Growth Plans Move Into Execution
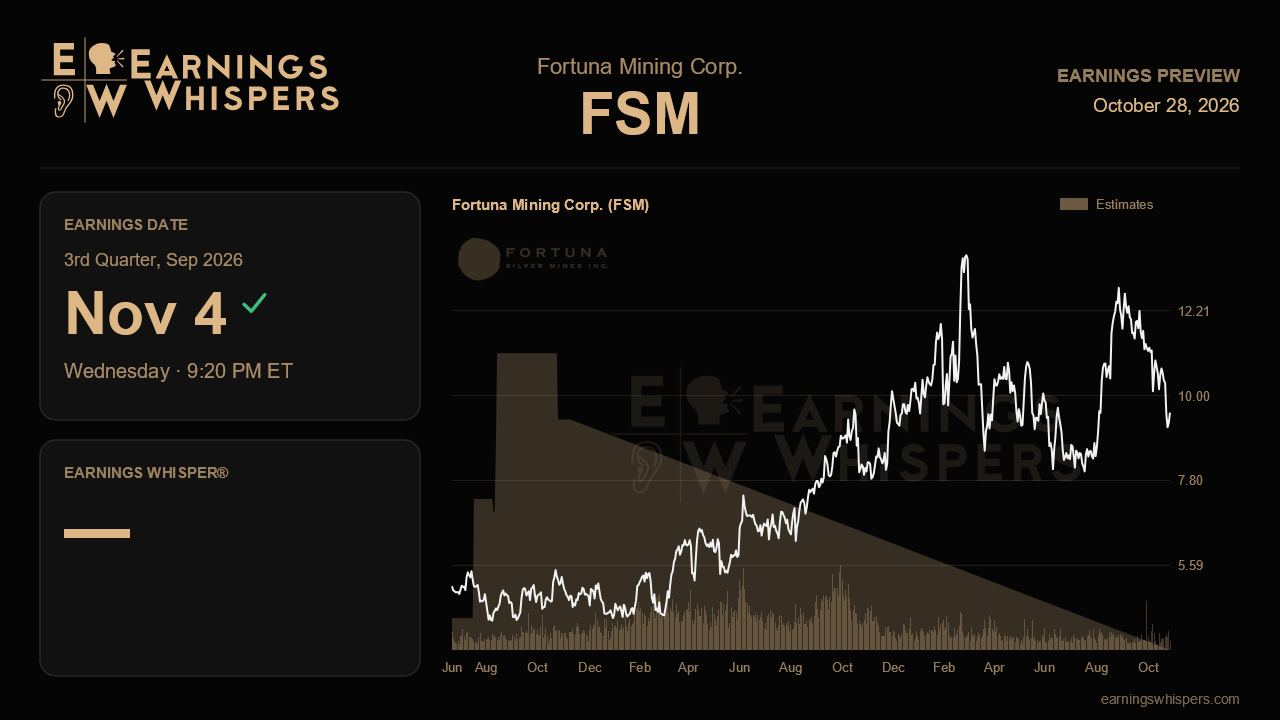
Fortuna Mining enters its third-quarter report with a credibility test on costs. Last quarter, management laid out the most confident growth story in years, with the Seguela expansion sanctioned and the Diamba Sud feasibility study published. It also asked shareholders to treat a jump in costs as temporary. The November 4 release, due after the close, is the first chance to check whether that framing holds. If all-in sustaining costs drift back toward the roughly $2,000 per ounce level management signaled for the second half, the expansion story keeps its footing. If they do not, the market may start to question how much of the margin squeeze was really one-time.
The published consensus figures do not offer a usable benchmark this time, so year-ago and prior-quarter results serve as the better yardsticks. A year ago, Fortuna earned $0.15 per share on $251.4 million in revenue. Last quarter it posted $0.24 on $318.4 million, a 34% sales increase that came largely from gold prices far above year-earlier levels. Even after slipping from the first-quarter record, the realized price was still about $4,447 an ounce. Another clear gain over the year-ago period looks plausible on pricing alone. The more useful question is how much of that price advantage reaches the bottom line once costs, taxes and capital spending are counted.
That is where the second-quarter call matters most. Consolidated ASIC rose to $2,157 an ounce and cash costs climbed above $1,000. The bulk of the damage was concentrated at Lindero in Argentina, where ASIC jumped from $1,783 to $2,265. Management traced roughly $115 per ounce of the group-wide increase to a crusher refurbishment it described as non-recurring. Results that show Lindero easing back toward its first-quarter cost profile would validate that explanation. Results that show peso strength, diesel and inflation still lifting costs would undercut it. Those three items added about $65 per ounce and are largely outside the company's control. Management has already warned that such pressures, along with price-linked royalties, could threaten its three-year cost guidance.
Free cash flow is the other figure to examine closely. It halved sequentially to $85.7 million, but much of that reflected $79.3 million in cash tax payments and heavier capital spending. Management characterized the tax hit as a matter of timing. A rebound would support that view, especially with a 46% effective tax rate and Argentine deferred tax charges still flowing through 2026. Cash generation also matters for capital returns. Buybacks surged to a record $82 million last quarter, and keeping that pace while funding Seguela, the $48 million Sunbird underground project and a lifted $60 million to $65 million exploration budget would reinforce the claim that growth is fully funded without issuing shares. Updates on the Diamba Sud investment decision targeted for the second half and early drilling in Guyana would show whether the path toward more than 500,000 ounces a year by mid-2028 is staying on schedule. Safety at Seguela, following a fatal contractor accident, also deserves attention.
Market positioning looks cautious rather than euphoric. Sentiment remains bearish but has improved from the prior quarter's reading. The stock has edged up 2.3% since the last report, slightly ahead of a flat S&P 500, yet at $9.56 it sits below its 200-day moving average of $10.33. That leaves it much closer to the $8.93 low of its post-earnings range than to the $12.94 high. That gap suggests investors have not fully priced in the growth story, which lowers the bar somewhat for a constructive reaction.
Ultimately, this report hinges on whether second-quarter cost inflation proves to have been a peak or the start of a new baseline. Lower unit costs, recovering free cash flow and steady buybacks would let the expansion narrative carry the stock. Sticky Argentine costs would leave Fortuna asking investors to look past near-term margins for longer than they may be willing to.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-22 | |
| Oct-20 | |
| Oct-13 | |
| Oct-09 | |
| Oct-07 | |
| Sep-24 | |
| Sep-24 | |
| Sep-22 | |
| Sep-16 | |
| Aug-26 | |
| Aug-26 | |
| Aug-20 | |
| Aug-18 | |
| Aug-14 |
