Fortuna's Third Straight Earnings Decline Meets A De-Risked Growth Pipeline As AISC Guidance Slips And Buybacks Pause
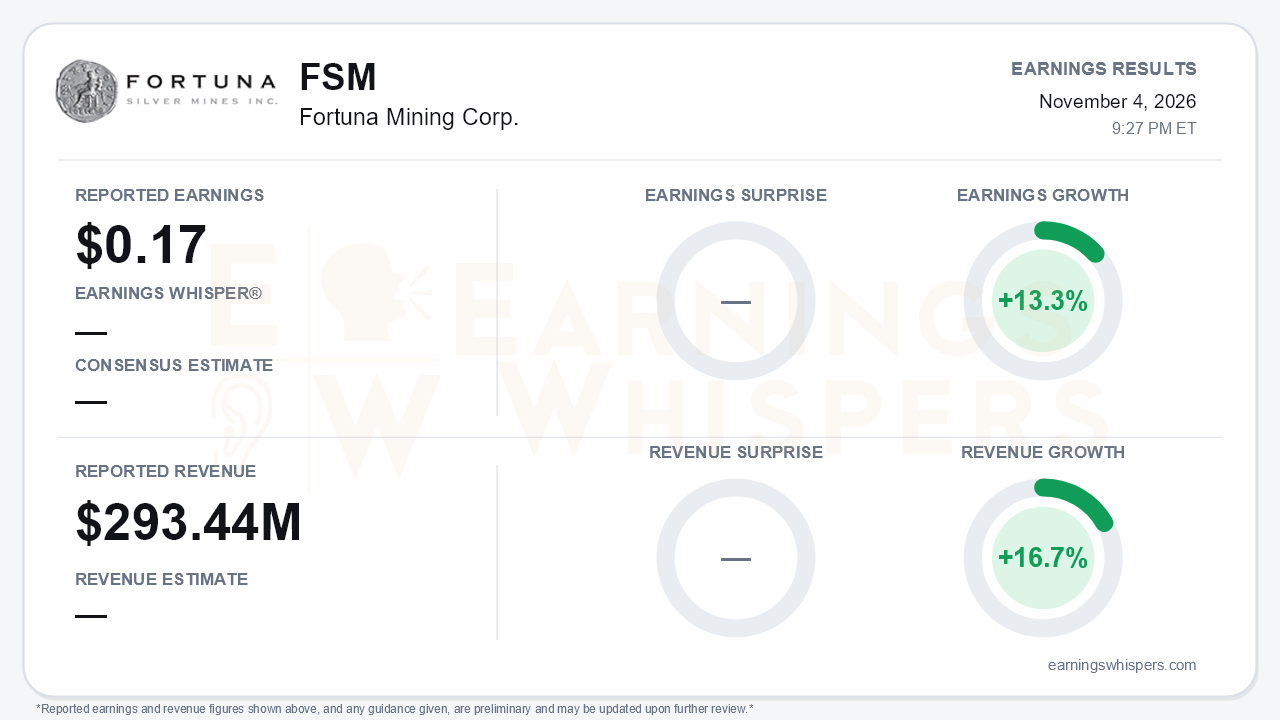
Fortuna Mining Corp. (NYSE: FSM) reported third-quarter adjusted earnings of $0.17 per share on revenue of $293.44 million. Earnings Whispers' normalized figures show earnings up 13.3% year over year and revenue up 16.7%, but the year-over-year comparison flatters a business that is losing momentum quarter to quarter. Adjusted EPS has fallen from $0.36 in Q1 to $0.25 in Q2 and now $0.17. Adjusted EBITDA dropped from a record $219 million to $200 million and then to $165 million. Revenue growth also cooled sharply: sales rose 41% over the first nine months, but the third-quarter gain was 16.7%, and sales fell from $318.4 million in Q2. No consensus figure was available, so there is no surprise to judge. That is the central tension: a softening operating quarter and higher cost outlook set against the clearest progress yet on a growth plan targeting 60% more gold production from mid-2028.
The quality of the quarter deserves scrutiny. The company's own adjusted attributable net income was essentially flat year over year at $51.2 million versus $51.0 million. That contrasts with the normalized growth figure, and investors should note the gap. Reported attributable EPS from continuing operations fell to $0.16 from $0.40, although the prior-year figure included a $52.7 million impairment reversal at Lindero. More telling is the cost trajectory. Consolidated cash cost per gold equivalent ounce jumped to $1,244 from $1,034 in Q2 and $942 a year ago. AISC climbed to $2,286 from $2,157. Realized gold of $4,281 per ounce, down from $4,447 in Q2, still sits well above last year's $3,467, but higher prices are no longer outrunning costs. EBITDA margin compressed to 56% from 63% sequentially. Free cash flow from ongoing operations was the bright spot at $90.8 million, up from $85.7 million, though that improvement came from lower sustaining capital rather than stronger operating cash flow.
Séguéla was the problem. Production fell to 33,744 ounces from about 41,700 in Q2. The causes were reduced contractor equipment availability and a roughly six-day site-wide blockade by artisanal miners. Head grade dropped 11% year over year to 2.67 g/t, and the strip ratio hit 19.1:1. Management now guides the mine only to the low end of its range. On the call, the company said consolidated full-year AISC will land 8-10% above the top of guidance. In Q2, management had suggested roughly $2,000 per ounce was plausible. The release attributes about $220 per ounce to external factors versus guidance assumptions:
- $116 from share-based compensation
- $45 from Argentine peso effects
- $42 from consumable prices
At Lindero, diesel is up about 60% and explosives about 30%. Depletion of $866 per ounce, up from $609, is expected to persist into Q4. Lindero itself delivered what earlier calls promised: 26,024 ounces, up 25% sequentially, with AISC down 18.5% sequentially. Caylloma is set to exceed guidance, and overall production guidance of 281-305koz GEO was maintained.
The forward catalysts are substantive. Diamba Sud received its Notice of Admissibility on November 2, and the exploitation permit and Mining Convention are expected in Q4. The board authorized $250 million in contract commitments, about 60% of capex, ahead of the permit, and a construction ceremony is planned for late November. The $109 million Séguéla plant expansion targets over 200,000 ounces annually from the second half of 2028. The Sunbird Underground has its environmental permit. The Bambadji acquisition adds district-scale upside next to Diamba Sud. The release cites $200 million in cash consideration while the call referenced $206 million, likely reflecting differing cost definitions. The price of this pipeline is visible on the balance sheet. Net cash fell to roughly $260 million from $434 million in Q2. Buybacks went from $82 million in Q2 to zero and are paused for at least two quarters as roughly $750 million of two-year growth spending ramps. Permitting timing in Senegal and the final Mining Convention terms remain execution risks, and bears have legitimate ammunition in the cost overrun and cash drawdown.
Investor sentiment improved meaningfully, moving from mildly negative (-0.18) at the prior report to slightly positive (+0.06). The stock has done little since the last report, up just 2.6% from the post-report open to $9.59. It remains 6.9% below its 200-day moving average of $10.30, so the market has not rewarded the growth milestones while near-term earnings slide. The Earnings Whispers trend readings are mixed, with momentum positive but AVWAP still negative.
The bottom line is that Fortuna's quarter separated two stories. Operationally, earnings, margins and cost guidance all moved the wrong way for a second straight quarter, and capital returns have been shelved. Strategically, the call preserved a credible growth narrative as Diamba Sud moves to the edge of construction. Until Séguéla delivers the promised strong fourth quarter and costs stabilize, the market setup is likely to remain more complicated than the improving sentiment implies.
Read our earnings preview for Fortuna Mining Corp.: https://www.earningswhispers.com/article/FSM/22018
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Nov-02 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-13 | |
| Oct-09 | |
| Oct-07 | |
| Sep-24 | |
| Sep-24 | |
| Sep-22 | |
| Sep-16 |
