Traeger Heads Into A Steep Q3 Revenue Drop As Lowe's Transition Tests Its Cut Outlook
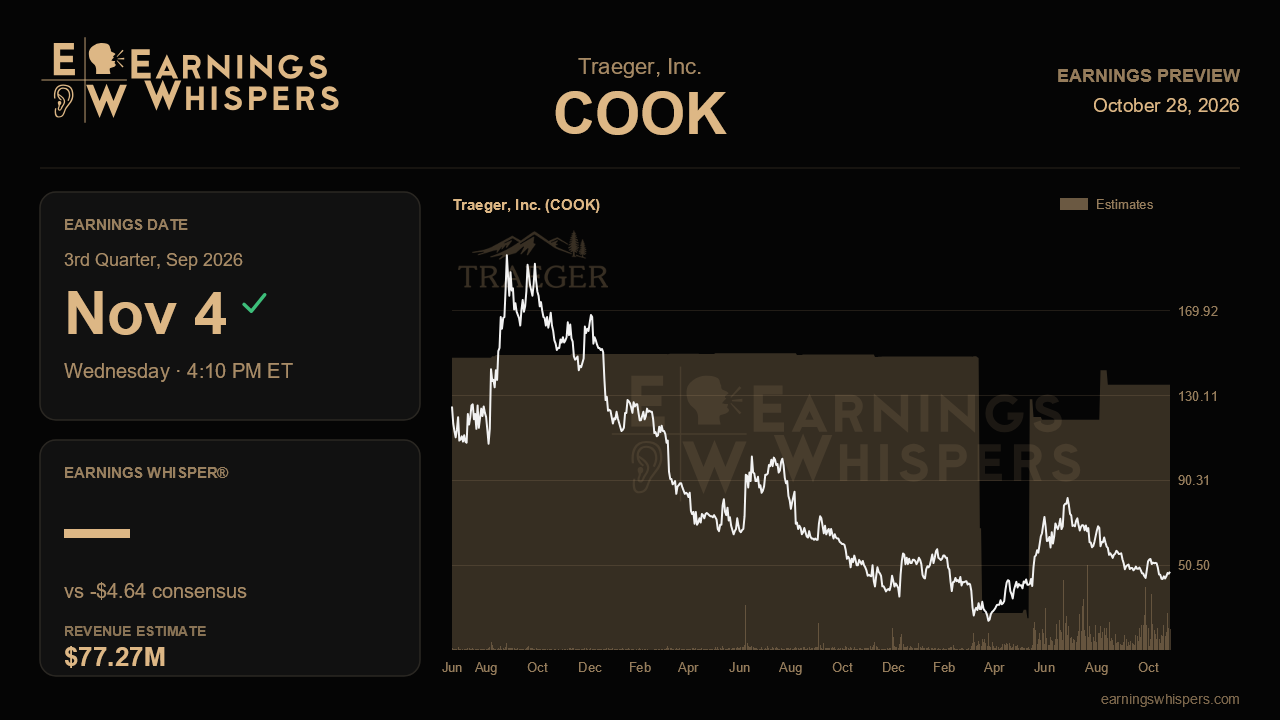
Traeger enters its third-quarter report in an awkward middle stage of a strategic pivot. Last quarter, management cut its full-year sales outlook for the first time this cycle and blamed it partly on friction from its own decision to move into Lowe's nationally. Since then, the market has delivered its verdict: the shares have fallen nearly 32% while the S&P 500 was essentially flat. The November 4 report, due after the close, is the first real chance to see whether the transition pain is behaving as management described or spreading further than planned.
The Street is braced for a deep contraction. Consensus calls for revenue of about $77.3 million, down roughly 38% from $125.4 million a year ago and well below the $120.2 million posted last quarter. The consensus loss of $4.64 per share looks alarming next to the $0.43 loss last quarter and $0.19 a year earlier, but the per-share figure appears to be on a different basis than those historical numbers, so adjusted EBITDA and gross margin are the more useful scorecards here. On the full year, management now guides to $435 million to $465 million in revenue, down from $465 million to $485 million. Annual consensus of roughly $470.7 million still sits above even the top of that reduced range, which suggests some estimates have not fully caught up. That gap leaves room for further downward revisions even if Traeger simply lands inside its own guidance.
The central claim from last quarter was that the revenue cut was largely self-inflicted rather than a sign of collapsing demand. Management pointed to weaker-than-expected promotions for its Meater thermometer line and to existing retail partners pulling back as exclusive arrangements shifted around the Lowe's deal. A sharply lower third quarter is consistent with that story. What would validate it is evidence that the shortfall is concentrated in channel offsets and Meater, while grill sell-in units track management's expectation of roughly flat volume, helped by the lower-priced Westwood and Irontop platforms. What would challenge it is broader weakness in grills or consumables, or commentary that the long-awaited replacement cycle remains out of reach and category demand is sliding rather than merely flat.
Profitability is where Traeger has earned some credibility. Gross margin guidance has been raised twice, to 40% to 41%, helped by lower tariff costs and a $16 million tariff refund, and the adjusted EBITDA target of $57 million to $67 million survived the revenue cut intact. Project Gravity cost savings, falling inventory and year-to-date free cash flow already above the full-year floor support that discipline. The catch is timing. Management said about two-thirds of remaining revenue and nearly all remaining EBITDA fall in the fourth quarter, which means a soft third quarter tells investors little unless it is accompanied by a confident read on the Lowe's load-in and holiday sell-through. A reaffirmed EBITDA range would carry more weight than any single quarterly figure; a trim would suggest the cost story is no longer fully offsetting the top line. Investors should also separate the one-time refund from underlying margin progress.
Sentiment has cooled from modestly bullish ahead of last quarter to roughly neutral with a slight bearish tilt, and the stock trades at $47.44, below its 200-day moving average near $50.90 and in the lower part of its post-earnings range between $42.80 and $69.50. Expectations are subdued, but not so washed out that another guidance cut would be shrugged off.
The issue that will decide whether the narrative holds is whether Traeger can show the fourth-quarter ramp is real: Lowe's shelves filling on schedule, legacy partners stabilizing and the EBITDA target intact. If management can demonstrate that, the transition-year framing survives. If the back-half math slips again, the market will likely treat the Lowe's expansion as a 2027 hope rather than a 2026 bridge.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-21 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-22 | |
| May-12 | |
| May-11 | |
| May-11 | |
| May-08 | |
| Apr-28 | |
| Apr-27 | |
| Apr-14 | |
| Mar-12 |
