Advance Auto Parts Must Show DIY Slump Was A Blip As Profits Expected To Shrink
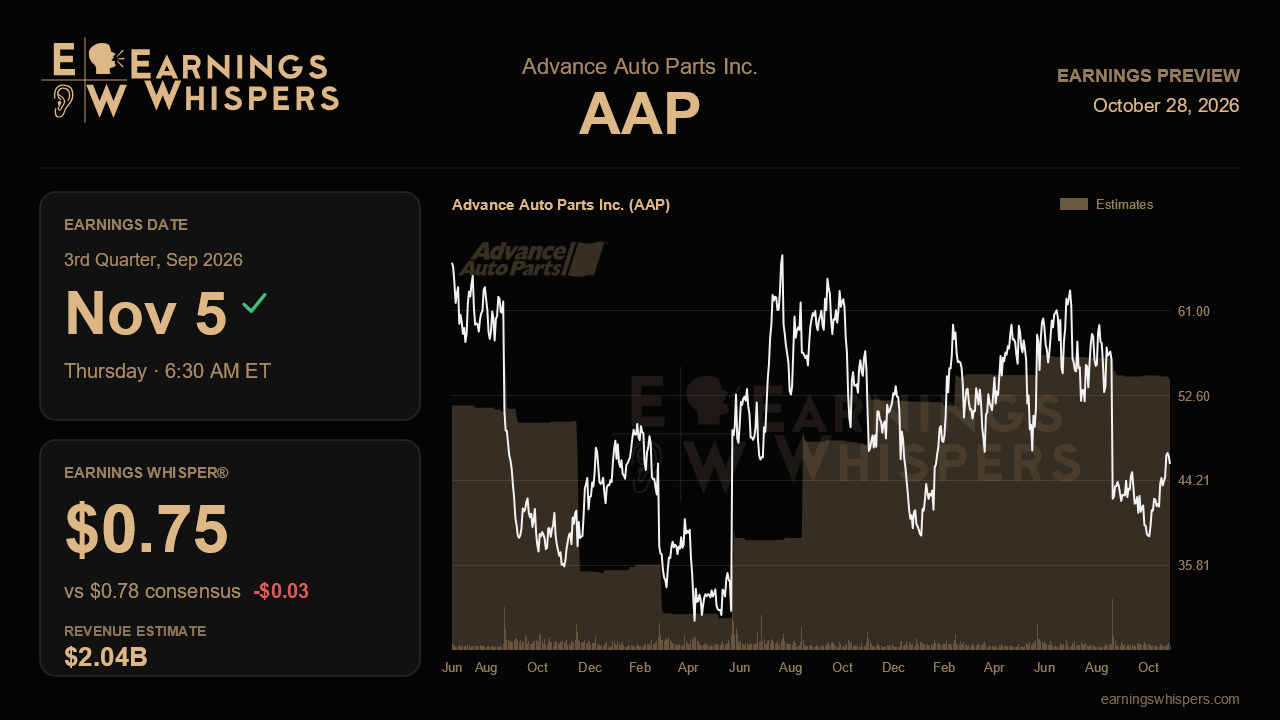
Advance Auto Parts heads into its third-quarter report with a split personality. The self-help side of the turnaround, from distribution center consolidation to free cash flow, has been delivering. The demand side has not. Last quarter, a sudden stall in do-it-yourself traffic over the final four weeks erased the momentum of a first quarter that management had called its best in five years. The November 5 release, due before the open, is the first real chance to learn whether that late-summer slide was a weather-and-budget hiccup or the start of a longer slowdown.
The Street is not asking for much. Consensus calls for earnings of $0.78 a share on revenue of $2.04 billion. That would mean sales essentially flat with a year ago and earnings down about 15% from $0.92. The Earnings Whisper sits a touch lower at $0.75, which hints that the more skeptical crowd sees modest downside but does not signal a dramatically lower bar. For the full year, management raised its earnings outlook to $2.60 to $3.30 a share. The roughly $2.94 consensus sits almost exactly at the midpoint. The more telling detail is revenue. The Street's $8.58 billion annual estimate is at or slightly above the top of the company's $8.485 billion to $8.575 billion range. That leaves little room for further top-line disappointment.
That tension matters because last quarter's guidance raise was not an operating story. The higher earnings range leaned on roughly $100 million of interest income, up from about $80 million, plus tariff refunds. Core targets were simply held: comparable sales growth of 1% to 2%, adjusted operating margin of 3.8% to 4.5%, and free cash flow near $100 million. With first-half comps averaging out to modest growth after a strong first quarter and a slightly negative second, reaching that comp range requires the back half to return to low-single-digit growth. A third quarter that shows DIY still declining, while same-SKU inflation near 4% squeezes lower and middle-income households, would make the comp guide look stretched.
The Pro business is the counterweight. It grew in the low single digits last quarter, and Main Street Pro outpaced the total Pro channel by more than 200 basis points. Continued Pro growth would support the case that service improvements are winning share. Those gains include time-to-serve under 40 minutes, a net promoter score near 80, and higher attach rates. Margins are the other test. Gross margin excluding tariffs came in slightly below plan, pressured by DIY mix and freight and fuel costs. Merchandising had added about 100 basis points to product margin. Holding that gain while the new pricing framework rolls out toward year-end would validate the playbook. Further gross margin slippage would challenge it. Cash matters too. With $120 million of year-to-date free cash flow already exceeding the full-year target, any reaffirmation implies a softer fourth quarter that management should explain. Updates on store openings, already cut to 30 to 35, and on the carrier rebid savings promised for 2027 will indicate whether the longer-dated margin ambitions remain credible.
The market has been unforgiving. Shares are down about 2% since the last report while the S&P 500 edged higher. The trading range has also shifted sharply lower, from roughly $51 to $63 last quarter to about $38 to $47 since. At $45.83, the stock has rebounded toward the upper part of that range. It still sits below its 200-day moving average near $51.67, so the longer-term trend remains damaged. Sentiment is mildly bearish and only a shade gloomier than before the prior report, suggesting caution rather than capitulation.
Ultimately, the quarter hinges on whether Advance can show that cost discipline is still outrunning a fragile consumer. If DIY stabilizes and the full-year comp and margin targets survive intact, the turnaround narrative holds. If demand weakness has persisted and guidance holds only through interest income and refunds, investors may conclude the operating story is losing ground beneath the headline numbers.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-15 | |
| Sep-25 | |
| Sep-22 | |
| Aug-24 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 |
