Advance Auto Parts Beats On EPS, But A Revenue Miss And Softer Comp Guidance Undercut A Late-Quarter Sales Inflection
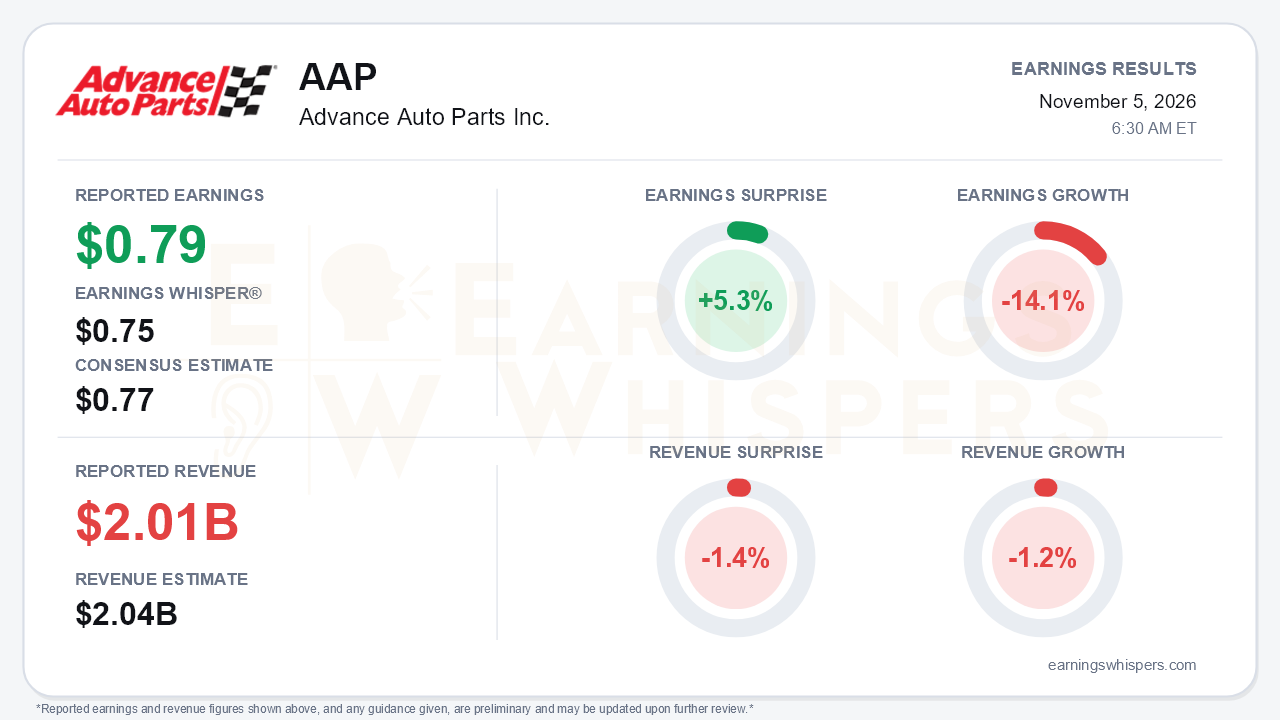
Advance Auto Parts (NYSE: AAP) cleared a low bar in the third quarter, but the beat is less convincing than it looks. Adjusted EPS of $0.79 topped the $0.77 consensus and the $0.75 Earnings Whisper number, a 5.3% surprise. Revenue of $2.012 billion missed the $2.04 billion consensus by 1.4% and fell 1.2% from a year ago, and earnings declined 14.1%. Management trimmed full-year comparable sales guidance to approximately 1%, the low end of the prior 1% to 2% range. It also raised free cash flow guidance to approximately $150 million from approximately $100 million. That is the central tension: sales exited the quarter on a stronger trajectory, but the full-year growth outlook was cut and per-share earnings are still moving backward.
The quality of the beat deserves scrutiny. Operating execution was steady rather than strong. Adjusted operating income was $91 million, essentially flat with $90 million a year ago, and adjusted operating margin edged up 10 basis points to 4.5%. That margin was held together by cost discipline: adjusted SG&A fell to $808 million from $823 million. Adjusted gross margin slipped to 44.7% from 44.8%, which management blamed on product and channel mix and supply chain deleverage. The year-over-year EPS decline came largely below the operating line. Interest expense rose to $46 million from $40 million, and a higher tax rate cut adjusted net income to $48 million from $56 million. On a GAAP basis, the comparison flatters. Diluted EPS swung to $0.25 from a $0.02 loss, though $44 million of restructuring and impairment charges still separated GAAP from adjusted results.
The sales cadence is the bullish part of the story. Comparable sales fell 1.2% for the quarter, but the trend improved steadily. Comps ran roughly -2% in the first eight weeks and turned positive in the final four, a meaningful recovery from about -3% in late Q2, when DIY was running near -7%. The Pro channel grew at a low-single-digit rate and reached roughly 3% in the final four weeks. Main Street Pro continued to outperform, although its lead over total Pro narrowed to about 100 basis points from more than 200 in the first half. Customer metrics also improved:
- Net Promoter Score rose above 80, versus high-60s a year ago.
- Reliascan diagnostic attachment reached the mid-30% range.
The longer view is less flattering. Comps went from +3.5% in Q1 to a slight decline in Q2 to -1.2% in Q3. DIY traffic among stressed lower- and middle-income consumers remains a structural soft spot, and management described early Q4 DIY trends as "bouncy" and flattish.
The forward picture gives bears legitimate ammunition. The adjusted EPS range narrowed to $2.75 to $3.10 from $2.60 to $3.30, nudging the midpoint slightly lower. The adjusted operating margin range tightened to 4.0% to 4.3%, with the midpoint held. Several cost assumptions also moved the wrong way:
- LIFO expense rose to about $50 million from $40 million.
- The tax rate climbed to about 28%.
- Motor oil and base-stock inflation is not being fully passed through, pressuring gross margin into the first half of 2027.
- Q4 SG&A is expected to grow at a mid-single-digit rate as investments step up.
More importantly, management reframed its targeted 2027 margin expansion of at least 100 basis points. That expansion will now be built off a lower second-half 2026 base, excluding about 30 basis points of tariff refunds and with roughly 50 basis points of cost headwinds persisting. On the positive side, several catalysts are concrete:
- Market hubs reached 46, with 60 targeted by mid-2027.
- Carrier consolidation is expected to save more than 20 basis points in 2027.
- A roughly 100-basis-point national account drag on Pro should fade by early 2027.
The cash flow improvement is real but should be read carefully. Year-to-date free cash flow was $109 million versus negative $277 million last year. That swing was helped by a $94 million payables inflow versus a $270 million outflow, and by a sharp drop in restructuring cash costs to $19 million from $130 million.
Investors were not leaning bullish going in. Earnings Whispers sentiment weakened modestly from -0.07 to -0.13, staying negative and drifting lower. The stock, however, told a more constructive story. Shares rallied 33% off an October 1 low of $38.05 and closed at $50.75 the day before the report, just under the inter-earnings high of $50.84. That leaves the stock up 8.3% since the open after the August report, but still about 2% below its 200-day moving average of $51.79. The trend readings are mixed: price and sequential growth trends remain negative, while AVWAP is positive. Entering the report near the top of its range, AAP needed the late-quarter inflection to carry more weight than a cut comp guide, a revenue miss and softer margin assumptions for 2027.
The bottom line is that Advance Auto delivered a narrow, cost-driven EPS beat alongside a revenue miss and a lower growth outlook. The improving exit rate and higher cash flow guidance keep the turnaround narrative intact, but the 2027 margin story now rests on a lower base and on DIY demand that has yet to stabilize. With the stock having rallied hard into the print against slightly weaker sentiment, the setup is more complicated than the earnings surprise implies.
Read our earnings preview for Advance Auto Parts Inc.: https://www.earningswhispers.com/article/AAP/22031
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 7 hours | |
| 8 hours | |
| Oct-28 | |
| Oct-15 | |
| Sep-25 | |
| Sep-22 | |
| Aug-24 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 |
