Stoneridge Must Prove Its Turnaround Survives A Softer Quarter As Shares Slide Toward Lows
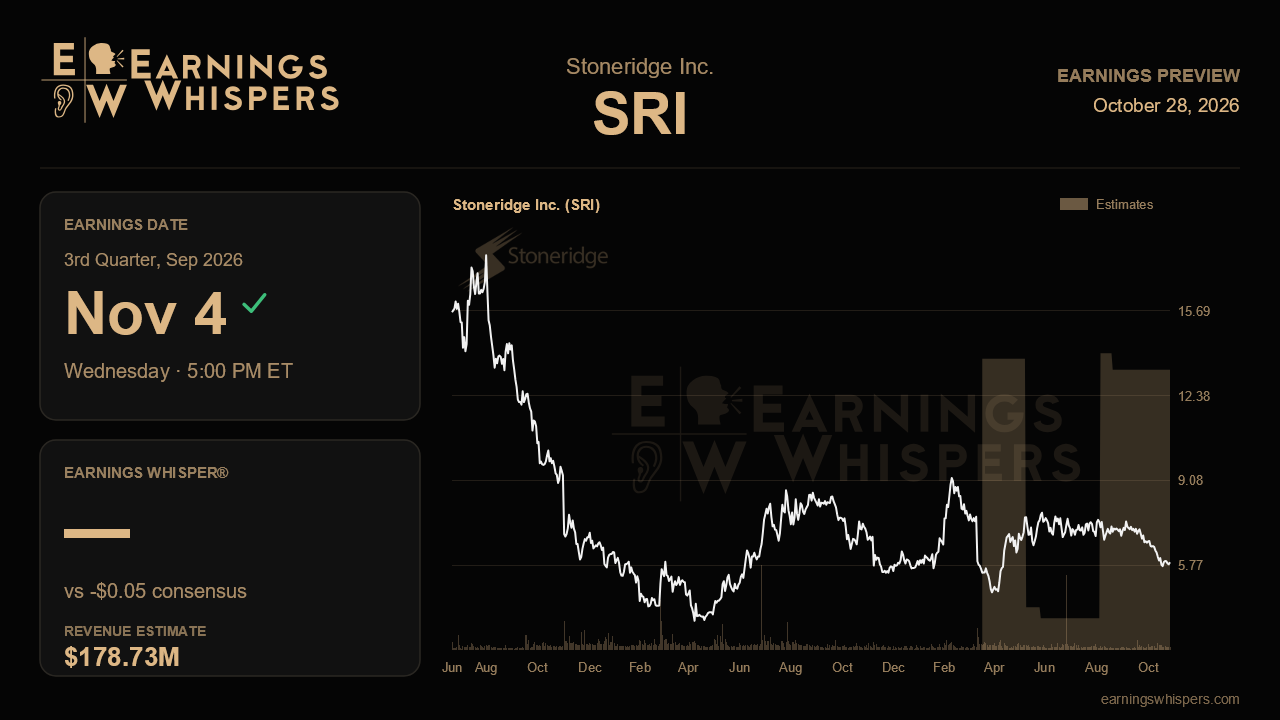
Stoneridge heads into its third-quarter report with an awkward mismatch between its story and its stock. Last quarter management delivered its fastest organic growth in more than two years, the best adjusted EBITDA in eight quarters and a record for its MirrorEye camera-monitor system. Since then, the shares have fallen 13.4% while the S&P 500 was essentially flat. The market is effectively asking whether the second quarter was a turning point or a high-water mark, and this report is the first real chance to answer.
The Street expects a loss of 5 cents a share on revenue of about $178.7 million. That would be a sharp improvement from the 18-cent loss in the same quarter last year, but revenue would be down roughly 15% from $210.3 million a year ago. The headline decline looks worse than the underlying picture. Management told investors that third- and fourth-quarter sales would land modestly below the second quarter's $181.4 million, and consensus sits right in that zone. In other words, analysts are not demanding a beat on the top line. They are asking Stoneridge to hit the softer trajectory it already laid out while showing that profitability holds up on slightly lower volume.
That makes margins the key test. Second-quarter adjusted EBITDA of $5.5 million owed a lot to cost discipline, with SG&A dollars barely moving even as sales jumped. Gross margin, however, fell nearly three points from a year earlier to 20.3%, hurt by currency and material costs, inventory charges tied to shifting North American MirrorEye sales from retrofit kits toward factory-installed systems, and fading Smart2 tachograph demand after a regulatory push ended. Management described much of that pressure as transitory. If gross margin stabilizes or improves this quarter, the operating leverage story gains credibility. If it slips again while revenue eases, the second-quarter EBITDA performance will look more like a one-off, and the full-year adjusted EBITDA target of $20 million to $25 million, which was reaffirmed rather than raised, could start to look stretched toward the low end.
MirrorEye remains the growth engine worth tracking. Sales hit $37 million last quarter, up 39% from a year earlier, and the product now sits in more than 20 bus and coach programs plus agricultural and off-highway applications. The company also won its largest bus and coach award to date, worth about $42 million over its life, though full commercialization is not expected until 2027. Continued sequential growth, or at least holding near record levels through the retrofit-to-factory handoff, would support the thesis that Stoneridge is becoming less dependent on cyclical truck volumes. Equally important is whether management still believes North American commercial vehicle demand has bottomed, as it said last quarter, and whether stronger OEM order books are showing up in its own schedules. The industry forecast for 2026 was lifted sharply, but the 2027 growth outlook was cut on the view that orders were pulled forward, so any fresh commentary on next year matters.
The balance sheet offers another catalyst. Refinancing of the credit facility maturing in July 2027 was targeted for completion by the end of November, so an update on terms or timing would remove an overhang. Continued cash generation and inventory reduction, which improved last quarter, would help that process.
Sentiment has warmed noticeably, with bearishness easing from about 66% to 31% heading into this report, yet the stock trades near $5.89, below its 200-day average of $6.90 and not far above its post-earnings low of $5.63. Its range has shifted down from the prior quarter's $6.39 to $8.00 band. That combination suggests skepticism is priced in, but patience is thin. The central question is simple: can Stoneridge show that its margin gains are durable on flatter sales? If so, the improving narrative stays intact. If not, the recent selloff may prove to have been an early warning.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-19 | |
| Sep-23 | |
| Sep-14 | |
| Aug-27 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 | |
| Jul-22 | |
| Jun-30 | |
| Jun-25 | |
| Jun-03 |
