Stoneridge Beats On Adjusted EPS And Raises Sales Outlook, But Margin Erosion And An Arbitration Charge Cloud The Profit Story
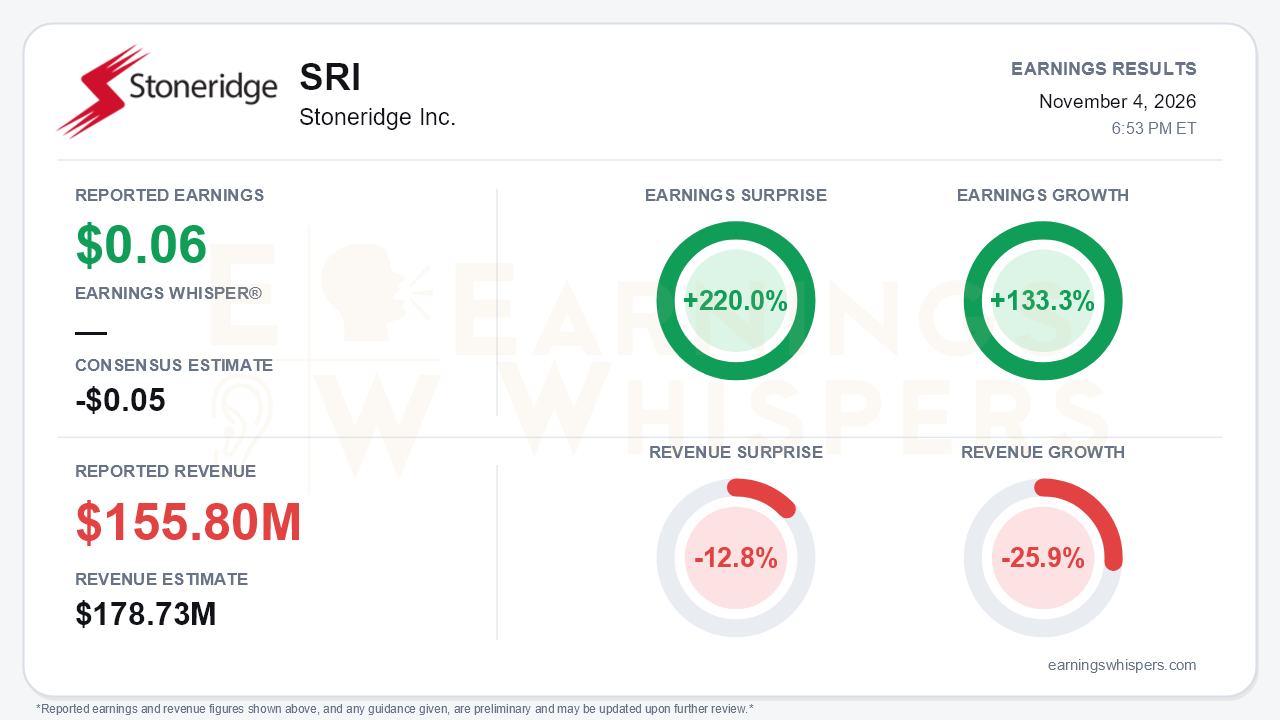
Stoneridge (NYSE: SRI) posted adjusted earnings of $0.06 per share for the third quarter, beating the consensus estimate for a $0.05 loss by 220.0%. Earnings grew 133.3% year over year, a swing from an adjusted loss of $0.27 a year earlier to a small adjusted profit. Reported revenue of $155.8 million missed the $178.73 million consensus by 12.8%. The miss was largely accounting rather than demand: the company booked a $24.2 million charge for a legacy PM sensor arbitration award as a reduction to net sales. Adjusted revenue of $180.0 million rose 29.9% and was slightly above the consensus figure. The central tension is that the top line is accelerating sharply while margins are going the wrong way. Management raised its sales outlook but pushed profit expectations to the low end of the range.
The headline numbers need some care. Earnings Whispers' normalized comparison shows revenue down 25.9% year over year. The company, measuring continuing operations after the Control Devices divestiture, reports GAAP sales up 9.5% in its financial tables and 12.4% in its highlights. On a GAAP basis, the loss from continuing operations widened to $22.9 million, or $0.81 per share, from $0.32. The quality of the adjusted beat also deserves scrutiny. Adjusted gross margin fell 382 basis points to 19.9%, worse than the 277-basis-point decline in the second quarter. Electronics adjusted operating margin dropped 217 basis points to 3.4%, after edging higher last quarter. Brazil's margin fell 411 basis points to 11.5% despite record sales of $21.5 million. Management blamed higher material costs, about $3 million of legacy warranty settlements that remained inside adjusted results, inventory write-down actions, and unfavorable mix in Brazil. Overhead cuts carried the bottom line: SG&A fell 317 basis points to 13.1% of adjusted sales, and adjusted EBITDA rose 41.7% to $7.3 million, up from $5.5 million in Q2 and $2.0 million in Q1.
Demand was the clear positive on the call. Organic growth reached roughly 26%, compared with about 8% in Q2, and ran well ahead of end markets. MirrorEye, the company's camera-based mirror replacement system, generated more than $37 million in revenue, up 48% year over year, with growth now led by North American OEM ramps. Management cited strong Class 8 order books extending into 2027. The company also won a roughly $180 million non-MirrorEye vision system order that ramps from early 2027, and announced a MirrorEye collaboration with Kodiak AI on autonomous trucks. Full-year adjusted sales guidance rose to $690-$700 million from $645-$670 million.
The profit outlook moved the other way. Adjusted EBITDA is now expected at the bottom of the $20-$25 million range, and adjusted gross margin guidance was cut a full point to 20.5%-21.0%. Management flagged memory-chip inflation that should worsen in Q4, along with weaker currency. More troubling for 2027, management declined to reaffirm its earlier targets of $750 million in revenue and about $44 million in EBITDA, deferring to the March call. Industry forecaster IHS's 2027 end-market growth estimate has fallen to about 3%, from 10% at the start of the year. The balance sheet adds another layer of risk. Net debt fell to $80.2 million, but the credit facility, now a current liability, matures in July 2027, and the refinancing has slipped from an end-of-November target to no stated date. The roughly $25.5 million arbitration award, if upheld, will be paid from cash.
Investor sentiment improved meaningfully, rising from -0.66 to -0.30. That still leaves it negative but far less bearish heading into the report. The price action has been less forgiving. Shares at $5.73 are down 15.7% since opening at $6.80 after the August report and sit about 17% below the 200-day moving average of $6.90. The Earnings Whispers trend signals lean negative, with price, sequential growth, and AVWAP all weak, though momentum is a modest exception.
Bulls can point to accelerating organic growth, record MirrorEye revenue, new multi-year orders, and real cost discipline. Bears have legitimate ammunition in four places: margins are falling even as sales accelerate, warranty and inventory cleanup costs keep recurring, the refinancing is unresolved, and the 2027 targets have been pulled into question.
The bottom line is that Stoneridge's demand problem appears to be fading while its profitability problem is not. The adjusted beat and revenue raise show the franchise is winning business. Until gross margins stabilize, the refinancing closes, and management restates credible 2027 targets in March, faster growth is not yet translating into the earnings power investors were promised.
Read our earnings preview for Stoneridge Inc.: https://www.earningswhispers.com/article/SRI/22029
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-19 | |
| Sep-23 | |
| Sep-14 | |
| Aug-27 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 |
