Ruger Faces Backorder Test As Investors Bet Its Q2 Breakout Can Last Into Fall
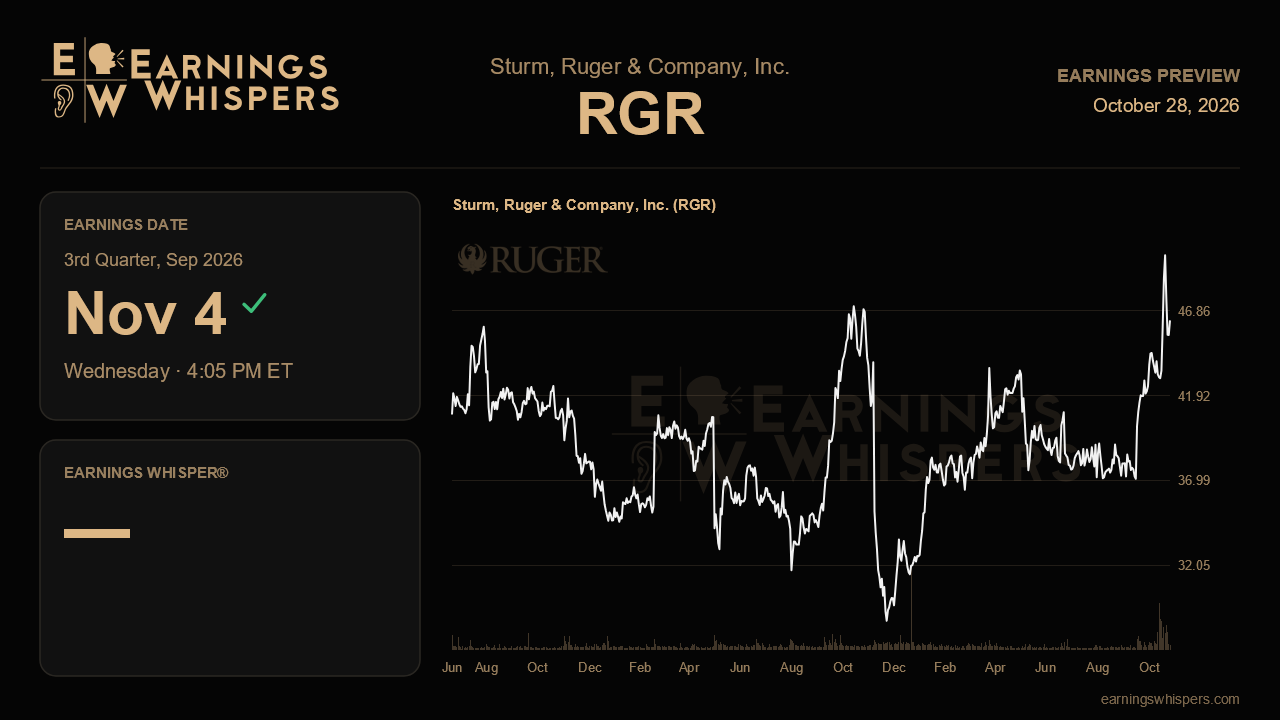
Sturm, Ruger & Company enters its third-quarter report with something it has not had in a while: genuine operating momentum and a stock price that reflects it. The question now is whether the second quarter's surge was the start of a durable upswing or a catch-up quarter flattered by recovered production. With units on backorder rising and some new product launches deferred to keep up with demand, the November 4 release, due after the close, should show whether Ruger can turn a demand problem into a supply solution.
The year-ago comparison is undemanding. Ruger earned just $0.10 per share on $126.8 million in revenue in the third quarter of last year, so even a modest step down from the second quarter's $0.52 in adjusted earnings and $158.1 million in sales would still produce strong year-over-year growth. No published consensus figure gives a usable read on the Street's bar, and the company does not issue numeric guidance. Its reaffirmed 2026 priorities and capital spending of roughly $30 million are the closest thing to a formal outlook. That leaves the second quarter's trajectory as the real benchmark.
That trajectory was impressive. Sales growth accelerated to 19% from about 4% in the first quarter, adjusted EBITDA margin widened to 10.5% on premium product mix and manufacturing efficiencies, and cash and short-term investments climbed to $118 million. The most persuasive detail was demand quality. Distributor sell-through rose 19% while adjusted NICS background checks grew only about 5%, and distributors trimmed inventory at the same time. That points to consumers pulling product off shelves rather than channel restocking, which is the kind of growth that tends to persist. Confirmation this quarter would look like sell-through continuing to outpace the broader market as the fall hunting season brings traffic back after a seasonally slow summer.
The swing factor is production. Management fixed the first quarter's storm-related shortfall of roughly 30,000 units and rebuilt finished goods inventory, yet backorders still rose. If Ruger shipped more units in the third quarter, the backlog becomes an earnings tailwind and supports further margin leverage. If backorders keep climbing without a matching rise in shipments, the story shifts from strong demand to constrained capacity, and the pilot work on mini-cell and fifth-axis machining under the newly formalized Ruger Business System will need to prove its worth quickly. New product share of firearm sales slipped to 29% from 41%, partly a mechanical effect as the American Gen 2 rifles aged out of the two-year window, but a further slide would raise questions about launch cadence. Updates on the Harrier MSR accessory push and the 250th anniversary products would help show the pipeline is intact.
The market has already rewarded the turnaround. Shares have climbed 15.5% since the last report, beating the S&P 500 by nearly 11 points, and at $46.31 the stock sits well above its 200-day moving average of $39.56. It has, however, pulled back roughly 9% from its post-earnings high of $50.84, and sentiment, while still bullish, has cooled to 16.5% from 27.2% heading into the prior report. That combination suggests enthusiasm has been tempered rather than abandoned, and that the stock is no longer priced for perfection.
The central issue is whether Ruger can convert consumer-led demand into shipped units without sacrificing margin. Sales growth well above last year's depressed base, sell-through still beating NICS, and a shrinking or stable backorder book would confirm that the second quarter was an inflection. Stalling shipments or margin giveback would suggest the breakout was more about recovering lost production than building lasting momentum.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-21 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Sep-17 | |
| Sep-16 | |
| Aug-18 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-28 | |
| Jul-15 | |
| Jun-18 |
